The Cost of Poor Bookkeeping: Hidden Expenses for SMEs
Bookkeeping is one of the most important functions in any business, yet it is often overlooked by small and medium-sized enterprises (SMEs).…
Read article
Does operating from a UAE free zone mean your company is automatically exempt from VAT registration? Not necessarily. Although free zones offer several business advantages, companies established in these areas must still assess their VAT obligations under UAE tax legislation.
Understanding VAT Registration for UAE Free Zone Companies is particularly important because the applicable requirements depend on the nature of business activities, taxable supplies, imports and the specific VAT treatment of transactions. Some free zones receive special treatment as Designated Zones, but this does not provide a general exemption from VAT.
Businesses must evaluate their turnover, maintain supporting financial records and monitor registration requirements to avoid unnecessary compliance issues.
Yes. A company established in a UAE free zone may need to register for VAT if it meets the applicable registration criteria.
VAT applies to taxable economic activities conducted in the UAE, regardless of whether a business operates from a mainland location or a free zone. Therefore, free zone companies should not assume that their location automatically exempts them from registration.
The Federal Tax Authority considers the value and nature of a company’s taxable supplies and imports when determining its registration obligations.
For example, a free zone company providing consultancy services to UAE customers may need to register once its taxable supplies meet the mandatory threshold. Similarly, a trading company importing goods into the UAE should assess the VAT treatment of its imports and subsequent transactions.
When assessing VAT Registration for UAE Free Zone Companies, businesses should consider:
These factors help determine whether the company must register or can apply voluntarily.
One of the most important considerations when assessing VAT Registration for UAE Free Zone Companies is the difference between an ordinary free zone and a Designated Zone.
Not every UAE free zone is treated as a Designated Zone for VAT purposes. Only specific free zones listed under the relevant Cabinet decisions receive this special treatment.
A Designated Zone is a specific area recognized under UAE VAT legislation that receives special VAT treatment, mainly concerning certain supplies of goods.
For qualifying transactions, certain goods supplied within a Designated Zone may be treated as outside the UAE for VAT purposes, subject to the applicable conditions.
However, this treatment has limitations:
For example, a company trading goods within a qualifying Designated Zone may receive different VAT treatment from a consultancy business operating from the same location.
No. Designated Zone status does not automatically exempt a company from VAT registration.
The FTA confirms that businesses established in Designated Zones and engaged in trading goods may still need to register depending on their activities, supplies and applicable registration thresholds.
Therefore, companies should assess their individual transactions rather than relying solely on their free zone licence or location.
The VAT registration thresholds are important when determining whether a free zone company must register or can apply voluntarily.
The general UAE thresholds are:
| Registration Type | Threshold | Registration Condition |
| Mandatory VAT registration | AED 375,000 | Taxable supplies and imports exceed the threshold |
| Voluntary VAT registration | AED 187,500 | Taxable supplies, imports or taxable expenses exceed the threshold |
These thresholds generally apply to UAE-resident businesses, including qualifying free zone companies.
A free zone company must register when the value of its taxable supplies and imports:
The assessment is not limited to the company’s annual financial statements. Businesses should monitor their rolling 12-month position and expected transactions separately.
For example, consider a free zone trading company with AED 310,000 in relevant taxable supplies and imports during the previous 12 months. It then signs a confirmed contract expected to generate another AED 90,000 in taxable supplies within the next 30 days.
The company should assess its registration obligation based on this expected activity rather than waiting for the next financial year.
A company that does not meet the mandatory registration criteria may qualify for voluntary registration if its taxable supplies, imports or taxable expenses exceed AED 187,500 during the previous 12 months or are expected to exceed this amount during the next 30 days.
This option may be useful for newly established free zone businesses that incur substantial VAT-bearing expenses before generating significant sales.
For example, a newly established company may purchase office equipment, professional services and business software while preparing to launch its operations. If its qualifying taxable expenses exceed AED 187,500 and the applicable conditions are satisfied, it may be eligible to apply voluntarily.
However, companies should assess whether voluntary registration is commercially beneficial, particularly when their customers are not VAT-registered businesses.
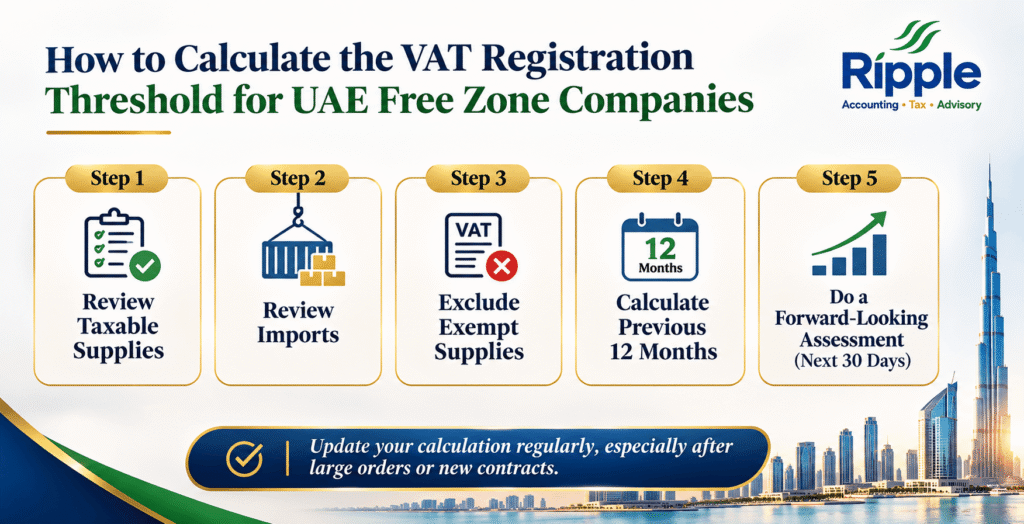
Accurate threshold calculations are essential when assessing VAT Registration for UAE Free Zone Companies.
Businesses should not simply add all revenue shown in their accounting records. The calculation must consider the VAT treatment of each transaction.
A practical assessment involves the following steps:
Identify the value of goods and services supplied by the company that qualify as taxable supplies under UAE VAT legislation. This includes relevant standard-rated and zero-rated supplies.
Identify relevant imports and their VAT treatment. Companies involved in international trading should examine customs documentation and import records to establish which amounts must be included.
Exempt supplies should not be treated as taxable supplies when calculating the relevant threshold. Businesses must distinguish exempt transactions from zero-rated supplies, as zero-rated supplies remain taxable supplies.
Prepare a rolling 12-month calculation using sales invoices, import documentation, accounting records and other relevant evidence.
Review contracts, purchase orders, confirmed sales and other supporting information to determine whether the relevant threshold is expected to be exceeded during the next 30 days.
This calculation should be updated regularly, especially when the business receives large orders or enters into new commercial agreements.
The next-30-days test is an important part of VAT Registration for UAE Free Zone Companies because a business may become required to register before its historical turnover reaches AED 375,000.
Under the FTA’s registration criteria, businesses must consider whether their taxable supplies and imports are expected to exceed the mandatory threshold during the next 30 days.
A forecast should be based on reasonable commercial evidence rather than an unsupported estimate.
Relevant supporting records may include:
For instance, a free zone company may have generated AED 250,000 in taxable supplies during the previous 12 months. However, it signs a contract for a taxable project worth AED 400,000, with the relevant supply expected within the next 30 days.
The business should assess its registration obligation immediately based on the available evidence. It should not wait until the entire project is completed or the revenue appears in its annual accounts.
A documented forecast also helps demonstrate how the company assessed its registration position if the FTA requests supporting information.
Preparing the correct documents can help businesses complete their VAT registration applications more efficiently. The FTA requires supporting information based on the company’s legal structure and registration circumstances.
The following table outlines commonly relevant documents:
| Document | Why It May Be Required |
| Valid free zone trade licence | Confirms the company’s licensed business activities |
| Certificate of incorporation | Establishes the company’s legal identity |
| Memorandum of Association (MOA) | Provides details about the company’s structure and ownership |
| Passport and Emirates ID copies | Identifies owners and authorised signatories, as applicable |
| Power of attorney | Confirms the authority of an appointed representative, where required |
| Financial statements or management accounts | Supports the assessment of taxable supplies and business activity |
| Sales invoices and purchase records | Demonstrates historical transactions and turnover |
| Contracts and purchase orders | Supports expected taxable supplies during the next 30 days |
| Tax invoices for business expenses | Supports an application based on the voluntary expense threshold |
| Customs information | Helps explain relevant import activities, where applicable |
| Bank account details | Provides company banking information, where requested |
The FTA may also request a signed and stamped declaration showing taxable supplies and monthly sales from the company’s establishment date.
For businesses operating in Designated Zones, additional information may be required to demonstrate their business flow, movement of goods and supply chain arrangements.
The exact document requirements depend on the legal entity and the nature of the application. Companies should check the latest FTA registration service requirements before submitting their applications.
Yes. A newly established free zone company may qualify for voluntary VAT registration even if it has not started generating significant sales.
This is particularly relevant for businesses that incur substantial taxable expenses during their initial setup period.
Under the voluntary registration rules, qualifying taxable expenses can be considered when assessing eligibility against the AED 187,500 threshold.
Examples of potentially relevant expenses include:
However, the company must satisfy the applicable conditions and provide sufficient supporting evidence.
For expense-based applications, the FTA’s registration requirements include at least five VAT invoices with amounts exceeding the registration threshold. Applicants should carefully review the FTA’s current documentation requirements before applying.
Voluntary registration may allow an eligible business to recover qualifying input VAT, subject to the normal recovery rules. However, registration also introduces responsibilities such as issuing appropriate tax invoices, filing VAT returns and maintaining tax records.
Therefore, businesses should consider both the potential benefits and ongoing obligations before choosing this route.
The VAT registration process for free zone companies is completed electronically through the FTA’s EmaraTax platform.
Businesses can follow these general steps:
Step 1. Create an EmaraTax account
Visit the FTA website and create an account using the company’s relevant contact details.
Step 2. Create a taxable person profile
Access the dashboard and create the company’s taxable person profile using its legal and registration information.
Step 3. Select VAT registration
Open the taxable person account and select the VAT registration option.
Step 4. Complete the application
Provide information about the company’s activities, legal structure, financial details, taxable supplies and registration category.
Step 5. Upload supporting documents
Attach the relevant trade licence, incorporation documents, financial records, contracts and other supporting evidence.
Step 6. Review and submit
Check that the information is accurate and consistent with the company’s supporting records before submitting the application.
Step 7. Monitor the application
Monitor the EmaraTax account for FTA updates or requests for additional information. Once approved, the VAT registration certificate and Tax Registration Number (TRN) will be available through the relevant account.
Businesses should ensure that all information is accurate because incomplete or inconsistent applications may require further clarification.
A company that becomes required to register must submit its VAT registration application within 30 days of becoming obligated to register, in accordance with the applicable VAT rules.
This deadline is important for businesses approaching the mandatory threshold or expecting significant taxable transactions.
Companies should not wait until the end of the financial year to assess their registration obligations.
Failing to apply within the prescribed timeframe may result in an administrative penalty. The business may also need to account for VAT from the date its registration obligation arose, subject to the applicable rules.
To avoid delays, companies should:
These practices help businesses manage registration deadlines and reduce the risk of unexpected tax liabilities.
Even businesses with established accounting systems can make mistakes when assessing their VAT obligations.
Some common issues include:
Reviewing these areas can help companies improve the accuracy of their VAT registration assessment.
Determining VAT registration eligibility can be challenging for free zone businesses, particularly when their activities involve international trading, services, imports or transactions within Designated Zones.
Ripple Accounting, Tax & Advisory provides VAT registration and filing support to help businesses understand their registration requirements and prepare the relevant financial information.
Our support can include:
Whether your company is newly established, approaching the mandatory threshold or considering voluntary registration, professional assistance can help you make informed decisions.
Book a free VAT registration consultation with Ripple Accountants to discuss your company’s registration requirements and documentation.
No. Free zone companies must assess their taxable supplies, imports and applicable registration thresholds. Registration becomes mandatory when the relevant criteria are met. Companies that do not meet mandatory criteria may qualify for voluntary registration.
The mandatory registration threshold is AED 375,000, while the voluntary registration threshold is AED 187,500. These thresholds generally apply to UAE-resident free zone companies, subject to the applicable VAT rules.
Not automatically. Designated Zones receive special VAT treatment for certain transactions involving goods, but this does not provide a general exemption from VAT registration. The company’s activities and taxable supplies must still be assessed.
Yes. A newly established company may qualify for voluntary registration if its qualifying taxable expenses exceed AED 187,500 and it meets the relevant FTA requirements. Supporting VAT invoices and other documentation may be required.
A business that becomes required to register must generally submit its application within 30 days of becoming obligated to register. Companies should monitor their turnover and expected transactions to identify when this requirement arises.
VAT registration is an important compliance responsibility for UAE free zone businesses. Although certain Designated Zones receive special VAT treatment, companies should not assume that operating from a free zone automatically removes their registration obligations. Understanding VAT Registration for UAE Free Zone Companies requires careful consideration of taxable supplies, imports, voluntary registration eligibility and expected transactions during the next 30 days. By maintaining accurate financial records, preparing supporting documents and monitoring registration thresholds, businesses can identify their obligations and approach the FTA application process with greater confidence.
Disclaimer: This article is intended for general informational purposes and does not constitute legal or tax advice. VAT treatment depends on the company’s specific activities and circumstances. Businesses should refer to the applicable UAE VAT legislation and FTA guidance or seek professional advice before making registration decisions.
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
 Bookkeeping
 is one of the most important functions in any business, yet it is often overlooked by small and medium-sized enterprises (SMEs).…
Read article Compliance
Businesses today generate more financial and operational data than ever before. Every invoice, payment, approval, and customer transaction creates valuable information that…
Read article Compliance
Lease accounting has become one of the most important areas of financial reporting for businesses that rent offices, warehouses, vehicles, machinery, or…
Read articlePage 67 of 67
Book a free consultation and get clear answers for your business.
0 Comments