Inventory Valuation Methods: FIFO, LIFO, and Weighted Average
Inventory valuation is one of the most important aspects of accounting and inventory management. Every business that buys, manufactures, or sells products…
Read article
Has your business received a notification that its VAT registration application has been rejected by the Federal Tax Authority (FTA)? An incomplete application, inconsistent financial information or missing supporting documents can create problems during the registration process.
When a UAE VAT registration application rejected, businesses should first understand the reason provided by the FTA before submitting another application. Repeating the same mistakes can lead to further delays and additional compliance concerns. Whether the issue relates to turnover calculations, the next 30-day forecast, business documentation or eligibility, identifying the underlying problem is essential.
This guide explains the common reasons for rejection, how to respond to FTA requests, which records to review and how businesses can prepare a stronger VAT registration application.
A VAT registration application is submitted through the FTA’s EmaraTax platform. The authority reviews the applicant’s information, eligibility and supporting documentation before deciding whether to approve the registration.
If the UAE VAT registration application is rejected, it means the FTA has not approved the submitted registration request.
However, businesses should distinguish between two important application statuses:
The FTA’s official VAT FAQ explains that applicants can check their application status through the EmaraTax dashboard. Where an application is marked Resubmit, the applicant should check the registered email address for the FTA’s comments and make the necessary adjustments.
A resubmission request should not automatically be treated as a final rejection. Responding accurately to the FTA’s specific comments may allow the existing application to proceed.
Businesses should therefore check the exact status and notification before taking further action.
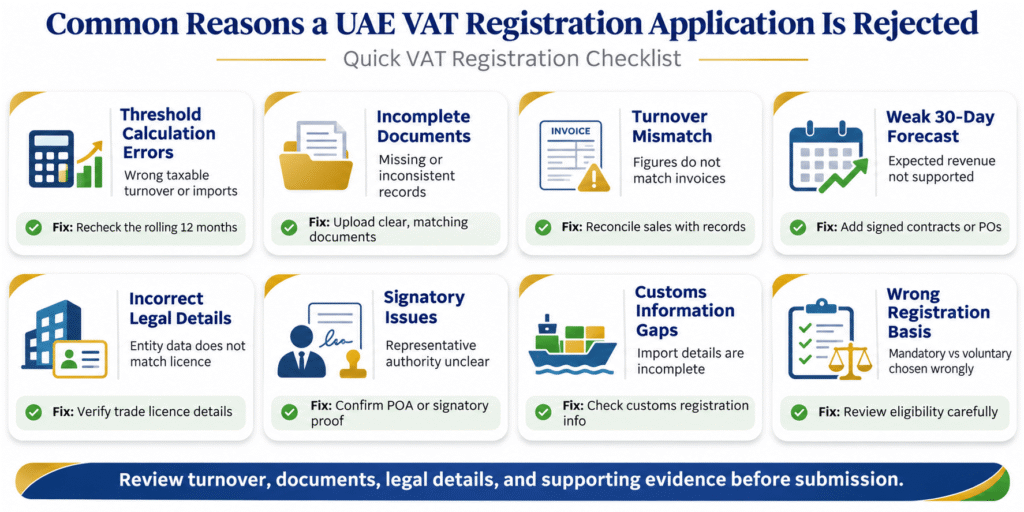
The FTA reviews different aspects of a VAT registration application, including the applicant’s eligibility, legal information, financial declarations and supporting evidence. The following are common application weaknesses that may lead to a request for clarification, resubmission or rejection, depending on the circumstances.
One important reason for registration problems is an incorrect assessment of taxable supplies and imports.
For UAE-resident businesses, mandatory VAT registration generally applies when the value of taxable supplies and relevant imports exceeds AED 375,000 during the previous 12 months or is expected to exceed this threshold within the next 30 days.
Voluntary registration may be available when qualifying taxable supplies, imports or taxable expenses exceed AED 187,500 during the relevant period.
Errors can occur when businesses:
For example, a company may declare AED 400,000 in annual revenue but include AED 80,000 of exempt income in that amount. Its actual qualifying taxable turnover may be lower than the declared figure.
The business should classify its transactions correctly and provide a calculation supported by accounting records.
How to fix it:
Review the previous 12 months of transactions, identify qualifying taxable supplies and relevant imports, and reconcile the calculation with monthly sales reports, invoices and accounting ledgers.
For a detailed explanation, read our guide on How to Calculate Taxable Turnover for UAE VAT Registration.
Missing or inconsistent documents can prevent the FTA from verifying the information provided in the registration application.
For example, a business may submit a trade licence without providing the required incorporation documents, identification details or evidence of the authorized signatory’s authority.
Other common document problems include:
The FTA’s document requirements vary according to the applicant’s legal structure and circumstances.
How to fix it:
Prepare a document checklist before submitting the application. Verify that company names, licence details, ownership information and authorised signatory details match the relevant official records.
Ensure that scanned documents are complete, readable and uploaded in the required format.
The turnover declared in a VAT registration application should be consistent with the supporting financial information.
If the monthly sales declaration shows one amount but the submitted invoices, accounting ledger or bank-related evidence suggests another, the FTA may request clarification.
For example, a business may declare AED 390,000 in taxable supplies but provide monthly sales records totalling only AED 320,000.
Without a clear reconciliation, the FTA may have difficulty verifying whether the registration criteria have been met.
Possible causes include:
How to fix it:
Reconcile the declared turnover with monthly sales records and supporting invoices. Explain any legitimate differences, including adjustments and excluded transactions, using appropriate documentation.
Businesses should also ensure that the turnover declaration is properly signed and stamped by the authorised signatory.
Businesses can become eligible or required to register based on expected taxable supplies and imports within the next 30 days. However, projected revenue must be supported by reliable commercial evidence.
A company may submit a VAT registration application based on expected sales without providing sufficient evidence of those transactions.
For example, a consultancy business may forecast AED 400,000 in upcoming revenue but provide only an internal spreadsheet without signed contracts or confirmed purchase orders.
This may make it difficult for the FTA to verify the basis of the forecast.
How to fix it:
Support expected revenue with relevant documents, such as:
The FTA’s VAT registration service specifically identifies valid purchase orders and contracts, signed and stamped by both parties, as supporting evidence for expected revenue.
The forecast should reflect genuine commercial expectations rather than unsupported estimates.
The legal information in the application must accurately represent the applicant. Problems can arise when businesses enter outdated company details or provide information that does not match their official registration documents.
Examples include:
These differences may require additional verification before the FTA can proceed.
How to fix it:
Review the company’s latest trade licence, incorporation documents and other relevant legal records before completing the application.
Make sure the selected legal entity type and business information correspond with the official documents.
Where a company has recently changed its ownership, management or registered details, check that the relevant amendments have been completed and supporting evidence is available.
The individual submitting a VAT registration application must have appropriate authority to act on behalf of the business.
Problems may occur when the application is signed by someone whose authority is not adequately established.
For example, a company employee may submit an application without the required authorisation documents, or the named representative may not match the details in the company’s constitutional documents.
How to fix it:
Confirm the authorised signatory before submitting the application.
Where required, provide the relevant Power of Attorney or other acceptable authorisation documents. Check that the individual’s identification details are accurate and consistent across the application.
Businesses involved in importing goods may need to provide relevant customs information during VAT registration.
Incomplete or incorrect customs details can create verification issues, particularly when the information does not match the company’s import activities.
For example, a trading company may report significant import transactions but fail to provide the relevant customs registration information.
How to fix it:
Review the company’s import activities and relevant customs records. Provide the applicable customs registration information and ensure that the declared import activity is consistent with the supporting documentation.
Where the business does not undertake relevant import activities, it should ensure that the application accurately reflects its circumstances.
A business must select the appropriate registration basis when completing its application.
Problems can occur when a company applies for mandatory registration despite not meeting the applicable criteria, or when it selects voluntary registration without sufficient evidence of qualifying supplies, imports or expenses.
Non-resident businesses also have different registration considerations. In certain circumstances, they may be required to register without meeting the usual UAE-resident turnover threshold.
How to fix it:
Reassess the registration basis before submitting or correcting the application. Determine whether the business qualifies for mandatory registration, voluntary registration or a relevant exception. Review the nature of its activities and the applicable rules for its legal and residency status.
When a UAE VAT registration application rejected, businesses should avoid immediately submitting another application without reviewing the decision. A structured review can help identify the issue and prevent the same mistakes from occurring again.
Determine whether the issue concerns:
Identifying the exact issue is important because different problems require different supporting evidence.
The FTA’s published VAT registration service currently indicates an estimated completion period of 20 business days from receipt of a completed application. This is an estimated processing period, not a guarantee of approval.
Preventing application problems is generally easier than correcting them after submission.
Businesses should conduct a basic review of their financial and legal information before completing the VAT registration form.
Confirm whether the company meets the mandatory or voluntary registration criteria.
For UAE-resident businesses, the main thresholds are:
| Registration category | Threshold |
| Mandatory VAT registration | AED 375,000 |
| Voluntary VAT registration | AED 187,500 |
Assess the previous 12-month period and relevant expectations for the next 30 days. Do not rely exclusively on annual revenue or accounting profit.
The FTA requires an official declaration of total taxable supplies and monthly sales from the establishment date until the application date.
The declaration should be signed and stamped by the authorised signatory. Before submission, reconcile the figures with the accounting records and supporting invoices.
Check the following information:
If registration eligibility depends on upcoming transactions, ensure that the relevant contracts and purchase orders are available.
The forecast should be consistent with the business’s actual commercial activities.
Yes, a business may be eligible for voluntary VAT registration if it meets the applicable requirements. However, rejection of a mandatory registration application does not automatically mean that the business qualifies for voluntary registration.
For UAE-resident businesses, voluntary registration is generally available when the value of qualifying taxable supplies, imports or taxable expenses exceeds AED 187,500 during the previous 12 months or is expected to exceed that amount within the next 30 days.
Consider a newly established UAE consultancy business that has generated AED 140,000 in taxable supplies but incurred AED 210,000 in qualifying VAT-bearing business expenses.
Although it has not reached the mandatory registration threshold, it may qualify for voluntary registration based on its taxable expenses, subject to the applicable conditions and supporting evidence.
Depending on the basis of application, the business may need:
The business should also consider the ongoing responsibilities associated with VAT registration, including maintaining tax records, issuing compliant tax invoices and filing VAT returns.
If the application was rejected because the supporting expense evidence was insufficient, simply selecting voluntary registration will not resolve the underlying problem.
If the FTA continues to reject an application, the business should carefully examine the decision and determine whether the issue relates to eligibility, missing evidence, incorrect information or another legal concern.
The appropriate next step depends on the nature of the decision.
Businesses should:
The UAE tax procedures framework provides a formal reconsideration process for certain decisions made by the FTA.
Under the applicable tax procedures, a person who disagrees with an FTA decision may submit a reconsideration request within 40 business days of notification of the decision, subject to the applicable requirements.
However, businesses should distinguish between challenging a decision and correcting an incomplete registration application.
A reconsideration request is not automatically the appropriate response to every rejected VAT registration application. Applicants should first establish whether the particular decision is eligible for reconsideration and review the relevant procedural requirements.
For further information, consult the UAE Government’s official guidance on Resolving Tax Disputes.
A rejected application does not automatically mean that a business has failed to meet its VAT obligations. The effect depends on whether the business was legally required to register and the reason for the rejection.
For example, a company that has exceeded the mandatory registration threshold should not assume that its VAT obligations disappear simply because its application has been rejected.
A person required to register must generally submit the application within 30 days of becoming required to register.
Late registration can result in penalties under the applicable tax legislation.
Businesses should therefore:
Where a business has already become liable for registration, professional advice can help it understand its responsibilities while resolving the application issue.
A rejected VAT registration application can create uncertainty for business owners, especially when the FTA requests additional financial information or identifies inconsistencies in the submitted documents.
Ripple Accounting, Tax & Advisory supports UAE businesses with VAT registration and filing services, helping them review their registration information and address documentation issues.
The team can assist with:
If your UAE VAT registration application has been rejected or returned for corrections, reviewing the underlying issue before proceeding can help reduce avoidable delays.
Contact Ripple Accounting, Tax & Advisory for assistance with VAT registration documentation, eligibility reviews and application preparation.
A VAT registration application may be rejected because of eligibility issues, incorrect turnover declarations, incomplete supporting documents, inconsistent legal information or insufficient evidence of expected revenue. Applicants should review the FTA’s notification to identify the specific reason.
It depends on the application status. If the application is marked Resubmit, you can generally edit the application and provide the information requested by the FTA. If it is marked Rejected, review the decision and follow the appropriate procedure for a fresh application or reconsideration, where applicable.
The FTA’s published VAT registration service currently indicates an estimated completion period of 20 business days from the date it receives a completed application or resubmission. Actual processing may depend on the completeness of the information and any additional verification required.
Yes, if your business independently meets the voluntary registration conditions. The general voluntary threshold for UAE-resident businesses is AED 187,500 in qualifying taxable supplies, imports or taxable expenses during the previous 12 months or expected within the next 30 days.
Incorrect or inconsistent turnover calculations may lead the FTA to request clarification, require corrections or reject an application where eligibility conditions are not met. Businesses should reconcile taxable supplies and relevant imports with their invoices, monthly sales reports and accounting records before applying.
A rejected VAT registration application can delay a business’s registration process, but identifying the underlying problem is the first step towards resolving it. Businesses should review their registration eligibility, verify the accuracy of turnover declarations, organise supporting documents and provide reliable evidence for any expected revenue. They should also distinguish between a resubmission request and a formal rejection, as each requires a different response. Maintaining accurate financial information and reviewing the application before submission can help businesses avoid unnecessary registration delays.
For assistance with VAT registration reviews, supporting documentation and application preparation, contact Ripple Accounting, Tax & Advisory.
Disclaimer: This article provides general information about UAE VAT registration and application procedures. It is not individual tax or legal advice. The appropriate response to an FTA decision depends on the circumstances of the application and the applicable UAE tax legislation.
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
 Bookkeeping
Inventory valuation is one of the most important aspects of accounting and inventory management. Every business that buys, manufactures, or sells products…
Read article Bookkeeping
Non-current assets and capital expenditures play a critical role in a company’s long-term financial health. Whether you own a startup, manage an…
Read article Bookkeeping
Expanding into international markets is an exciting milestone for any business. It opens the door to new customers, increased revenue, and long-term…
Read articlePage 64 of 68
Book a free consultation and get clear answers for your business.
0 Comments