Prevent Payroll Fraud: Ghost Employees & Duplicate Payments
Could your payroll be paying employees who don’t exist or paying the same salary twice? You could be losing money to payroll…
Read article
The UAE Federal Tax Authority (FTA) has introduced important amendments to the Marking Tobacco and Tobacco Products Scheme through Federal Tax Authority Decision No. 18 of 2026, issued on 15 September 2026.
The UAE tobacco tax mark amendments 2026 affect businesses involved in the import, production and handling of cigarettes, electrically heated cigarettes and water pipe tobacco. The most significant changes include a reduction in the fee for purchasing tax marks, the introduction of a new tax mark design, and a detailed transition schedule for phasing out marks carrying the old design.
The amendments have different implementation dates depending on the provision. The consolidated FTA decisions show Decision No. 18 of 2026 taking effect from 1 October 2026 for the amended mark-design framework under Decision No. 3 of 2021, while the revised mark fee reflected in Decisions No. 3 of 2018 and No. 2 of 2019 applies from 1 January 2027.
For tobacco manufacturers, importers, distributors and other businesses handling designated excise goods, these dates should now form part of their 2026–2028 compliance planning.
The UAE tobacco marking regime requires specific excise goods to carry approved tax marks. These marks form part of the regulatory controls surrounding tobacco products and help identify products that have passed through the applicable excise compliance framework.
Under the amended Decision No. 3 of 2021, Designated Excise Goods include:
Earlier decisions separately addressed cigarettes and water pipe tobacco. Decision No. 3 of 2018 applies to all types of cigarettes, while Decision No. 2 of 2019 addressed water pipe tobacco and electrically heated cigarettes.
One of the most commercially relevant changes is the reduction in the fee payable for purchasing tax marks.
The amended fee is:
AED 0.036 per Mark
The fee must be paid by the importer or producer before the marks are issued.
For cigarettes, Article 2 of FTA Decision No. 3 of 2018 now states that the fee is AED 0.036 for each mark. The amendment note confirms that Decision No. 18 of 2026 reduced the previous fee from AED 0.084 to AED 0.036.
The same reduction applies under Decision No. 2 of 2019 for the designated products covered by that decision. The updated Article 3 specifies AED 0.036 per mark, with the amendment note again confirming the reduction from AED 0.084.
Businesses purchasing large quantities of marks should update their costing models, excise compliance processes and mark-ordering budgets.
For example, a company purchasing one million marks would see the mark fee calculated using AED 0.036 per mark once the updated fee becomes applicable, instead of the previous AED 0.084 rate.
Companies should nevertheless ensure that the correct rate is applied according to the relevant effective date and transaction period.
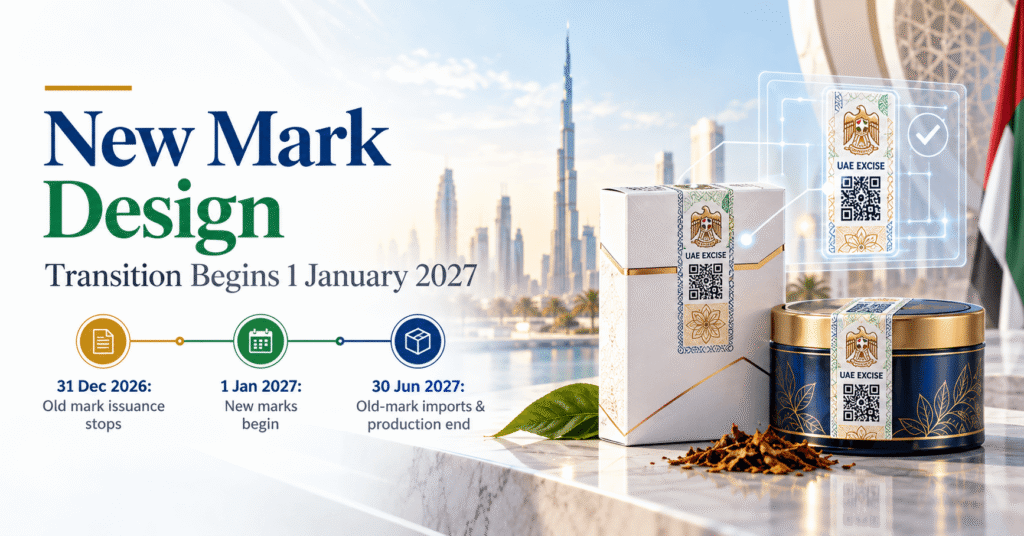
Decision No. 3 of 2021 has also been amended to introduce a new design for tax marks.
The Decision states that marks with the new design are approved and that approval will be withdrawn from marks carrying the old design.
Rather than requiring businesses to change immediately, the FTA has established a phased transition covering requests, issuance, imports, UAE production, returns of unused marks and the eventual prohibition of products carrying old marks.
Businesses should pay particular attention to the following dates:
This is the last day for payment of fees due on requests for marks carrying the old design.
Businesses with outstanding requests should therefore review whether payments connected with old-design marks need to be completed before this deadline.
The FTA will stop issuing and supplying marks with the old design.
This effectively closes the old-mark issuance process before the new system starts.
The FTA will begin:
The updated fees will also apply as part of this transition.
For importers and producers, this is a critical operational date because mark procurement procedures should be aligned with the new design from the beginning of 2027.
This is both:
Importers should therefore review shipments scheduled around this date, while local producers should monitor production plans and remaining stocks of old-design marks.
This is the last day for returning unused old-design marks.
Businesses holding unused marks should maintain accurate inventory records and establish an internal process to identify and return remaining old marks within the required timeframe.
The amended schedule ultimately prohibits the supply, transfer, storage or possession in the UAE of Designated Excise Goods bearing old-design marks at the earlier of:
This means businesses should not treat June 2027 as the end of the transition. Stock already produced or imported using old-design marks will also need to be monitored during the subsequent sell-through period.
The amendments do not remove the existing security obligations surrounding physical tax marks.
Under the marking decisions, marks must be securely stored before being affixed to designated excise goods. The minimum controls include:
Equivalent storage requirements are also included in Decision No. 2 of 2019. Businesses should therefore ensure that transitioning from old marks to new marks does not weaken existing inventory controls.
Businesses affected by the marking scheme should use the transition period to review their processes rather than waiting until the final deadlines.
A practical readiness review should include:
Businesses operating across manufacturing, importing, warehousing and distribution functions should coordinate these steps across tax, finance, operations, customs and supply-chain teams.
FTA Decision No. 18 of 2026 introduces more than a simple fee adjustment.
The amendments establish a structured migration to a new tax mark design while giving businesses defined periods to manage existing orders, production, imports, unused marks and old-mark inventory.
The immediate compliance priorities are the 15 December 2026 payment deadline, the 31 December 2026 end of old-mark issuance, and the 1 January 2027 launch of new-design marks and updated fees.
Companies dealing in cigarettes, electrically heated cigarettes or water pipe tobacco should map the full timeline through 2028 and ensure their excise tax controls, inventory records and supply-chain processes are updated accordingly.
The amended fee is AED 0.036 for each mark, reduced from AED 0.084.
Requests, issuance and supply of marks carrying the new design begin on 1 January 2027.
Issuance and supply of old-design marks will stop on 31 December 2026.
The last day for importing Designated Excise Goods carrying old-design marks is 30 June 2027.
Unused marks carrying the old design must be returned by 15 July 2027.
The amended Decision covers normal cigarettes, electrically heated cigarettes and qualifying water pipe tobacco.
The amendments introduced through FTA Decision No. 18 of 2026 update three key decisions governing the UAE’s tobacco marking scheme: FTA Decision No. 3 of 2018, FTA Decision No. 2 of 2019, and FTA Decision No. 3 of 2021. Together, the changes reduce the tax mark fee to AED 0.036 per mark, introduce a new mark design, and establish a clear transition timetable for phasing out old-design marks.
The amendments apply to cigarettes, electrically heated cigarettes, and qualifying water pipe tobacco, with important compliance dates running from December 2026 through June 2028. Businesses involved in importing, producing, storing, or supplying designated excise goods should review their mark inventories, payment schedules, production and import plans, and internal compliance controls to ensure a smooth transition to the new requirements.
Disclaimer: This article is for general informational purposes only and is based on the Federal Tax Authority decisions referenced above. It should not be considered tax, legal or regulatory advice. Businesses should review their specific facts, the applicable Arabic legislation and current FTA guidance before taking compliance action.
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
 Audit
Could your payroll be paying employees who don’t exist or paying the same salary twice? You could be losing money to payroll…
Read article VAT
Exporting goods and services from the UAE can provide significant VAT advantages when the conditions for zero-rated exports are met. Under the…
Read article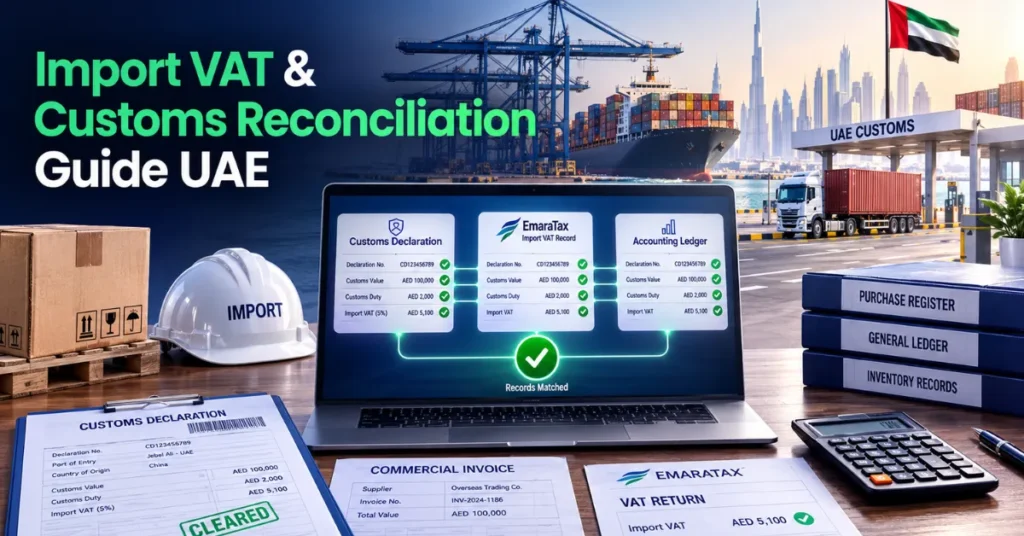 VAT
Businesses that import goods into the UAE must ensure their Import VAT records match their Customs declarations and accounting records. Accurate reconciliation…
Read articlePage 42 of 59
Book a free consultation and get clear answers for your business.
0 Comments