The Value of Personal Financial Statements for Business Owners
Running a successful business requires more than tracking company revenue and expenses. As a business owner, your personal financial position also plays…
Read article
When should your UAE consultancy recognise revenue: when you issue an invoice, receive payment, or complete the agreed service?
For service businesses, these events do not always happen at the same time. A consultancy may receive an advance payment in January, deliver work throughout February and March, and issue its final invoice in April. Recording the entire amount as revenue when cash arrives could distort the financial results for each month.
Understanding revenue recognition UAE services helps consultancies, agencies, and professional service providers report income in the correct accounting period. This guide explains the principles of IFRS 15, practical examples, common reporting errors, and the records businesses should maintain.
Revenue recognition is the accounting process of determining when a business has earned revenue and how much it should report in its financial statements.
For service businesses, the central question is whether the promised service has been transferred to the customer in accordance with the contract.
Under IFRS 15, Revenue from Contracts with Customers, revenue is recognised to reflect the transfer of promised goods or services to customers in an amount that reflects the consideration the business expects to receive. The standard uses a five-step model to determine the timing and amount of revenue.
In the UAE, the Federal Tax Authority states that businesses should prepare financial statements using accounting standards accepted in the UAE, with IFRS being the most frequently used standard. Businesses should confirm which accounting framework applies to their circumstances.
Revenue recognition is therefore not simply a matter of matching sales invoices with bank deposits. It requires an assessment of the contract, the service delivered, and the business’s entitlement to payment.
Service businesses often work under arrangements that make revenue timing less straightforward than a simple sale.
These may include:
If revenue is recorded too early, the business may overstate its income and profit for a reporting period. If it is recorded too late, the financial statements may understate the work already performed.
Accurate revenue recognition supports reliable management reports, budgeting, cash-flow planning, and financial statements. It also helps management understand whether reported growth reflects services delivered or simply invoices issued and payments collected.
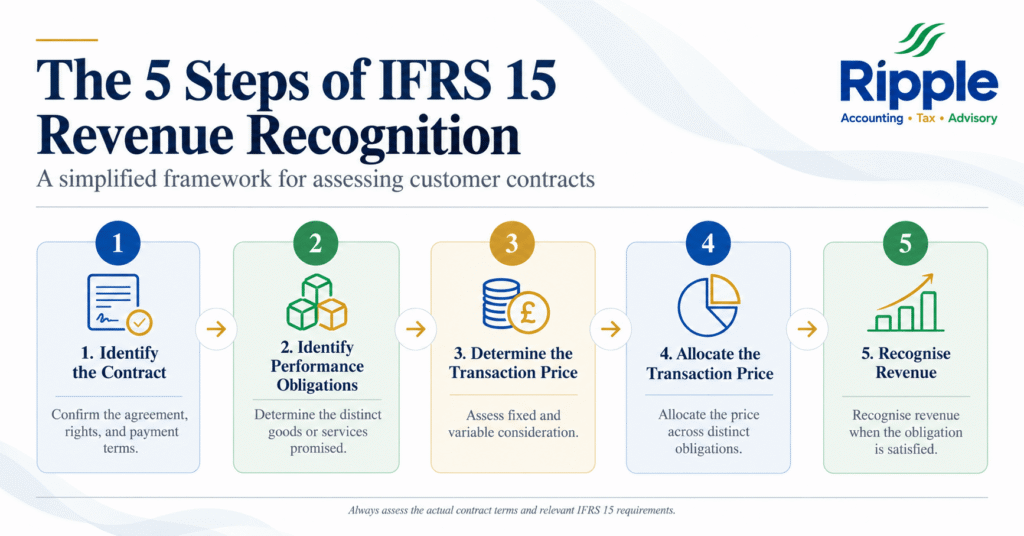
Businesses applying IFRS 15 should use its five-step framework to assess customer contracts.
Start by identifying the agreement that establishes the rights and obligations between the service provider and its customer.
The contract may be written, oral, or implied by customary business practices, provided the applicable IFRS 15 criteria are met.
Relevant documents can include:
For example, a UAE marketing agency signs an agreement to manage a client’s digital advertising campaigns for six months. The contract establishes the services to be provided, the payment terms, and the responsibilities of each party.
The agency should review the agreement before deciding how to recognise the related revenue.
A performance obligation is a promise to transfer a distinct good or service to the customer. A contract may contain one performance obligation or several, depending on the services promised and how they relate to one another.
For example, a consultancy may provide a business assessment, a separate training programme, and ongoing advisory support under one contract. If these services are distinct under IFRS 15, the business may need to account for them as separate performance obligations.
However, a list of deliverables does not automatically mean that each item is a separate obligation. The business must assess whether each promised service is distinct in the context of the contract.
This assessment matters because different obligations may be satisfied at different times.
The transaction price is the consideration the business expects to be entitled to in exchange for transferring the promised services. It may include a fixed fee, variable consideration, or both.
Examples include:
Where fees depend on performance or other uncertain outcomes, IFRS 15 contains requirements for estimating variable consideration and limiting the amount included in revenue until it is sufficiently certain that a significant reversal will not occur.
Businesses should therefore review contract terms carefully rather than automatically recording the maximum potential fee.
If a contract contains multiple performance obligations, the business generally allocates the transaction price based on the relative stand-alone selling prices of the distinct goods or services promised. For example, a consultancy charges AED 40,000 for a contract containing two distinct services:
If these are the relevant stand-alone selling prices and no other allocation considerations apply, the total transaction price can be allocated proportionately to the two services.
This allocation helps the business recognise the appropriate amount of revenue as each performance obligation is satisfied.
Finally, determine when the customer obtains the benefit or control of the promised service.
Under IFRS 15, revenue is recognised either over time or at a point in time, depending on the performance obligation and the relevant criteria.
Many recurring service arrangements qualify for recognition over time, but businesses must assess the actual contract rather than assume that every service contract does.
A performance obligation is satisfied over time when at least one of the criteria in IFRS 15 is met.
These criteria include situations where:
The third criterion requires careful assessment of the contractual terms and applicable law.
For many ongoing professional services, the customer receives and consumes the benefits as the work is performed. This may support recognition over time.
For example, a consultancy provides monthly financial reporting support for AED 12,000 per month. If it satisfies its performance obligation throughout the month, revenue would generally be recognised as the service is delivered rather than waiting until the customer pays.
The business should use an appropriate measure of progress that faithfully depicts its performance.
If none of the criteria for recognition over time is met, revenue is recognised at the point in time when the performance obligation is satisfied.
Consider a service provider engaged to deliver a specific report. Depending on the contract and the facts, the obligation may be satisfied when the completed report is transferred to the customer and the applicable recognition criteria are met.
The invoice date alone does not determine the recognition date.
Businesses should document why the obligation is satisfied at a particular point in time and retain evidence of delivery or acceptance where relevant.
A UAE consultancy charges AED 15,000 per month for ongoing advisory services.
Assume the services are provided evenly throughout the month and the performance obligation qualifies for recognition over time.
The business would generally recognise AED 15,000 as revenue for each month in which it delivers the agreed service.
If the customer pays three months in advance, the business should not automatically recognise all AED 45,000 as revenue when the payment arrives. Amounts relating to services not yet delivered are generally recorded as a contract liability until the relevant obligations are satisfied.
A UAE agency agrees to deliver a website project for AED 60,000.
The project includes planning, design, development, and testing. The business must determine whether these activities represent one combined performance obligation or multiple distinct obligations.
It must then assess whether the relevant obligation qualifies for recognition over time or at a point in time.
If the obligation qualifies for recognition over time, the agency should select a suitable measure of progress. If it does not, revenue is recognised when the obligation is satisfied at a point in time.
Important: Completing 50% of the internal task list does not automatically justify recognising 50% of the contract revenue. The measure must faithfully represent progress in transferring the promised service to the customer.
A consultancy agrees to provide services for AED 90,000, with invoices issued at three milestones:
These billing milestones determine when amounts become invoiced under the contract. They do not automatically determine when revenue should be recognised.
If the performance obligation is satisfied over time, revenue should be recognised based on an appropriate measure of progress. If it is satisfied at a point in time, the business should recognise revenue when the relevant obligation is satisfied.
The accounting assessment should follow the substance of the contract and IFRS 15 requirements.
A consistent monthly reporting process can help businesses identify differences between invoicing, cash collection, and services delivered.
Record the customer name, contract value, service description, start and end dates, billing terms, performance obligations, and recognition method.
Update the register whenever the scope, price, or delivery schedule changes.
Compare invoices issued with project records, timesheets, deliverables, service logs, and customer acceptance documents where relevant.
Investigate cases where invoicing is ahead of performance or where completed work has not yet been reflected in the accounting records.
A contract liability generally arises when a customer pays, or an amount becomes due, before the business transfers the related service.
A contract asset may arise when the business has transferred services but its right to consideration remains conditional on something other than the passage of time. A trade receivable, by contrast, generally represents an unconditional right to consideration.
Correct classification helps management understand how much revenue has been earned, what remains to be delivered, and what amounts are due from customers.
A useful report can include:
| Reporting item | What it shows |
| Revenue recognised | Income earned during the period under the applicable accounting framework |
| Invoices issued | Amounts billed to customers |
| Cash collected | Payments received during the period |
| Deferred revenue or contract liabilities | Amounts received or due before related obligations are satisfied |
| Contract assets | Rights to consideration that remain conditional |
| Unbilled work | Services delivered that have not yet been invoiced, where applicable |
| Outstanding receivables | Amounts customers owe under issued invoices |
These figures serve different purposes and should not be treated as interchangeable.
A year-end review should examine contracts, deliverables, invoices, receipts, and supporting project records.
Accurate revenue recognition gives business owners a clearer understanding of their financial performance and helps make monthly and year-end reporting more reliable.
Ripple Accounting, Tax & Advisory supports UAE businesses with financial reporting and accounting processes that help organise financial information and improve visibility over business performance.
Support may include:
If your consultancy or agency manages retainers, fixed-fee projects, milestone payments, or long-term client contracts, a structured review can help identify areas where revenue reporting needs improvement.
Contact Ripple Accounting, Tax & Advisory to discuss your financial reporting requirements and develop a process suited to your business.
Explore Ripple’s Financial Reporting Services
IFRS 15 provides a framework for recognising revenue from customer contracts. Businesses identify their performance obligations, determine and allocate the transaction price, and recognise revenue when or as the promised goods or services are transferred to customers.
Not necessarily. The invoice date does not automatically determine when revenue is recognised. Businesses should assess when the relevant performance obligation is satisfied under the applicable accounting framework.
Advance payments received before the related services are delivered are generally recorded as contract liabilities. Revenue is recognised as the relevant performance obligations are satisfied, subject to the applicable accounting requirements.
Yes. Revenue may be recognised over time when one of the IFRS 15 criteria is met. The business should use an appropriate measure of progress that reflects the transfer of services to the customer.
Revenue recognition affects accounting profit and the financial statements that may be used in determining taxable income. The UAE Corporate Tax framework includes rules on acceptable accounting standards and methods, so businesses should assess the applicable requirements and any relevant tax adjustments with a qualified adviser.
Revenue recognition is an essential part of reliable financial reporting for UAE consultancies, agencies, and other service businesses. Invoices, customer payments, and revenue earned are related, but they do not always occur in the same accounting period. By applying the relevant IFRS 15 principles, documenting performance obligations, reviewing contract terms, and reconciling revenue records regularly, businesses can produce more reliable financial reports and make better-informed decisions.
Need support with revenue reporting? Contact Ripple Accounting, Tax & Advisory to discuss financial reporting and accounting support for your UAE business.
Disclaimer: This article provides general information and does not constitute accounting, legal, or tax advice. The appropriate revenue recognition treatment depends on the applicable accounting framework, contractual terms, and facts of each arrangement. Consult a qualified professional for advice specific to your business.
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
 Bookkeeping
Running a successful business requires more than tracking company revenue and expenses. As a business owner, your personal financial position also plays…
Read article Audit
Financial fraud can happen in businesses of any size, from startups to multinational corporations. As the UAE continues to strengthen its regulatory…
Read article Bookkeeping
 is one of the most important functions in any business, yet it is often overlooked by small and medium-sized enterprises (SMEs).…
Read articlePage 57 of 58
Book a free consultation and get clear answers for your business.
0 Comments