The Value of Personal Financial Statements for Business Owners
Z Zobia July 10, 2026 17 min read
Running a successful business requires more than tracking company revenue and expenses. As a business owner, your personal financial position also plays a significant role in securing funding, making investment decisions, managing risks, and planning for long-term success. This is where Personal Financial Statements become essential. They provide a complete picture of your personal assets, liabilities, income, expenses, and overall net worth, helping you make informed financial decisions.
What Are Personal Financial Statements?
Personal Financial Statements are financial documents that summarize an individual’s financial position at a specific point in time. They help business owners understand what they own, what they owe, how much they earn, and how much they spend. Unlike business financial reports, these statements focus entirely on personal finances rather than company operations.
A well-prepared personal financial statement allows you to evaluate your financial health, calculate your net worth, monitor cash flow, and identify opportunities to improve your financial stability. It also serves as an important document when applying for loans, attracting investors, purchasing property, or planning future investments.
Definition of Personal Financial Statements
A personal financial statement is a document that lists all your personal assets, liabilities, income, and expenses to provide a complete overview of your financial condition. It helps determine your net worth and evaluates your ability to meet financial obligations.
Unlike company financial reports that focus on business profitability and operations, personal financial statements reflect your individual financial status. They support financial planning, wealth management, tax preparation, and informed decision-making.
Regularly updating these statements enables business owners to monitor progress toward financial goals while identifying areas where spending, saving, or investing can be improved.
Two Main Types of Personal Financial Statements
Most business owners rely on two primary financial statements to monitor their personal finances.
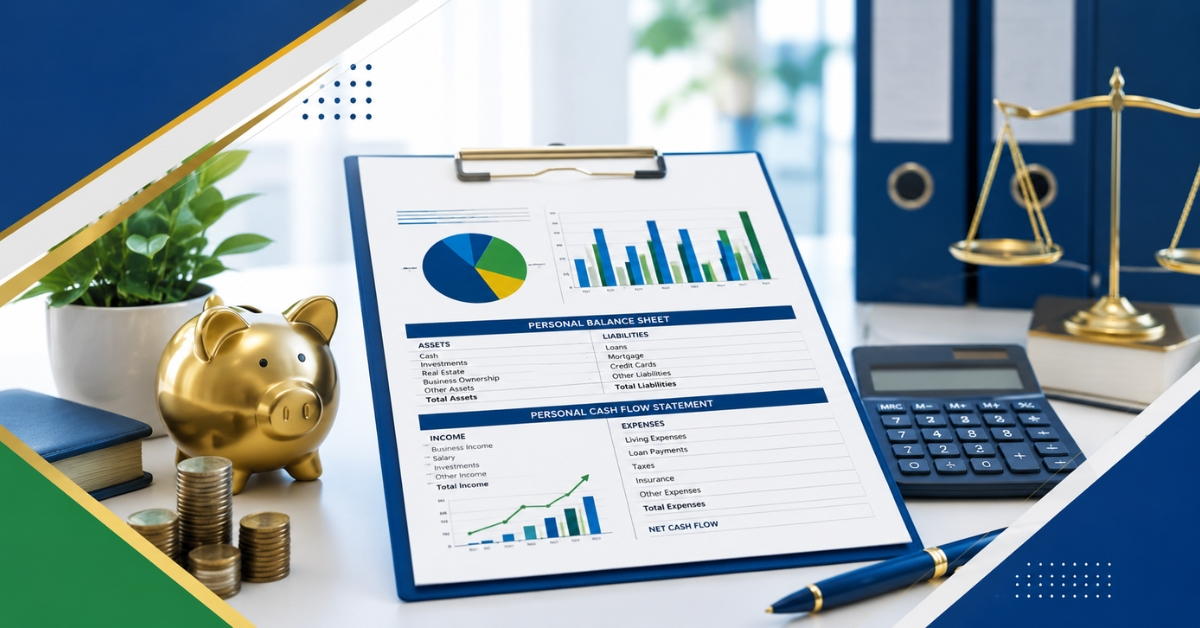
Personal Balance Sheet
A personal balance sheet provides a snapshot of your financial position by listing everything you own and everything you owe.
It generally includes:
Cash in hand and bank balances
Savings accounts
Investment portfolios
Real estate properties
Vehicles
Business ownership interests
Retirement accounts
Personal loans
Mortgage balances
Credit card debt
Other financial liabilities
The difference between your total assets and total liabilities represents your personal net worth.
Personal Cash Flow Statement
A personal cash flow statement tracks money coming in and money going out over a specific period.
It usually includes:
Salary or business income
Rental income
Investment income
Dividend income
Household expenses
Loan repayments
Utility bills
Insurance premiums
Taxes
Education expenses
Savings and investments
A positive cash flow means your income exceeds your expenses, while negative cash flow indicates that your spending is greater than your earnings.
Why Personal Financial Statements Matter for Business Owners
Many entrepreneurs assume that strong business financial statements alone are enough. In reality, lenders, investors, and financial advisors often evaluate both business and personal finances before making important decisions.
Personal Financial Statements help business owners understand their financial capacity, improve planning, and reduce financial risks.
They Show Your True Financial Position
Business profits do not always reflect personal financial health. A company may perform well while its owner carries significant personal debt or has limited liquid assets.
Personal Financial Statements provide a complete overview of:
Total personal assets
Outstanding liabilities
Available cash
Investment holdings
Property ownership
Overall net worth
This information allows business owners to assess financial stability and make better decisions regarding investments, borrowing, and long-term planning.
Understanding your personal financial position also helps identify unnecessary expenses, reduce debt, and improve savings strategies.
Banks Often Review Personal Finances
When applying for business financing, many banks request Personal Financial Statements in addition to company financial records.
Lenders want to determine whether business owners have the financial capacity to manage loan repayments if business income fluctuates. A strong personal financial profile increases confidence and may improve your chances of securing financing.
Financial institutions commonly use personal financial statements when evaluating applications for:
Business loans
Startup financing
Commercial mortgages
Equipment financing
Business credit lines
Personal guarantees
Investment funding
Accurate financial documentation demonstrates financial responsibility and strengthens your credibility during the approval process.
Better Financial Decision-Making
Good financial decisions require reliable information. Personal Financial Statements provide the data needed to evaluate financial opportunities and identify potential risks before making major commitments.
For example, before purchasing investment property or expanding your business, reviewing your personal balance sheet helps determine whether you have sufficient liquidity and borrowing capacity.
These statements also support better decisions regarding:
Investment planning
Retirement savings
Insurance coverage
Debt reduction
Wealth management
Estate planning
Asset protection
Business owners who regularly review their financial information are better prepared to respond to economic changes and unexpected expenses.
Improve Financial Discipline
Maintaining Personal Financial Statements encourages consistent financial habits and greater accountability.
Instead of relying on estimates, business owners can monitor their financial progress using accurate records. This improves budgeting, expense management, and long-term financial planning.
Regular financial reviews help you:
Monitor changes in net worth
Control unnecessary spending
Increase personal savings
Reduce outstanding debt
Improve cash flow management
Achieve financial goals faster
Strengthen overall financial health
Strong financial discipline benefits both personal wealth and business success, creating a more secure foundation for future growth.
Key Components of a Personal Financial Statement
Every Personal Financial Statement contains several essential components that provide a complete overview of your financial position.
Component
What It Includes
Why It Matters
Cash and Bank Balances
Cash, checking accounts, savings accounts
Provides immediate liquidity for daily expenses and emergencies
Investments
Stocks, bonds, mutual funds, ETFs, and other investments
Shows long-term wealth and income-generating assets
Real Estate
Residential homes, commercial properties, land
Represents significant personal assets and supports net worth calculations
Vehicles
Cars, motorcycles, recreational vehicles
Adds to total assets while reflecting current market value
Business Ownership
Shares or ownership interests in private businesses
Demonstrates personal investment in business ventures
Supports long-term financial security and retirement planning
Personal Loans
Bank loans, personal financing, borrowed funds
Records financial obligations that reduce net worth
Credit Card Debt
Outstanding balances on credit cards
Helps monitor short-term liabilities and debt management
Mortgage
Home loans and property financing
Represents one of the largest long-term liabilities for many business owners
Other Liabilities
Tax obligations, guarantees, unpaid bills, other debts
Ensures a complete and accurate picture of financial obligations
A comprehensive personal financial statement should include accurate values for each component and be updated regularly. Keeping detailed financial records improves financial transparency, supports informed decision-making, and makes it easier to respond to opportunities such as business expansion, investment, or loan applications.
Personal Balance Sheet Explained
A personal balance sheet is one of the most important Personal Financial Statements because it provides a snapshot of your financial position at a specific point in time. It shows everything you own (assets) and everything you owe (liabilities). The difference between these two figures is your personal net worth.
Business owners should review their personal balance sheet at least once a year or before making major financial decisions. This helps identify opportunities to increase wealth, reduce debt, and improve overall financial stability.
Assets
Assets are resources that have financial value and contribute to your overall net worth. Some assets are highly liquid and can be converted into cash quickly, while others are long-term investments.
Common personal assets include:
Cash in hand
Savings and current bank accounts
Fixed deposits
Stocks and mutual funds
Bonds and investment portfolios
Residential and commercial properties
Land and other real estate
Vehicles
Retirement savings
Valuable personal possessions
Ownership interests in private businesses
Keeping accurate records of your assets allows you to measure financial growth over time and make informed investment decisions.
Liabilities
Liabilities represent financial obligations that reduce your net worth. Monitoring liabilities helps business owners understand how much debt they carry and whether repayments remain manageable.
Common liabilities include:
Home mortgage
Personal loans
Business loans with personal guarantees
Vehicle financing
Credit card balances
Student loans
Tax liabilities
Outstanding utility bills
Other unpaid financial obligations
Reducing unnecessary debt can improve your financial health and strengthen your ability to qualify for future financing.
How Net Worth Is Calculated
Your personal net worth reflects your overall financial position and serves as a key indicator of financial stability.
Formula:
Net Worth = Total Assets − Total Liabilities
For example:
Total Assets: AED 2,500,000
Total Liabilities: AED 900,000
Net Worth = AED 1,600,000
Tracking your net worth annually helps you evaluate financial progress, measure wealth growth, and adjust your financial strategy when necessary.
Personal Cash Flow Statement Explained
While a balance sheet shows your financial position at one point in time, a personal cash flow statement tracks the movement of money over a specific period, such as a month or year. It highlights where your money comes from and where it goes. Understanding your cash flow helps ensure you have enough funds to meet personal and business obligations while supporting future investments.
Income Sources
Business owners often have multiple income streams. Recording each one provides a complete picture of available cash.
Common sources of income include:
Business profits
Salary
Rental income
Investment returns
Dividend income
Interest income
Freelance or consulting income
Other passive income
Diversifying income sources can improve financial security and reduce reliance on a single revenue stream.
Monthly Expenses
Monitoring expenses is equally important. Even high-income business owners can experience financial stress if spending consistently exceeds income.
Typical monthly expenses include:
Household expenses
Mortgage or rent
Loan repayments
Utilities
Insurance premiums
School fees
Transportation costs
Healthcare expenses
Taxes
Entertainment
Savings contributions
Investment contributions
A well-managed cash flow statement helps identify unnecessary spending and improves budgeting decisions.
Why Positive Cash Flow Matters
Positive cash flow means your income exceeds your expenses. This provides financial flexibility and creates opportunities to invest, save, and grow your wealth.
Positive cash flow allows business owners to:
Build emergency savings
Invest in business expansion
Purchase investment assets
Pay debts faster
Prepare for unexpected expenses
Increase retirement savings
Improve long-term financial security
Regularly reviewing cash flow helps prevent financial shortfalls and supports sustainable business growth.
Top Benefits of Personal Financial Statements
Maintaining updated Personal Financial Statements provides significant advantages for business owners, regardless of company size or industry.
Some of the key benefits include:
Provides a clear picture of your overall financial health.
Calculates your personal net worth accurately.
Improves business loan approval chances.
Supports mortgage and property financing applications.
Strengthens your creditworthiness with financial institutions.
Helps create realistic financial goals.
Supports smarter investment planning.
Simplifies retirement planning.
Assists with tax planning throughout the year.
Improves budgeting and expense management.
Identifies unnecessary debt and financial risks.
Makes estate planning more effective.
Supports wealth management strategies.
Helps prepare for unexpected financial emergencies.
Increases financial transparency when working with investors or lenders.
Business owners who maintain accurate financial records are generally better prepared to respond to economic changes and business opportunities.
When Should Business Owners Update Personal Financial Statements?
Updating your personal financial information regularly ensures that it remains accurate and useful for financial planning.
You should review and update your statements:
Before applying for a business loan.
Before seeking investor funding.
Before purchasing residential or commercial property.
Before refinancing existing loans.
Before filing annual taxes.
At the end of every financial year.
After purchasing or selling significant assets.
After paying off major debts.
Following major life events such as marriage or inheritance.
Before business succession or exit planning.
Many financial professionals recommend reviewing your personal financial statements at least once every year, even if there are no major financial changes.
Common Mistakes Business Owners Make
Even experienced entrepreneurs make mistakes when preparing their personal financial statements. Avoiding these common errors improves financial accuracy and decision-making.
1. Mixing Personal and Business Finances
One of the most common mistakes is combining personal and business transactions.
Using separate bank accounts and maintaining clear financial records makes accounting simpler and improves financial transparency.
2. Ignoring Certain Liabilities
Some business owners record obvious debts such as mortgages but overlook personal guarantees, tax obligations, or outstanding loans.
Including every liability provides a more realistic picture of your financial position.
3. Overvaluing Assets
Estimating asset values without considering current market conditions can inflate your net worth.
Use realistic market values for properties, vehicles, investments, and business ownership interests.
4. Forgetting Contingent Liabilities
Business guarantees, pending legal obligations, or co-signed loans may not require immediate payment, but they still represent potential financial risks.
Recording these obligations improves financial planning and risk management.
5. Not Updating Financial Statements Regularly
Financial information becomes outdated quickly.
Changes in investments, income, property values, or debt levels should be reflected promptly to ensure your statements remain accurate.
6. Ignoring Cash Flow
Some business owners focus only on assets while overlooking monthly income and expenses.
A healthy net worth does not always guarantee positive cash flow. Managing both is essential for long-term financial stability.
7. Missing Supporting Documentation
Financial statements should always be backed by supporting documents such as:
Bank statements
Investment reports
Property valuation documents
Loan agreements
Credit card statements
Tax records
Insurance documents
Maintaining organized financial documentation makes it easier to verify information during loan applications, investment discussions, audits, or financial reviews.
Avoiding these common mistakes helps business owners maintain accurate Personal Financial Statements, improve financial planning, strengthen lender confidence, and make better long-term business and personal financial decisions.
How to Prepare a Personal Financial Statement
Creating a personal financial statement does not have to be complicated. By following a structured process, business owners can build an accurate document that supports financial planning, loan applications, and long-term wealth management.
Step 1: Gather Your Financial Documents
Start by collecting all relevant financial records. Having complete and accurate information reduces errors and saves time.
Documents to gather include:
Bank statements
Investment account statements
Property valuation reports
Loan agreements
Mortgage statements
Credit card statements
Insurance policies
Retirement account statements
Business ownership documents
Tax records
Keeping these records organized also makes future updates much easier.
Step 2: List All Personal Assets
Prepare a detailed list of everything you own and assign a realistic market value to each asset.
Your asset list may include:
Cash and savings
Current accounts
Investments
Real estate
Vehicles
Retirement funds
Business ownership interests
Valuable personal belongings
Avoid overestimating values. Accurate reporting provides a clearer picture of your financial health.
Step 3: Record Every Liability
Next, list all financial obligations.
Include:
Mortgages
Personal loans
Vehicle financing
Credit card balances
Tax liabilities
Business guarantees
Other outstanding debts
Being honest about liabilities allows you to calculate your actual financial position.
Step 4: Calculate Your Net Worth
Once your assets and liabilities have been recorded, calculate your personal net worth.
Formula:
Net Worth = Total Assets − Total Liabilities
Reviewing your net worth regularly helps you monitor financial progress and identify opportunities to improve your financial position.
Step 5: Prepare a Monthly Cash Flow Statement
Record all monthly income and expenses.
Track:
Business income
Salary
Investment income
Rental income
Household expenses
Loan repayments
Utilities
Insurance
Taxes
Savings
Investments
Understanding your monthly cash flow helps you maintain financial stability and avoid unnecessary debt.
Step 6: Review and Update Regularly
Your financial position changes over time. Review your personal financial statement at least once a year or whenever significant financial events occur.
Regular updates ensure your information remains accurate for lenders, investors, and financial planning purposes.
Tools That Help Create Personal Financial Statements
Several tools can simplify the preparation and maintenance of personal financial statements. The right option depends on your financial complexity and reporting needs.
Tool
Best For
Key Advantages
Microsoft Excel
Individuals and small business owners
Fully customizable, flexible calculations, and easy reporting
Google Sheets
Collaboration and cloud access
Automatic saving, online access, and simple sharing
Personal Finance Apps
Everyday financial tracking
Automatic expense tracking and budgeting features
Accounting Software
Entrepreneurs with multiple financial activities
Integrated reporting and organized financial records
Professional Accountants
Complex financial situations
Expert guidance, accuracy, and compliance support
Financial Advisors
Long-term financial planning
Investment strategies, retirement planning, and wealth management advice
Using digital tools alongside professional advice can improve financial accuracy and reduce administrative workload.
Personal Financial Statements vs Business Financial Statements
Although both documents provide financial insights, they serve different purposes.
Personal Financial Statements
Business Financial Statements
Focus on an individual’s finances
Focus on company finances
Include personal assets and liabilities
Include business assets and liabilities
Measure personal net worth
Measure business profitability and financial performance
Used for personal loan applications and financial planning
Used for investors, lenders, tax authorities, and management
Include personal income and expenses
Include business revenue and operating expenses
Support retirement and wealth planning
Support business strategy and operational decisions
Prepared by individuals or financial advisors
Prepared by business accountants or finance teams
Updated based on personal financial changes
Updated according to accounting periods and reporting requirements
Business owners should maintain both personal and business financial statements to gain a complete understanding of their financial position.
How Personal Financial Statements Support Business Growth
Strong personal finances often contribute to stronger business performance. Lenders, investors, and financial institutions frequently evaluate a business owner’s personal financial position before approving financing or partnerships.
Better Loan Eligibility
Banks often assess personal financial statements alongside business financial records. A healthy personal balance sheet and positive cash flow can improve borrowing capacity and increase approval chances for business loans.
Greater Investor Confidence
Potential investors want to work with financially responsible entrepreneurs. Organized personal financial records demonstrate transparency, discipline, and effective financial management.
Improved Expansion Planning
Business expansion requires capital. Understanding your personal financial position helps determine whether you can safely invest additional funds or secure financing without creating unnecessary financial pressure.
Stronger Risk Management
Personal financial statements allow you to identify financial risks before they become significant problems. Monitoring debt levels, liquidity, and cash flow supports better financial decision-making.
Long-Term Wealth Creation
Successful entrepreneurs focus on building both profitable businesses and personal wealth. Regular financial reviews help balance business growth with personal investment planning, retirement savings, and wealth preservation.
Why Choose Ripple Accountants for Financial Advisory and Accounting Support
Managing both personal and business finances requires accuracy, consistency, and professional expertise. Ripple Accountants provides comprehensive accounting, bookkeeping, financial reporting, and advisory services that help business owners maintain organized financial records and make informed financial decisions. Whether you need assistance preparing financial statements, improving cash flow management, maintaining compliance, or planning for future business growth, our experienced professionals are ready to support your financial goals. Contact Ripple Accountants at +971 52 356 5409 or email info@uaetaxcompliance.ae to learn how our tailored accounting and advisory solutions can support your business.
FAQ
What is a personal financial statement?
A personal financial statement is a document that summarizes your assets, liabilities, income, expenses, and overall net worth. It provides a complete overview of your personal financial position.
Why do business owners need personal financial statements?
Business owners use personal financial statements to monitor financial health, support loan applications, improve financial planning, attract investors, and make informed financial decisions.
How often should I update my personal financial statement?
Review and update your statement at least once a year or whenever significant financial changes occur, such as purchasing property, taking on new debt, or making major investments.
What documents are required?
Common supporting documents include bank statements, investment reports, property valuations, loan agreements, mortgage statements, credit card statements, insurance records, and tax documents.
Do banks require personal financial statements?
Yes. Many banks request personal financial statements when evaluating business loan applications, particularly for startups, sole proprietors, partnerships, and businesses providing personal guarantees.
Can I prepare a personal financial statement myself?
Yes. Many business owners prepare their own statements using spreadsheets or personal finance software. However, professional accounting assistance can improve accuracy and ensure all financial information is properly documented.
What is the difference between a balance sheet and a cash flow statement?
A balance sheet shows your assets, liabilities, and net worth at a specific point in time. A cash flow statement tracks income and expenses over a period, helping you understand how money moves in and out of your finances.
Conclusion
Personal Financial Statements are far more than simple financial documents; they are valuable tools that help business owners understand their financial health, calculate net worth, manage cash flow, and plan confidently for the future. By maintaining accurate records of your assets, liabilities, income, and expenses, you can make informed decisions, strengthen your eligibility for financing, and build long-term financial stability.
Disclaimer: This article is for general informational purposes only and should not be considered financial, legal, or tax advice. Every business owner’s financial situation is different. Consult a qualified financial advisor or accounting professional before making financial decisions.
Share
Free Consultation
Have a tax or accounting question?
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
0 Comments
No comments yet. Be the first to start the conversation.
Non-profit organizations play a vital role in supporting communities, advancing education, promoting healthcare, protecting the environment, and delivering humanitarian aid across the…
Businesses have traditionally relied on financial reports such as revenue, profit, cash flow, and expenses to evaluate performance. While these metrics remain…
Auditing different types of businesses is essential because every industry operates with unique financial processes, regulations, and risks. A manufacturing company manages…



0 Comments