DNFBP Transaction Monitoring UAE: Accounting Red Flags and Review Procedures
M Maria August 22, 2026 16 min read
Could a transaction look completely normal in your accounting system and still be an AML red flag?
A transaction may appear normal in accounting records but still require closer review. Large payments, transfers involving several parties, or sudden changes in transaction patterns can be potential red flags, although they do not automatically indicate money laundering or financial crime.
Businesses should assess whether such activity is reasonable and consistent with the customer’s known profile. This makes DNFBP transaction monitoring UAE important for sectors exposed to money laundering risks. UAE DNFBPs are subject to the AML/CFT framework, with sector-specific guidance covering red flags and suspicious transaction reporting.
What is a DNFBP?
DNFBP stands for Designated Non-Financial Businesses and Professions. In the UAE, DNFBPs include certain non-financial businesses and professional activities that can be exposed to money laundering and other financial crime risks. Examples include:
Auditors and accountants
Real estate agents and brokers
Dealers in precious metals and stonesTrust and company service providers
The Ministry of Economy and Tourism provides specific AML resources for these sectors, including red-flag guidance for accountants and auditors, real estate businesses, precious-metal dealers, and corporate service providers. The reason these businesses receive particular attention is that their services, transactions, or assets may potentially be misused to move, conceal, or integrate illicit funds.
The UAE’s current AML framework includes Federal Decree-Law No. 10 of 2025 and its Executive Regulations under Cabinet Resolution No. 134 of 2025, which became effective on 14 December 2025.
What Is Transaction Monitoring?
Transaction monitoring means reviewing customer activity to identify transactions or patterns that appear unusual, inconsistent, or potentially suspicious based on what the business knows about the customer. In simple terms, it asks:
“Does this transaction make sense for this customer and their business?”
A business may consider factors such as:
Transaction amount
Frequency of transactions
Payment method
Customer’s business activity
Expected transaction behavior
Countries involved
Source and purpose of funds
Beneficial ownership
Previous transaction history
Transaction Monitoring vs Transaction Screening
These two AML terms are sometimes confused. Transaction monitoring looks at transaction activity and patterns to identify unusual behavior. Transaction screening is different. It involves checking relevant parties or transactions against applicable sanctions and other screening lists. A strong AML framework may require both, depending on the business’s activities and risk exposure.
Why is DNFBP Transaction Monitoring UAE important?
Effective DNFBP AML compliance UAE processes help businesses identify unusual activity and respond appropriately before risks become harder to investigate.
Transaction monitoring can help a DNFBP:
Identify unusual transactions
Compare actual activity with expected activity
Detect changes in customer behavior
Identify potential financial crime risks
Support customer risk assessments
Maintain appropriate records
Escalate concerns when necessary
Meet applicable AML obligations
The UAE Ministry of Economy and Tourism states that DNFBPs must promptly report suspicious transactions or attempted transactions when there are suspicions or reasonable grounds to suspect that funds or proceeds are related to a crime or intended for criminal purposes. It also says DNFBPs should maintain indicators for identifying possible suspicious transactions and have internal procedures for identification and reporting.
Importantly, transaction monitoring is not about assuming that every unusual transaction is illegal. The purpose is to identify activity that requires appropriate review.
How Does Transaction Monitoring Work?
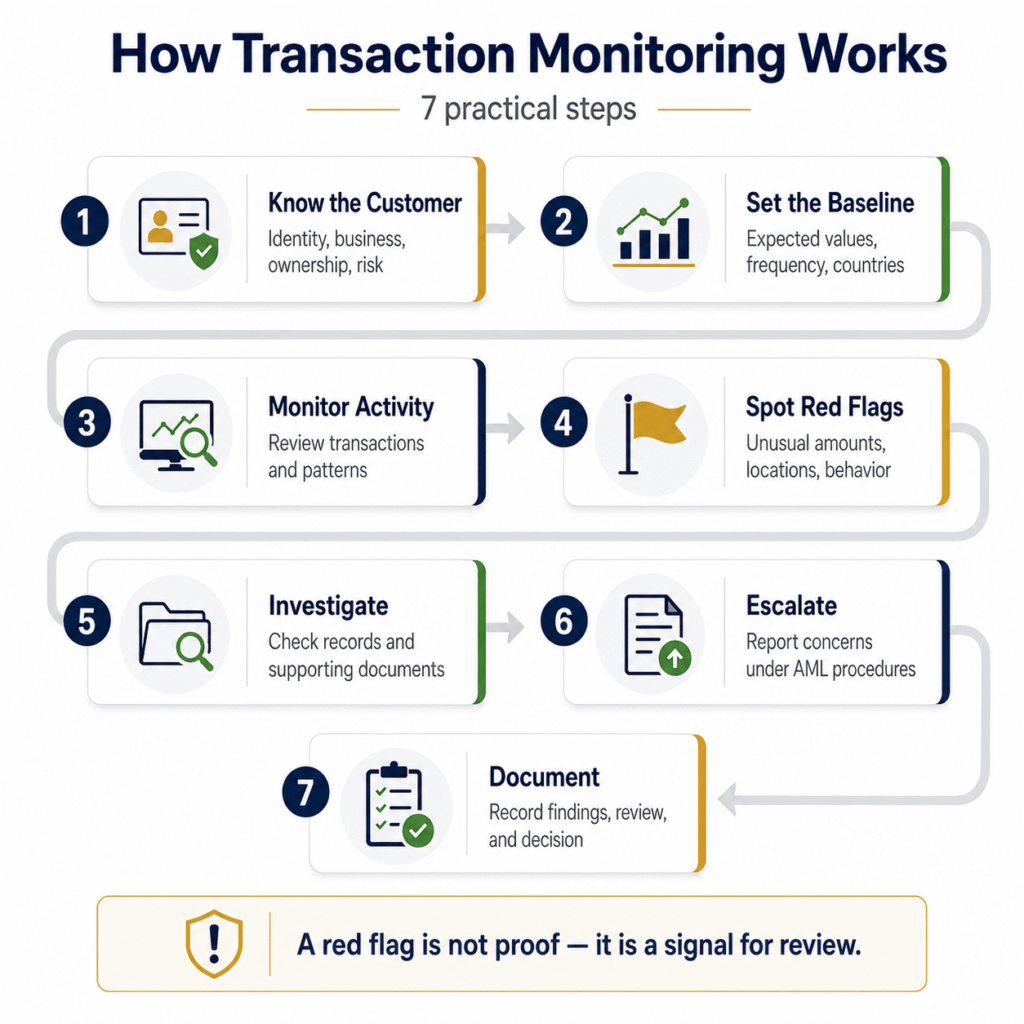
A practical transaction monitoring process usually follows several stages.
Transaction Monitoring
Step 1: Understand the Customer
Before deciding whether something is unusual, the business needs to understand who the customer is. This may include reviewing:
Customer identity
Business activity
Ownership structure
Beneficial owners
Expected transaction activity
Geographic exposure
Source of funds or wealth, where relevant
Customer risk classification
Without this information, it is difficult to determine whether a transaction is genuinely unusual. For example, a large international payment may be completely normal for an import-export company but unusual for a small local business whose activities have historically been domestic.
Step 2: Establish Expected Activity
The business should have a reasonable understanding of how the customer is expected to operate. Consider:
Typical transaction values
Expected payment frequency
Normal counterparties
Usual countries involved
Normal payment methods
Nature of the customer’s business
This creates a baseline against which future activity can be reviewed.
Step 3: Monitor Transactions
Transactions can then be reviewed for unusual amounts, patterns, counterparties, locations, or payment behavior. Monitoring may be manual or supported by technology.
Step 4: Identify Red Flags
An unusual transaction or pattern may trigger a review. However, a red flag is not proof of money laundering. It is an indicator that should be considered alongside the customer’s circumstances and other available information.
Step 5: Investigate
The business should review relevant information and supporting documents to understand the transaction.
Step 6: Escalate When Appropriate
If concerns remain after review, the matter may need to be escalated according to the organization’s AML procedures.
Step 7: Document the Decision
The business should record what was identified, what was reviewed, what explanation was obtained, and why a particular decision was reached.
Accounting Red Flags in DNFBP Transaction Monitoring
Accounting records can provide valuable information during AML reviews. They may show patterns that are not obvious from a single transaction. The following transaction monitoring red flags should not automatically be treated as evidence of criminal activity. Instead, there are situations that may require additional questions or investigation.
Unusually Large or Unexpected Transactions
A transaction that is significantly larger than the customer’s normal activity may deserve attention. For example, a business that normally processes payments of AED 20,000 suddenly records a transaction of AED 1 million. The amount alone does not make the transaction suspicious. The reviewer should ask:
What is the purpose?
Is the transaction consistent with the customer’s business?
Who is the other party?
Is there an invoice or contract?
Where did the funds come from?
Transactions Inconsistent With the Customer’s Business
One of the important AML red flags UAE businesses should understand is inconsistency between the customer’s known business and actual transaction activity. For example, a company described as a small local consulting business suddenly starts receiving substantial payments connected with unrelated international trading activity.
The reviewer should determine whether the customer’s business has changed, whether the activity is legitimate, and whether customer information needs updating.
Unexplained Cash Transactions
Cash is not automatically suspicious. However, unusual cash activity can require closer review when it does not fit the customer’s normal business. Examples include:
Large cash deposits
Frequent cash transactions
Sudden increases in cash activity
Cash activity is inconsistent with the customer’s business model
The important question is whether the transaction has a reasonable and supported explanation.
Third-Party Payments
A third-party payment occurs when someone other than the expected customer or counterparty makes a payment. For example, a customer owes a supplier AED 100,000, but the payment comes from an unrelated company. This does not automatically indicate wrongdoing. However, the relationship between the parties and the reason for the payment should be understood.
Rapid Movement of Funds
Another potential red flag is when funds enter and leave an account or transaction chain unusually quickly. Reviewers may examine:
Where the money came from
Where it went
Why it moved
Whether multiple parties were involved
Whether there is a legitimate commercial explanation
Looking at the full transaction pattern is often more useful than looking at one payment in isolation.
Complex or Unnecessarily Complicated Transactions
A transaction involving multiple companies, intermediaries, jurisdictions, or ownership layers may require additional review when the structure has no clear commercial purpose. The key question is not simply:
“Is this transaction complicated?”
It is:
“Why does it need to be structured this way?”
A legitimate international transaction may naturally involve several parties. What matters is whether the structure can be reasonably explained and supported.
Frequent Changes in Ownership or Control
Changes in ownership are not inherently suspicious. However, unexplained or unusually frequent changes may require review, particularly when the business has difficulty identifying the ultimate beneficial owner.
Review:
New shareholders
Ownership transfers
Changes in directors or controllers
Corporate restructuring
Beneficial ownership information
High-Risk Geographic Exposure
Transactions involving jurisdictions identified as high-risk or subject to increased monitoring may require appropriate risk-based measures.
The UAE Ministry of Economy and Tourism publishes updates concerning high-risk countries and jurisdictions and related measures for DNFBPs.
This does not mean every transaction involving a particular country is suspicious. Geographic exposure is one factor that should be considered together with the customer’s profile and transaction circumstances.
Missing or Inconsistent Documentation
Documentation problems can also create concerns.
Examples include:
The invoice does not match the payment amount
The contract does not explain the transaction
Missing supporting documents
Customer information conflicts with transaction details
Documents appear unreliable or inconsistent
A missing document does not automatically mean a transaction is suspicious. The business should determine whether the issue can be reasonably resolved.
Unusual Invoices and Accounting Entries
Accounting teams may notice patterns such as:
Repeated round-number invoices
Unexplained journal entries
Unusual adjustments
Backdated entries
Frequent reversals
Payments that do not match invoices
Transactions posted to unexpected accounts
Again, the pattern and context matter more than a single accounting entry.
Common AML Red Flags for DNFBPs
Red flag
What to review
Unusually large transaction
Customer profile and transaction purpose
Unexpected cash activity
Source and business rationale
Third-party payment
Relationship between parties
Complex transaction
Commercial or economic purpose
Geographic exposure
Applicable country and customer risk
Rapid movement of funds
Full transaction chain
Ownership changes
Beneficial ownership
Missing documents
Supporting evidence
Unusual invoices
Invoice and payment consistency
Activity inconsistent with profile
Expected vs. actual activity
The presence of a red flag does not establish that a customer has committed a crime. The appropriate response is to review, investigate, and document the circumstances.
Transaction Review Procedures for DNFBPs
A clear AML review procedure helps staff respond consistently rather than making decisions based on assumptions.
1. Identify the Transaction
Record the basic details:
Date
Amount
Currency
Parties
Payment method
Transaction description
2. Compare It With the Customer Profile
Ask:
Is this normal for the customer?
Does it match their business?
Is the amount reasonable?
Is the frequency unusual?
Are the parties expected?
3. Review Supporting Documents
Depending on the transaction, documents may include:
Invoice
Contract
Purchase order
Payment evidence
Ownership documents
Other relevant records
The purpose is to understand the commercial reason for the transaction.
4. Understand the Source and Purpose of Funds
Where appropriate based on the customer’s risk and applicable requirements, the business should seek to understand where the funds came from and why the transaction is being made.
5. Check Related Transactions
Do not always review an alert by itself.
Look for:
Earlier transactions
Similar payments
Related parties
Repeated patterns
Connected entities
Changes in transaction behavior
A single unusual payment may be easily explained. A repeated pattern may require more attention.
6. Assess the Risk
Consider the combined circumstances:
Customer risk
Transaction risk
Geographic risk
Service or product risk
Payment method
Transaction pattern
7. Decide the Appropriate Action
Depending on the outcome, the business may:
Close the review with no further action
Request additional information
Conduct enhanced review
Escalate the matter internally
Investigate further
Consider suspicious transaction/activity reporting where required
The appropriate decision should follow the DNFBP’s AML policies and applicable UAE requirements.
8. Document Everything
A reviewer should be able to understand:
What happened → What was investigated? → What evidence was reviewed → What decision was reached → Why
Good documentation is therefore an important part of the DNFBP AML requirements UAE.
Manual vs Automated Transaction Monitoring
Not every DNFBP needs the same technology.
Manual Monitoring
Smaller businesses may use:
Accounting reports
Spreadsheets
Exception reports
Periodic reviews
Customer transaction summaries
The process still needs to be structured and documented.
Automated Monitoring
Larger or more complex businesses may use systems that identify:
Transaction thresholds
Unusual patterns
Frequent transactions
Geographic exposure
Customer-risk-based alerts
Other defined indicators
Technology can improve efficiency, but automation does not replace human judgment. The UAE’s DNFBP guidance recognizes that monitoring can be manual or automated and should be appropriate to the business’s size, nature, complexity, and risk.
How to Investigate a Transaction Monitoring Alert
When an alert is generated, avoid jumping directly to a conclusion. Ask these questions:
What happened?
Who was involved?
How much was involved?
Why did the transaction occur?
Does it fit the customer’s business?
What is known about the source and purpose of funds?
Where did the funds go?
What documents support the transaction?
Is there a wider pattern?
Does anything remain unexplained?
The final assessment should consider all available information rather than relying on one red flag.
What Should Be Included in a Transaction Review Record?
A useful transaction review record may include:
Customer details
Transaction details
Red flag identified
Customer risk information
Documents reviewed
Questions raised
Explanation received
Investigation performed
Reviewer’s name
Review date
Final decision
Escalation details, where applicable
This documentation helps demonstrate that the business did not simply ignore an alert.
When Should a Transaction Be Escalated?
Not every unusual transaction requires external reporting. A useful way to understand the process is
Unusual → Reviewed → Explained → Close the review
or:
Unusual → Reviewed → Concerns remain → Escalate according to AML procedures
Escalation may be appropriate when:
The explanation is inconsistent
Supporting evidence is inadequate
The activity remains unexplained
Several red flags appear together
Activity conflicts significantly with the customer’s profile
There are concerns regarding the source or purpose of funds
Internal AML procedures require escalation
The UAE’s current DNFBP guidance states that DNFBPs must promptly report suspicious transactions or attempted transactions when the applicable suspicion or reasonable grounds to suspect threshold is met.
Suspicious Transaction Reporting in the UAE
Suspicious transaction or activity reporting is an important part of the UAE AML framework.
The UAE’s Financial Intelligence Unit (FIU) receives and analyzes suspicious transaction and activity reports. DNFBPs use the goAML system for relevant reporting. The Ministry of Economy and Tourism states that DNFBPs are required to register on goAML and use the system to submit STRs/SARs as applicable.
A report should not be treated as a declaration that the customer is guilty of a crime. Reporting is part of the AML framework for communicating concerns to the competent authority.
DNFBPs should also be careful about tipping off. In simple terms, this means improperly alerting a customer that a suspicious transaction/activity report or related investigation is being made.
Because reporting requirements and procedures can have serious legal consequences, businesses should follow their approved AML framework and obtain appropriate professional advice where necessary.
Common Transaction Monitoring Mistakes DNFBPs Should Avoid
1. Treating Every Alert as Suspicious: An alert is a reason to investigate, not proof of criminal activity.
2. Looking Only at Transaction Value: A smaller transaction can also be unusual when considered as part of a wider pattern.
3. Ignoring Customer Context: A transaction should be assessed against the customer’s business and expected activity.
4. Reviewing Transactions in Isolation: Related transactions can reveal a pattern that one payment does not show.
5. Accepting Weak Explanations: An explanation should be supported by appropriate evidence where necessary.
6. Failing to Update Customer Information: Changes in business activity, ownership, or risk can affect how transactions should be assessed.
7. Poor Documentation: If a review is not documented, it can be difficult to demonstrate what happened and why a decision was reached.
8. Relying Completely on Software: Automated tools can identify patterns, but human review remains important.
9. Failing to Escalate Concerns: Unresolved concerns should follow the organization’s escalation process.
10. Treating AML as a One-Time Exercise: Ongoing monitoring is important because customers, businesses, and transaction patterns can change.
How Accounting Teams Can Support AML Transaction Monitoring
Accounting teams can play an important supporting role in AML compliance because they often work directly with financial records.
They may identify:
Unusual payments
Inconsistent invoices
Unexpected accounting entries
Unexplained adjustments
Third-party payments
Unusual customer balances
Missing supporting documents
Sudden changes in transaction patterns
However, accounting staff should not be expected to independently decide that a customer is committing a crime. Their role is generally to identify relevant concerns, preserve supporting information, and escalate according to the organization’s AML procedures. This makes communication between accounting, compliance, and management particularly important.
How Ripple Can Help UAE Businesses
Running a business in the UAE requires more than managing day-to-day operations. Companies also need to maintain accurate financial records, meet regulatory requirements, manage tax obligations, and build internal processes that support long-term growth.
Ripple Accountants supports UAE businesses with practical accounting, tax, compliance, and advisory services tailored to their operational needs. From bookkeeping and financial reporting to VAT, Corporate Tax, AML compliance support, and management advisory, Ripple helps businesses improve financial visibility and stay better prepared for regulatory requirements.
Contact us today to discuss your payment, reconciliation, and financial control requirements.
Email: info@uaetaxcompliance.ae
Phone: +971 52 356 5409
WhatsApp: +971 4 250 0833
Frequently Asked Questions
1. What is DNFBP transaction monitoring?
DNFBP transaction monitoring is the process of reviewing customer transactions and patterns to identify activity that may be unusual or inconsistent with the customer’s known profile and requires further assessment.
2. What businesses are considered DNFBPs in the UAE?
Relevant sectors include certain accounting and auditing businesses, real estate agents and brokers, dealers in precious metals and stones, and trust and company service providers. The exact scope depends on the applicable UAE legislation and the activities performed.
3. What are accounting red flags for money laundering?
Examples can include unexplained transactions, unusual accounting entries, inconsistent invoices, unexplained third-party payments, unusual cash activity, and transactions that do not fit the customer’s known business profile.
4. Is an unusual transaction automatically suspicious?
No. An unusual transaction is an indicator that may require review. Its context, customer profile, supporting evidence, and overall pattern should be considered.
5. How often should DNFBPs monitor transactions?
Monitoring should be appropriate to the customer’s and business’s risk profile and applicable AML requirements. Higher-risk relationships may require more frequent or enhanced monitoring.
6. Can accounting software be used for transaction monitoring?
Yes. Accounting and other technology systems can support monitoring, but businesses should ensure that their overall AML controls are appropriate to their risk and that alerts receive appropriate human review.
Conclusion
Effective DNFBP transaction monitoring UAE businesses can rely on is not about searching for one “suspicious” transaction and immediately assuming the worst. It is about understanding the customer, knowing what normal activity looks like, identifying meaningful changes, and reviewing transactions in context.
Accounting records can provide some of the earliest warning signs. Unusual payments, unexplained cash activity, third-party transactions, inconsistent invoices, complex structures, and unexpected changes in customer behavior may all deserve closer attention.
Disclaimer: This article is intended for general educational and informational purposes only. It does not constitute legal, tax, accounting, audit, or regulatory advice. UAE requirements can vary depending on the business structure, activity, location, tax status, and applicable regulatory framework. Businesses should obtain professional advice based on their specific circumstances.
Share
Free Consultation
Have a tax or accounting question?
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
0 Comments
No comments yet. Be the first to start the conversation.
Non-profit organizations play a vital role in supporting communities, advancing education, promoting healthcare, protecting the environment, and delivering humanitarian aid across the…
Businesses have traditionally relied on financial reports such as revenue, profit, cash flow, and expenses to evaluate performance. While these metrics remain…
Auditing different types of businesses is essential because every industry operates with unique financial processes, regulations, and risks. A manufacturing company manages…



0 Comments