Blocked Input Tax in UAE: Motor Vehicles & Personal Use
Z Zobia August 10, 2026 15 min read
Businesses registered for VAT in the UAE can recover input tax on many business expenses, but not every VAT payment is recoverable. The UAE VAT system blocks input tax recovery on specific expenses that are considered personal or non-business in nature. Motor vehicles used for personal purposes and certain entertainment expenses are among the most common areas where businesses make costly VAT mistakes. Understanding the rules on blocked input tax UAE is essential for maintaining compliance with the UAE VAT legislation and avoiding errors during Federal Tax Authority (FTA) audits. Incorrect VAT claims can result in assessments, administrative penalties, and additional tax liabilities.
What Is Blocked Input Tax in UAE VAT?
Blocked input tax refers to VAT paid on specific goods or services that cannot be recovered by a VAT-registered business, even if the business has a valid tax invoice. These restrictions are set out in the UAE VAT legislation to prevent businesses from claiming VAT on expenses that mainly provide a personal benefit or are not directly connected with making taxable business supplies.
Input tax recovery is only available when all legal conditions are met. If an expense falls under the blocked input tax rules, the VAT becomes a cost to the business rather than a recoverable amount.
Understanding the difference between recoverable and blocked input tax helps businesses prepare accurate VAT returns and reduce compliance risks.
Recoverable Input Tax vs Blocked Input Tax
Recoverable Input Tax
Blocked Input Tax
Related to taxable business activities
Related to personal or restricted use
Meets UAE VAT recovery conditions
Specifically restricted under UAE VAT rules
Supported by valid tax documentation
Cannot be claimed even with a valid invoice if blocked by law
Included in VAT recovery calculations
Treated as a business expense instead of recoverable VAT
Why Does the UAE Block Certain Input Tax?
The blocked input tax rules protect the integrity of the UAE VAT system by ensuring that businesses recover VAT only on genuine business expenses.
These rules help to:
Prevent recovery of VAT on personal consumption.
Reduce incorrect VAT claims.
Create consistent VAT treatment across industries.
Improve transparency during FTA audits.
Support fair tax compliance for all businesses.
For finance teams and business owners, understanding these restrictions is just as important as knowing when VAT recovery is allowed.
When Can Businesses Recover Input Tax in the UAE?
A VAT-registered business can recover input tax only when the purchase supports taxable business activities and all legal recovery conditions are satisfied. Recovering VAT without meeting these requirements may result in adjustments during an FTA review.
General Conditions for VAT Recovery
Businesses should ensure the following conditions are met before claiming input tax:
The business is registered for VAT in the UAE.
The goods or services are purchased for business purposes.
The purchase relates to making taxable supplies.
A valid tax invoice is available.
VAT has been correctly charged by the supplier.
The expense is properly recorded in the accounting system.
Supporting documents are retained for the required record-keeping period.
The expense is not specifically classified as blocked input tax under UAE VAT rules.
Meeting all these conditions improves VAT compliance and reduces the likelihood of disputes with the FTA.
When Input Tax Becomes Non-Recoverable
Input tax cannot be recovered when one or more recovery conditions are not met.
Common situations include:
Goods or services are used for personal purposes.
Expenses are unrelated to taxable business activities.
Purchases fall under blocked input tax categories.
Tax invoices are missing or incomplete.
Business records are insufficient to support the claim.
VAT was charged incorrectly.
The purchase relates to exempt supplies where recovery is restricted.
Businesses should review every expense carefully before including it in their VAT return.
Motor Vehicles and Blocked Input Tax in UAE
Motor vehicles are one of the most misunderstood areas of UAE VAT compliance. Many businesses assume VAT paid on every company vehicle is recoverable. However, UAE VAT legislation limits recovery where passenger vehicles are available for personal use.
The purpose for which the vehicle is acquired and how it is actually used determine whether VAT recovery is allowed.
What Qualifies as a Motor Vehicle?
For VAT purposes, a motor vehicle generally includes passenger vehicles designed to transport people on public roads.
Examples include:
Passenger cars
Sedans
SUVs
Crossovers
Hatchbacks
Station wagons
Luxury vehicles
Double-cab vehicles primarily used for passengers
Commercial vehicles designed mainly for transporting goods or providing specific services may be treated differently under the VAT rules.
Businesses should evaluate each vehicle based on its design, intended use, and actual business purpose rather than assuming all vehicles receive the same VAT treatment.
Why VAT on Some Motor Vehicles Is Blocked
The UAE blocks VAT recovery on certain motor vehicles because they are commonly available for private or personal use.
VAT recovery is generally restricted where a passenger vehicle is available for:
Personal travel.
Home-to-office commuting.
Family use.
Weekend driving.
Social or recreational activities.
Mixed business and personal use without meeting the relevant recovery conditions.
The restriction applies even when the vehicle is owned or leased by the business. The deciding factor is whether the vehicle provides a personal benefit rather than being used exclusively for qualifying business activities.
For example, if a company purchases a luxury sedan for a managing director who also uses it for family trips and commuting, the VAT on that vehicle is generally treated as blocked input tax.
By contrast, a delivery company using vehicles solely to transport customer goods as part of its business operations may qualify for VAT recovery, provided all legal conditions are satisfied.
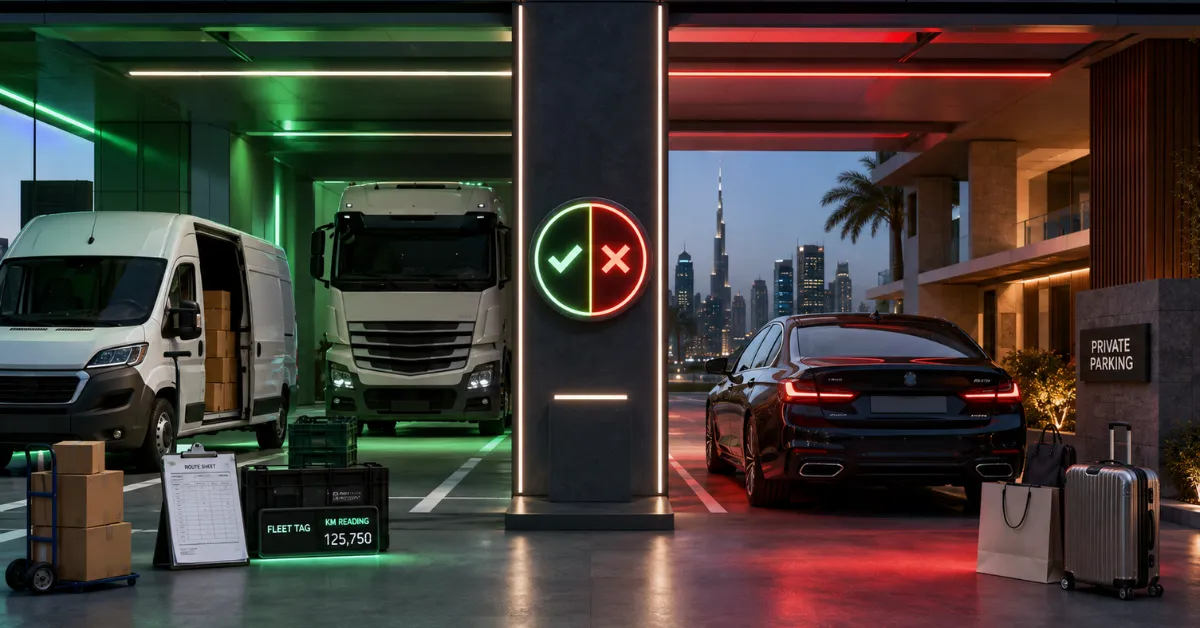
Motor Vehicles Eligible for VAT Recovery
Although VAT recovery is restricted for many passenger vehicles, certain vehicles used exclusively for qualifying business activities may still be eligible for input tax recovery. Businesses should assess each vehicle based on its actual use and maintain supporting documentation to demonstrate that the recovery conditions have been met.
Examples of vehicles that may qualify include:
Commercial delivery vans used for transporting goods.
Heavy trucks used in logistics and construction.
Refrigerated vehicles used for food and pharmaceutical deliveries.
Taxis licensed for passenger transport.
Ride-hailing vehicles used exclusively for commercial passenger services where applicable.
Driving school vehicles used solely for driver training.
Ambulances providing healthcare services.
Police and emergency response vehicles.
Rental vehicles operated by vehicle leasing businesses.
Public transport vehicles.
Specialized service vehicles used exclusively for business operations.
Businesses claiming VAT on these vehicles should maintain:
Purchase invoices.
Vehicle registration documents.
Business usage records.
Maintenance records.
Fuel receipts.
Mileage logs where applicable.
Internal vehicle usage policies.
Keeping comprehensive documentation strengthens VAT recovery claims and helps demonstrate compliance if the FTA requests supporting evidence during a VAT audit.
Motor Vehicles Where VAT Cannot Be Recovered
The UAE VAT rules restrict input tax recovery on passenger motor vehicles that are available for personal use. Even if the vehicle is registered in the company’s name, VAT may still be blocked if employees, directors, or owners can use it for non-business purposes.
Businesses should evaluate how each vehicle is used before claiming VAT. Incorrect claims may lead to adjustments during an FTA audit.
VAT is generally not recoverable on:
Passenger cars available for private use.
Company cars provided to directors for personal travel.
Executive vehicles used for both business and personal purposes.
Employee vehicles used for commuting.
Family vehicles owned by the business.
Luxury cars used mainly for personal convenience.
Vehicles used for holidays or recreational trips.
Cars without sufficient evidence of exclusive business use.
Before recovering VAT, businesses should maintain clear records demonstrating that a vehicle is used solely for qualifying business activities.
Understanding Personal Use Under UAE VAT Rules
Personal use is one of the main reasons why input tax becomes blocked. If goods or services provide a personal benefit rather than supporting taxable business activities, VAT recovery is generally not permitted.
Understanding what constitutes personal use helps businesses avoid incorrect VAT claims and improve compliance with UAE VAT requirements.
What Counts as Personal Use?
Personal use refers to the use of business assets or services for private purposes rather than business operations.
Common examples include:
Home-to-office commuting.
Weekend travel.
Family outings.
School runs.
Shopping trips.
Holidays.
Personal appointments.
Recreational driving.
For example, if a company vehicle is regularly used by an employee to take family members on weekend trips, the related VAT generally falls under blocked input tax.
Mixed Business and Personal Use
Some businesses use the same vehicle for both business and private purposes. This mixed use increases VAT compliance risks because the vehicle is no longer used exclusively for qualifying business activities.
Businesses should carefully review:
Who is authorised to use the vehicle.
Whether personal use is permitted.
Business mileage compared with private mileage.
Internal vehicle usage policies.
Supporting documentation.
Maintaining accurate mileage logs, travel records, and company policies can help demonstrate the intended business use of vehicles during an FTA review.
Entertainment Expenses That Also Have Blocked Input Tax
Entertainment expenses are another major category where businesses commonly make VAT recovery errors. Under the UAE VAT rules, input tax on entertainment provided to non-employees is generally not recoverable because these expenses do not directly contribute to making taxable supplies.
Businesses should distinguish between genuine business operating expenses and hospitality or entertainment costs before claiming VAT.
Employee Entertainment
Some employee-related expenses may qualify for VAT recovery where they are required by law or provided as part of normal business operations. However, recreational or social entertainment may be subject to VAT restrictions depending on the circumstances.
Examples include:
Team celebrations.
Recreational events.
Staff parties.
Hotel accommodation for leisure events.
Entertainment outings.
Sports activities.
Holiday celebrations.
Businesses should review each expense individually to determine whether VAT recovery conditions are met.
Client Entertainment
VAT is generally blocked on entertainment provided to customers, suppliers, business partners, or other non-employees.
Common examples include:
Restaurant meals.
Sporting event tickets.
Concert tickets.
Luxury hospitality.
Entertainment events.
Holiday gifts.
Client parties.
Recreational activities.
These expenses are usually considered to provide hospitality rather than directly supporting taxable business supplies.
Common Business Expenses with Blocked Input Tax
Businesses should understand which expenses commonly fall within the blocked input tax rules before preparing VAT returns.
Examples include:
Entertainment provided to clients.
Personal travel expenses.
Private accommodation.
Family-related expenses.
Personal fuel consumption.
Personal meals.
Recreational expenses.
Private club memberships.
Non-business purchases.
Passenger motor vehicles used for personal purposes.
Personal gifts outside normal business activities.
Goods or services used primarily for private benefit.
Reviewing expense categories regularly helps reduce VAT errors and supports accurate tax reporting.
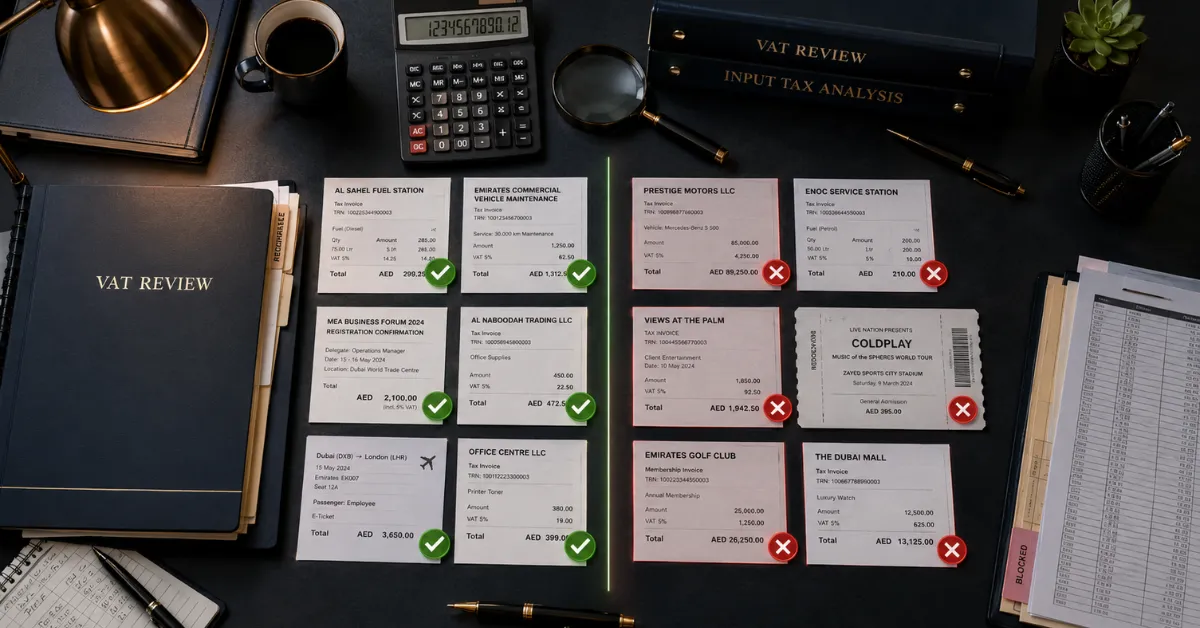
Examples of Recoverable vs Blocked Input Tax
The following examples illustrate how VAT recovery may apply to common business expenses.
Business Expense
Recoverable?
Reason
Commercial delivery van
Yes
Used exclusively for taxable business activities
Construction truck
Yes
Commercial vehicle supporting business operations
Taxi used for passenger transport
Yes
Operated as part of taxable business services
Director’s luxury passenger car
No
Available for personal use
Employee commuting vehicle
No
Used for private travel
Client dinner
No
Entertainment provided to non-employees
Concert tickets for customers
No
Hospitality expense
Hotel for employee business travel
Generally Yes
Business-related travel subject to recovery conditions
Personal fuel
No
Private consumption
Business conference registration
Generally Yes
Supports business activities if recovery conditions are met
Each expense should be assessed based on its purpose, supporting documentation, and applicable UAE VAT recovery rules.
Documentation Required to Support VAT Recovery
Strong documentation is essential for supporting VAT recovery claims. During an FTA audit, businesses should be able to demonstrate that expenses relate directly to taxable business activities.
Businesses should retain:
Valid tax invoices.
Supplier invoices and contracts.
Vehicle registration documents.
Purchase agreements.
Fuel receipts.
Maintenance invoices.
Insurance records where relevant.
Business mileage logs.
Travel records.
Expense claims.
Accounting records.
VAT return working papers.
Internal approval documents.
Vehicle usage policies.
Maintaining complete records not only supports VAT recovery but also strengthens overall tax compliance.
Common Mistakes Businesses Make
Many VAT adjustments occur because businesses misunderstand the blocked input tax rules or fail to maintain proper documentation.
The most common mistakes include:
Recovering VAT on passenger vehicles used for personal purposes.
Claiming VAT on client entertainment expenses.
Recovering VAT without a valid tax invoice.
Mixing personal and business expenses.
Failing to maintain mileage logs.
Poor documentation supporting business use.
Incorrect VAT coding in accounting software.
Assuming every company vehicle qualifies for VAT recovery.
Not reviewing expense categories before filing VAT returns.
Ignoring updates to UAE VAT guidance.
Weak internal approval procedures.
Failing to conduct periodic VAT compliance reviews.
Regular internal VAT reviews, clear company policies, and proper record keeping help businesses reduce compliance risks and prepare accurate VAT returns.
Penalties and Risks of Incorrect VAT Recovery
Incorrectly claiming blocked input tax can expose a business to VAT adjustments during an FTA review. If input tax is recovered on expenses that do not qualify under the UAE VAT rules, the business may be required to repay the tax and could face administrative penalties in accordance with the applicable tax procedures and legislation.
Common risks include:
VAT reassessments during an FTA audit.
Administrative penalties for incorrect VAT returns.
Repayment of incorrectly recovered VAT.
Additional tax liabilities.
Increased compliance costs.
Greater scrutiny in future VAT audits.
Delays in VAT assessments due to incomplete records.
To reduce these risks, businesses should review expense claims carefully before filing VAT returns and maintain complete supporting documentation.
Best Practices to Stay VAT Compliant
Following good VAT compliance practices helps businesses reduce errors and improve the accuracy of VAT returns.
Recommended best practices include:
Develop a clear VAT policy for business expenses.
Separate business and personal expenses at all times.
Restrict personal use of company vehicles where appropriate.
Maintain detailed mileage and vehicle usage records.
Keep valid tax invoices for every VAT claim.
Review entertainment expenses before claiming input tax.
Perform regular internal VAT compliance reviews.
Reconcile accounting records with VAT returns.
Train finance staff on UAE VAT recovery rules.
Maintain proper document retention procedures.
Review VAT treatment before purchasing high-value assets.
Seek professional VAT advice for complex transactions.
Consistent compliance practices help businesses avoid costly corrections and prepare for FTA reviews with confidence.
Real UAE Business Examples
Trading Company
A wholesale trading company purchases delivery vans used exclusively to transport products to customers across the UAE. Since the vehicles support taxable business activities and the company maintains complete documentation, the VAT paid on these vehicles may be recoverable, provided all recovery conditions are met.
Consultancy Firm
A consultancy purchases a luxury passenger car for its managing director. The vehicle is used for client meetings during the week and family travel on weekends. Because the vehicle is available for personal use, the VAT is generally treated as blocked input tax.
Construction Company
A construction company acquires heavy trucks used only for transporting building materials between project sites. As the vehicles are commercial in nature and used solely for business operations, input tax recovery may be permitted when the legal requirements are satisfied.
Marketing Agency
A marketing agency hosts clients at expensive restaurants and sporting events to strengthen business relationships. Although these expenses relate to business networking, VAT on client entertainment is generally not recoverable under the UAE VAT rules.
FAQ
Can I recover VAT on a company car in the UAE?
It depends on how the vehicle is used. VAT recovery is generally restricted for passenger vehicles that are available for personal use. Commercial vehicles used exclusively for qualifying business activities may be eligible for input tax recovery if all legal conditions are met.
Is VAT recoverable on fuel for company vehicles?
VAT on fuel generally follows the VAT treatment of the related vehicle. If the vehicle qualifies for input tax recovery, the associated fuel expenses may also qualify, subject to the applicable VAT recovery rules and supporting documentation.
Can VAT be claimed on luxury vehicles?
Luxury passenger vehicles that are available for personal use generally fall within the blocked input tax rules. Businesses should assess the intended use of each vehicle before claiming VAT.
What is considered personal use under UAE VAT?
Personal use includes activities that are not directly connected with business operations, such as home-to-office commuting, family travel, shopping trips, holidays, and other private journeys.
Can businesses recover VAT on client entertainment?
In most cases, VAT on entertainment provided to customers, suppliers, or other business guests is not recoverable because it falls under the blocked input tax provisions.
Are delivery vehicles treated differently from passenger cars?
Yes. Commercial delivery vehicles used exclusively for transporting goods as part of taxable business activities may qualify for VAT recovery, while many passenger vehicles available for personal use do not.
What records should businesses keep for VAT recovery?
Businesses should retain valid tax invoices, supplier contracts, purchase records, vehicle registration documents, mileage logs, fuel receipts, maintenance records, accounting records, and VAT return documentation to support recovery claims.
What happens if blocked input tax is claimed incorrectly?
If a business incorrectly claims blocked input tax, the FTA may require repayment of the VAT, make adjustments during an audit, and apply administrative penalties where appropriate.
How Ripple Accountants Can Help
Managing UAE VAT rules can be challenging, especially when dealing with blocked input tax, motor vehicles, entertainment expenses, and input tax recovery. Ripple Accountants provides expert VAT advisory, VAT registration, VAT return filing, input tax reviews, VAT health checks, FTA audit support, and ongoing compliance assistance. Our experienced tax professionals help businesses apply the correct VAT treatment, maintain proper documentation, and reduce compliance risks. Contact us today at +971 52 356 5409, +971 4 250 0833 (WhatsApp), or email info@uaetaxcompliance.ae to discuss your VAT compliance requirements.
Conclusion
Understanding the blocked input tax UAE rules is essential for every VAT-registered business. While many business expenses qualify for input tax recovery, passenger motor vehicles used for personal purposes and client entertainment expenses are common areas where VAT recovery is restricted.
Disclaimer: This article is for general informational purposes only and should not be considered tax, legal, or financial advice. UAE VAT laws, regulations, and FTA guidance may change over time. Businesses should refer to the latest applicable legislation or consult a qualified UAE VAT professional before making tax decisions.
Share
Free Consultation
Have a tax or accounting question?
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
0 Comments
No comments yet. Be the first to start the conversation.
Non-profit organizations play a vital role in supporting communities, advancing education, promoting healthcare, protecting the environment, and delivering humanitarian aid across the…
Businesses have traditionally relied on financial reports such as revenue, profit, cash flow, and expenses to evaluate performance. While these metrics remain…
Auditing different types of businesses is essential because every industry operates with unique financial processes, regulations, and risks. A manufacturing company manages…



0 Comments