VAT Registration for UAE Freelancers and Consultants: Requirements and Process
Are you working independently as a freelancer or consultant in the UAE and wondering whether you need to register for VAT? Operating…
Read article
Are you working independently as a freelancer or consultant in the UAE and wondering whether you need to register for VAT?
Operating as an individual does not automatically exempt you from UAE tax registration requirements. If your professional activities meet the relevant taxable supply thresholds, you may be required to register with the Federal Tax Authority (FTA).
Understanding VAT Registration for UAE Freelancers and Consultants is important for independent professionals providing services such as marketing, IT development, management consultancy, graphic design, accounting, engineering and business advisory. The registration requirements depend on the nature of your activities, taxable supplies, imports where relevant and expected business transactions.
This guide explains the eligibility requirements, registration thresholds, 30-day forecast, required documents and application process to help independent professionals manage their VAT responsibilities.
Yes, freelancers and consultants may need to register for VAT if they conduct an economic activity in the UAE and meet the applicable registration criteria.
UAE VAT legislation applies to natural persons conducting business activities, not only companies with separate legal identities. Therefore, an individual providing professional services independently may qualify as a taxable person.
For example, a freelance graphic designer providing services to UAE businesses, an independent IT consultant working on client projects or a marketing professional operating a consultancy practice may need to assess their VAT registration position.
The FTA’s registration provisions apply to natural and legal persons carrying out business activities, even where the individual does not hold a trade licence.
When evaluating VAT Registration for UAE Freelancers and Consultants, consider the following:
A freelancer should not assume that working independently, receiving payments into a personal bank account or operating without employees removes their VAT responsibilities.
The UAE has two main VAT registration thresholds. These determine whether an independent professional must register or can apply voluntarily.
| Registration type | Threshold | Requirement |
| Mandatory VAT registration | AED 375,000 | Taxable supplies and imports exceed the threshold |
| Voluntary VAT registration | AED 187,500 | Taxable supplies, imports or qualifying taxable expenses exceed the threshold |
These thresholds generally apply to UAE-resident individuals carrying out taxable business activities.
A freelancer or consultant must register for VAT when the value of their taxable supplies and imports:
For example, consider an independent business consultant who generates AED 390,000 in taxable consultancy fees over the previous 12 months.
If the relevant supplies fall within the UAE VAT registration calculation, the individual has crossed the mandatory registration threshold and must assess the registration deadline.
The threshold is based on relevant taxable business activity, not personal savings, total bank deposits or employment salary.
Freelancers who do not meet the mandatory registration criteria may qualify for voluntary registration.
An individual may apply when their taxable supplies and imports, or qualifying taxable expenses, exceed AED 187,500 during the previous 12 months or are expected to exceed this amount during the next 30 days.
This can be useful for professionals who have substantial business expenses but have not yet reached the mandatory sales threshold.
For example, an independent consultant may spend money on VAT-bearing software subscriptions, professional equipment, office facilities and other qualifying business expenses before generating substantial client revenue.
If the relevant expenses exceed AED 187,500 and the FTA requirements are satisfied, voluntary registration may be available.
However, registering voluntarily also creates ongoing responsibilities, including VAT return filing, tax invoicing and recordkeeping.
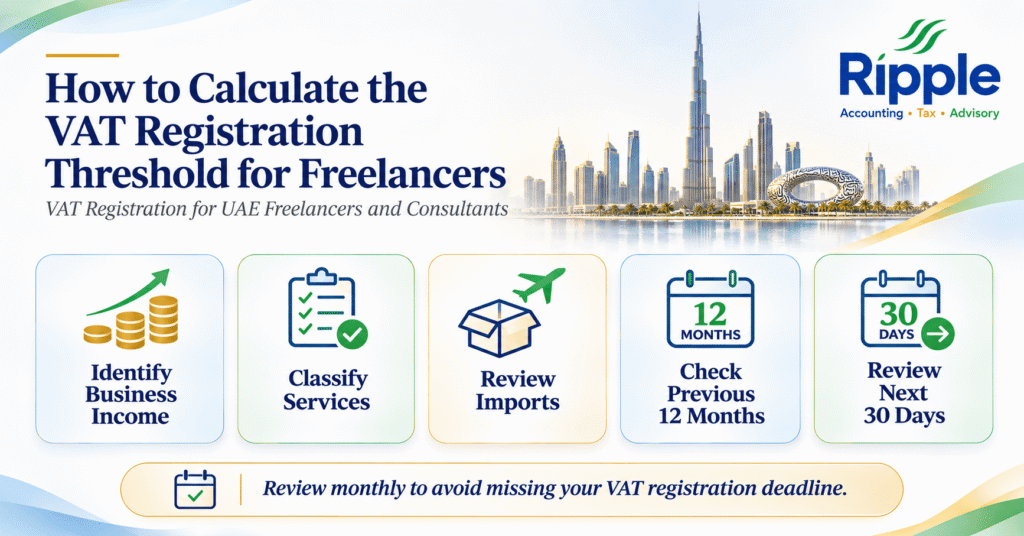
Accurate calculations are essential when assessing VAT Registration for UAE Freelancers and Consultants. Independent professionals sometimes calculate their eligibility using total money received in their bank accounts. However, not every payment received is automatically a taxable supply. The calculation should focus on relevant taxable business supplies and imports under UAE VAT legislation.
Follow these steps:
Step 1: Identify your business income
List the services you provide and the payments received from clients. Separate professional fees from unrelated personal receipts and other income that does not represent taxable business supplies.
Step 2: Classify your services
Determine whether your services are standard-rated, zero-rated, exempt or outside the scope of UAE VAT. Zero-rated supplies are still taxable supplies for registration threshold purposes, while exempt supplies are generally excluded.
Step 3: Review relevant imports
If your professional activities involve relevant imports, consider their VAT treatment and whether they must be included in the registration calculation.
Step 4: Calculate the previous 12 months
Prepare a rolling 12-month calculation using invoices, contracts, payment records and other supporting documents.
Step 5: Review the next 30 days
Examine confirmed projects, signed contracts and expected transactions to determine whether the relevant threshold is likely to be exceeded.
A monthly review can help freelancers identify their registration obligations before a deadline is missed.
The next-30-days test is particularly important for freelancers because their income may fluctuate depending on projects, contracts and client requirements.
A professional may remain below the mandatory threshold based on previous transactions but become required to register because of expected taxable supplies during the next 30 days.
For example, an independent consultant has generated AED 290,000 in taxable supplies during the previous 12 months. They then sign a consultancy agreement under which another AED 100,000 of taxable supplies is expected within the next 30 days.
The individual should assess the registration obligation based on the expected supplies rather than waiting for the payments to arrive.
A reasonable forecast should be supported by commercial evidence, such as:
Freelancers should maintain a simple monthly forecast showing their historical taxable supplies, expected transactions and remaining threshold position.
This makes VAT Registration for UAE Freelancers and Consultants easier to manage as professional activities expand.
Yes. Eligible UAE-resident freelancers and consultants may apply for voluntary VAT registration without reaching the mandatory threshold.
The AED 187,500 voluntary threshold can be assessed using qualifying taxable supplies, imports or taxable expenses.
This option may be relevant for newly established professionals who spend money on business setup, equipment, software and professional services before receiving substantial client payments.
Voluntary registration may benefit freelancers who:
However, voluntary registration should not be treated as an automatic financial advantage.
An individual should consider whether their clients can recover VAT, how registration may affect service pricing and whether the additional filing responsibilities are manageable.
The decision should be based on the professional’s actual business circumstances and the applicable FTA requirements.
Preparing the correct documents helps independent professionals support their registration applications and respond to FTA requests. The documentation may differ depending on whether the applicant operates as a natural person, holds a freelance permit or runs a sole establishment.
The following documents may be relevant:
| Document | Purpose |
| Passport copy | Identifies the individual applying for registration |
| Emirates ID copy | Supports identity verification for UAE residents |
| Freelance permit or professional licence, if available | Provides information about the authorised business activity |
| Client contracts and consultancy agreements | Demonstrates the nature and value of professional services |
| Sales invoices | Supports the calculation of taxable supplies |
| Bank statements | Helps reconcile client receipts with business records |
| Financial statements or income records | Supports the historical turnover assessment |
| Purchase invoices | Provides evidence of qualifying taxable expenses for voluntary registration |
| Accepted quotations and purchase orders | Supports expected transactions during the next 30 days |
| Power of attorney or authorisation documents | Establishes the authority of a representative, where applicable |
| Bank account information | Provides relevant banking details where requested |
Freelancers applying on the basis of taxable expenses should pay particular attention to their purchase invoices.
The FTA may require at least five tax invoices supporting the relevant expense threshold.
These documents should demonstrate qualifying expenses and meet the applicable requirements.
For example, an independent consultant purchasing professional software, office equipment and business services should retain the supplier invoices and evidence that the expenses relate to their economic activity.
A personal purchase or an expense without appropriate VAT documentation should not automatically be treated as qualifying expenditure.
For a more detailed document-by-document explanation, see Ripple’s guide to VAT Registration in the UAE: Required Documents and Checklist.
The FTA provides an online VAT registration service through its EmaraTax platform.
For VAT Registration for UAE Freelancers and Consultants, the general application process involves the following steps.
According to the FTA’s published service information, the estimated processing time is 20 business days from receipt of a completed application. Applications requiring clarification may take longer.
A freelancer or consultant who becomes required to register must generally submit the application within 30 days of becoming obligated to register.
This deadline is important because registration obligations can arise through either the previous-12-month test or the next-30-days forecast.
For example, if a consultant crosses the mandatory threshold based on historical taxable supplies, they should identify when the obligation arose and calculate the application deadline accordingly.
Waiting until the end of the financial year can result in delayed registration.
To manage the deadline, independent professionals should:
The FTA may impose a late-registration administrative penalty if an individual fails to apply within the prescribed timeframe.
Completing VAT Registration for UAE Freelancers and Consultants is only the beginning of the compliance process. Once registered, freelancers and consultants must meet the ongoing responsibilities applicable to VAT-registered persons.
Registered professionals must issue tax invoices for taxable supplies where required under UAE VAT legislation. Invoices should contain the required information, including supplier details, TRN, invoice date, description of services, taxable amount and applicable VAT.
For further guidance, see this UAE VAT Tax Invoice Checklist.
VAT-registered freelancers must submit VAT returns for their assigned tax periods through EmaraTax. Most businesses are assigned quarterly tax periods, although the FTA determines the applicable filing frequency. Returns and payments are generally due within 28 days following the end of the relevant tax period.
Keep sales invoices, purchase invoices, contracts, credit notes, payment records and VAT calculations organised. The general VAT record-retention period is five years after the end of the relevant tax period, although certain circumstances require longer retention.
Read guide on UAE VAT Record-Keeping: What Records Must Businesses Retain? for further details.
A registered freelancer may be able to recover eligible input VAT on business purchases, subject to the applicable conditions. However, VAT on personal expenditure or purchases that do not meet the recovery requirements should not be claimed automatically.
Independent professionals may overlook their registration responsibilities because they operate without a traditional company structure.
The following mistakes can create unnecessary compliance problems:
Avoiding these mistakes can help independent professionals manage VAT Registration for UAE Freelancers and Consultants more effectively.
Managing VAT responsibilities while handling client projects, service delivery and payments can become challenging for independent professionals.
Ripple Accounting, Tax & Advisory provides VAT registration and filing support to help freelancers and consultants understand their obligations and prepare the necessary financial information.
Our support can include:
Whether you are a newly established freelancer, an independent consultant approaching the mandatory threshold or a professional considering voluntary registration, the right support can help you make informed decisions.
Book a free VAT registration consultation with Ripple Accountants to discuss your eligibility, documentation and registration requirements.
Yes. Freelancers conducting taxable economic activities in the UAE must register when their taxable supplies and imports exceed AED 375,000 during the previous 12 months or are expected to exceed this amount during the next 30 days. Eligible individuals may also apply voluntarily at AED 187,500.
Yes. The FTA’s VAT registration provisions apply to natural and legal persons carrying out business activities, even if they do not hold a trade licence. Applicants must still satisfy the applicable registration requirements and provide supporting information.
Yes. UAE-resident consultants may qualify for voluntary registration when their taxable supplies, imports or qualifying taxable expenses exceed AED 187,500 during the previous 12 months or are expected to exceed this amount within the next 30 days.
No. The AED 1 million threshold relates to the Corporate Tax treatment of certain natural persons conducting business activities in the UAE. VAT has separate mandatory and voluntary registration thresholds of AED 375,000 and AED 187,500, respectively.
The FTA publishes an estimated processing time of 20 business days from receipt of a completed application. The actual time may vary if additional information or supporting documents are requested.
Freelancers and consultants conducting business in the UAE should understand that operating independently does not remove their VAT responsibilities. Registration depends on the nature and value of taxable activities, relevant imports, historical transactions and expected supplies during the next 30 days. Understanding VAT Registration for UAE Freelancers and Consultants helps independent professionals identify when registration becomes mandatory, whether voluntary registration is available and which documents they need to prepare. By monitoring taxable income, maintaining proper invoices and reviewing upcoming contracts, freelancers can manage their registration obligations and maintain accurate VAT records.
Disclaimer: This article is intended for general informational purposes and does not constitute legal, tax or professional advice. VAT treatment depends on the individual’s activities and circumstances. Consult the applicable UAE VAT legislation, current FTA guidance or a qualified tax professional before making registration decisions.
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
 VAT
Are you working independently as a freelancer or consultant in the UAE and wondering whether you need to register for VAT? Operating…
Read article VAT
Does operating from a UAE free zone mean your company is automatically exempt from VAT registration? Not necessarily. Although free zones offer…
Read article Compliance
Are your business invoicing processes ready to meet the UAE’s electronic invoicing requirements? Non-compliance with the Electronic Invoicing System can result in…
Read articlePage 1 of 67
Book a free consultation and get clear answers for your business.
0 Comments