Could one missing detail on your invoice create a UAE VAT compliance problem?
A tax invoice may look like a routine sales document, but for a VAT-registered UAE business it is an important part of the tax record. Missing TRNs, incorrect dates, wrong VAT calculations or using a simplified invoice when a full invoice is required can create problems during VAT reconciliation and review. Understanding the UAE VAT tax invoice requirements therefore matters to business owners, accountants, sellers and finance teams alike.
Now let’s get started to study VAT Tax Invoice Checklist!
What Is a Tax Invoice Under UAE VAT?
A tax invoice is a document issued by a VAT registrant for a taxable supply and containing the information prescribed under UAE VAT legislation.
Article 59 of the UAE VAT Executive Regulation sets out the particulars required on tax invoices. The FTA has clarified that only VAT registrants, who hold a Tax Registration Number or TRN, can issue tax invoices.
A VAT invoice is more than a payment request.
It helps establish:
Who made the supply
Who received the supply
What goods or services were provided
When the supply took place
How much was charged
What VAT treatment was applied
How much VAT was charged
How the transaction connects to the accounting records
These details help support VAT reporting and provide an audit trail between invoices, accounting records and VAT returns.
Who Needs to Issue a UAE VAT Tax Invoice?
A business registered for UAE VAT is generally required to issue tax invoices in respect of taxable supplies where the VAT legislation requires one.
The first step should therefore be to confirm whether the supplier is VAT registered. The supplier should also assess:
Whether the transaction is a taxable supply
The VAT treatment applicable to the supply
Whether a full or simplified tax invoice is appropriate
The date of supply
The deadline for issuing the invoice
This assessment should ideally happen within the accounting or invoicing workflow rather than after the VAT return is prepared.
UAE VAT Tax Invoice Requirements: Full Invoice Checklist
A full tax invoice has more detailed requirements than a simplified tax invoice.
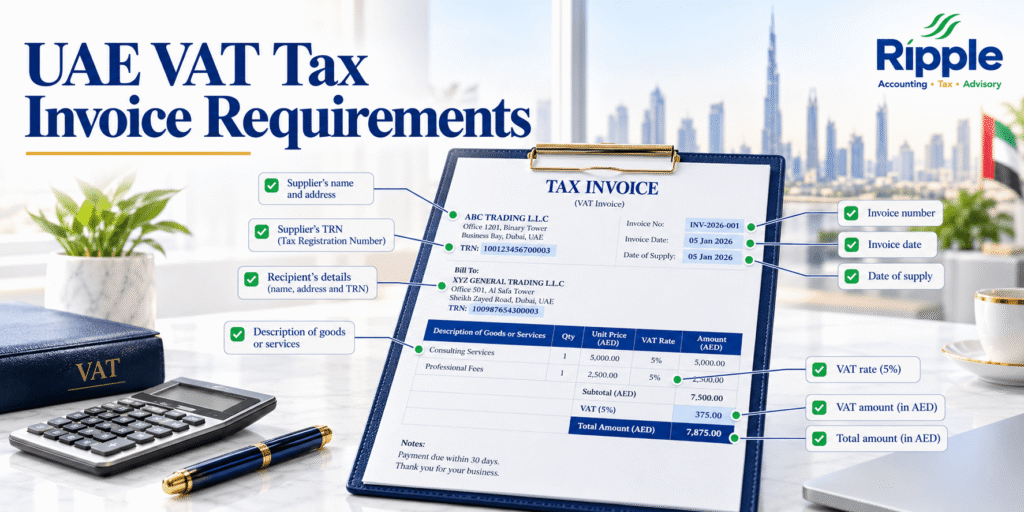
Under Article 59, businesses should review the following particulars when preparing a full tax invoice UAE transaction.
1. Clearly State “Tax Invoice”
The document should clearly display the words:
Tax Invoice
A commercial document should not be assumed to meet the VAT rules merely because it is titled “Invoice,” “Receipt,” “Bill” or “Pro Forma Invoice.”
The required tax-invoice information must be present.
2. Supplier Name, Address and TRN
The invoice should state the supplier’s:
Name
Address
Tax Registration Number
The TRN is particularly important because it identifies the supplier as a VAT registrant.
Businesses should make sure the TRN used on invoice templates matches their VAT registration records.
3. Customer Details
Where the recipient is VAT registered, the full tax invoice should include the recipient’s:
Name
Address
TRN
The VAT status of the customer should therefore be correctly maintained within the accounting or ERP system.
4. Unique or Sequential Invoice Number
A full tax invoice should contain a sequential tax invoice number or another unique number that identifies the invoice and its position within the invoice sequence.
Examples may include:
INV-2026-001
INV-2026-002
INV-2026-003
Businesses should avoid duplicate invoice numbers and unexplained gaps in their invoicing records.
5. Invoice Issue Date
The date on which the tax invoice was issued should be clearly displayed.
Do not automatically assume that the invoice date is also the date of supply.
6. Date of Supply
Where the date of supply is different from the invoice issue date, the date of supply should also be stated.
This is important because VAT timing obligations are generally linked to the date of supply rules contained in the UAE VAT legislation.
7. Description of Goods or Services
The invoice should clearly identify what was supplied.
For example, descriptions such as:
“Professional Services”
may provide less useful information than a description such as:
“VAT compliance review services – September 2026.”
The description should allow the transaction to be understood and matched to the underlying business activity.
8. Unit Price, Quantity and VAT Information
For each relevant good or service, the invoice requirements include information such as:
Unit price
Quantity or volume supplied
Applicable VAT rate
Amount payable expressed in AED
Article 59 specifically includes these elements within the full invoice particulars.
The invoice lines should reconcile mathematically with the invoice totals.
9. Discounts
Where a discount is offered, it should be correctly reflected on the invoice.
The accounting treatment and VAT calculation should correspond with the actual consideration for the supply.
10. Invoice Totals and VAT Amount
The invoice should correctly show the applicable totals and VAT amount in AED.
Businesses should check that:
Taxable values reconcile
VAT percentages are correct
VAT calculations are mathematically accurate
Final invoice totals agree with accounting records
This is especially important where an invoice includes multiple products or services with different VAT treatments.
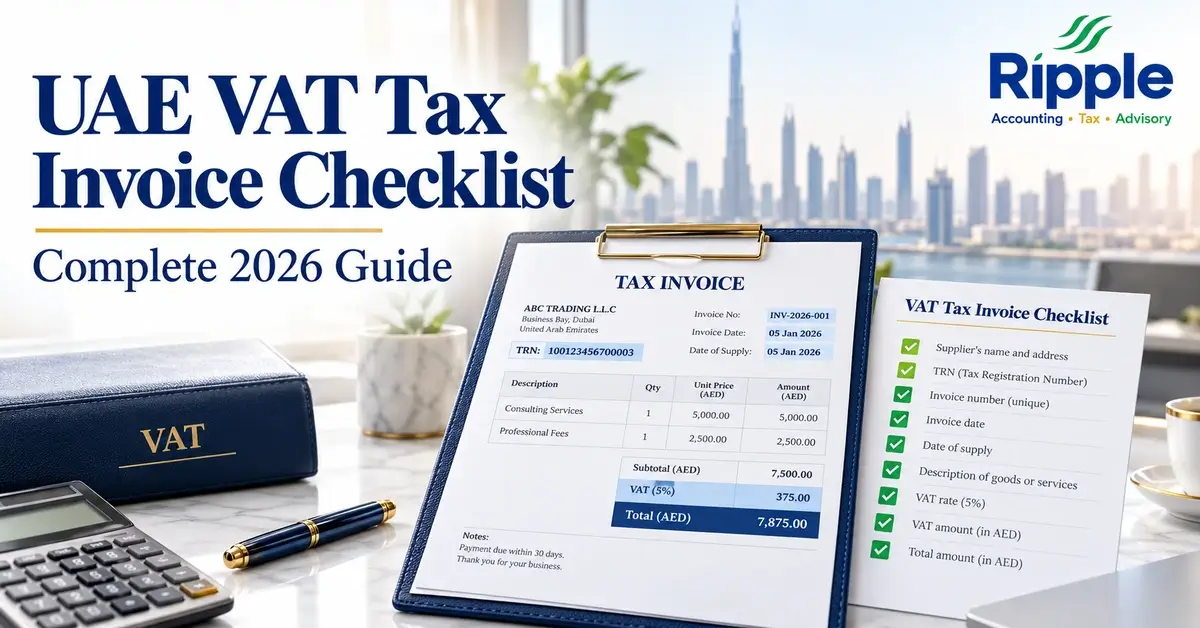
Full UAE VAT Invoice Checklist
Finance teams can use the following practical checklist before releasing a full tax invoice:
“Tax Invoice” clearly stated
Supplier legal name
Supplier address
Supplier TRN
Recipient name
Recipient address
Recipient TRN where applicable
Unique or sequential invoice number
Invoice issue date
Date of supply where different
Clear description of goods or services
Unit price
Quantity or volume
Applicable VAT rate
VAT amount
Applicable discount
Required totals in AED
Currency conversion information where applicable
Required reverse-charge wording where applicable
This UAE VAT invoice checklist can be incorporated directly into an invoice approval workflow.
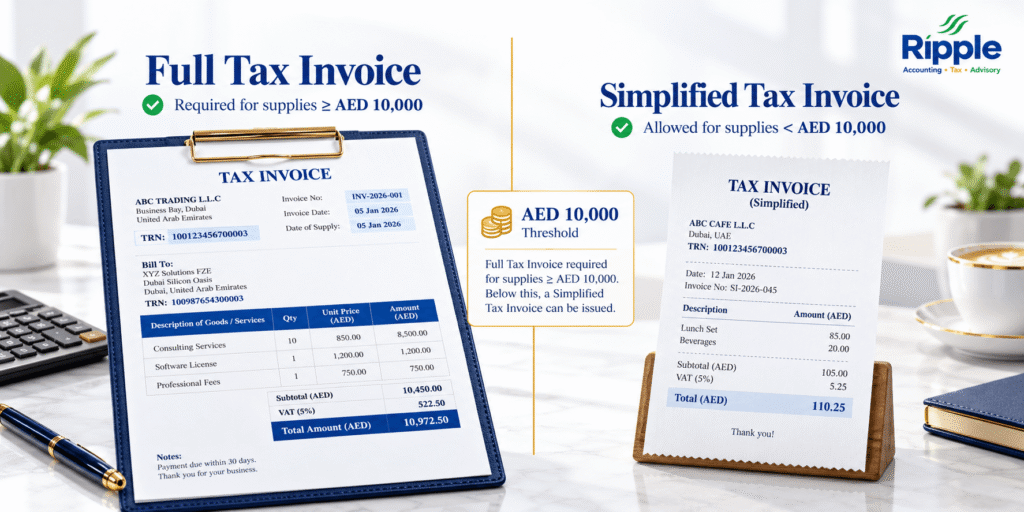
What Is a Simplified Tax Invoice in the UAE?
UAE VAT rules allow a simplified tax invoice in certain circumstances.
According to FTA guidance, a simplified tax invoice may generally be issued where:
The recipient is not registered for VAT; or
The recipient is VAT registered and the consideration for the supply is AED 10,000 or less.
This format can be particularly relevant to retail or lower-value transactions.
However, businesses should not assume that every low-value transaction automatically qualifies.
The amended Article 59 specifically provides that simplified tax invoices are not permitted where the reverse charge mechanism applies under Article 48, unless the relevant circumstances or an approved administrative exception apply.
What Must a Simplified Tax Invoice Include?
The FTA identifies a shorter list of mandatory information for a simplified invoice.
It should contain:
The words “Tax Invoice”
Supplier’s name
Supplier’s address
Supplier’s TRN
Date of issue
Description of goods or services
Total consideration
VAT amount charged
The FTA’s updated Article 59 guidance also confirms that both the total consideration and VAT amount appearing on a simplified tax invoice must be expressed in AED.
A normal cash-register receipt is therefore not automatically a compliant simplified tax invoice.
It must contain the required information.
Full Tax Invoice vs Simplified Tax Invoice
Understanding the difference helps businesses avoid using the wrong VAT invoice format.
Requirement
Full Tax Invoice
Simplified Tax Invoice
“Tax Invoice” wording
Required
Required
Supplier details
Required
Required
Supplier TRN
Required
Required
Recipient details
Required where applicable
Generally not part of the simplified particulars
Recipient TRN
Required where recipient is registered
Generally not part of the simplified particulars
Unique invoice sequence
Required
Reduced requirements
Description
Required
Required
Detailed line information
Required
Reduced requirements
Total consideration
Required
Required
VAT amount
Required
Required
Suitable for all taxable transactions
Subject to applicable rules
No
The transaction circumstances—not convenience—should determine which invoice type is used.
When Must a UAE VAT Tax Invoice Be Issued?
Timing is a particularly important part of the UAE tax invoice requirements.
Registrants are generally required to issue the relevant tax invoice within 14 days from the date of supply, as determined under the VAT Decree-Law.
However, the amended Executive Regulation introduced more specific rules for certain invoices.
Simplified Tax Invoice Deadline
A simplified tax invoice must be issued on the date of supply. This is an important distinction. Businesses operating retail or point-of-sale systems should therefore make sure simplified invoices are generated at the correct time.
Summary Tax Invoice Deadline
Where a summary tax invoice is permitted, it must generally be issued and delivered within 14 days after the end of the calendar month in which the relevant dates of supply occurred. Businesses should therefore configure their accounting processes according to the type of invoice involved.
What If an Invoice Is Issued in a Foreign Currency?
International companies and UAE businesses dealing with overseas customers may issue commercial invoices in currencies other than AED.
However, UAE VAT reporting still requires relevant amounts to be expressed in dirhams.
Where foreign currency is involved, the tax invoice requirements can include:
VAT amount expressed in AED
Required invoice totals expressed in AED
Applicable currency conversion information
The relevant exchange rate
The UAE electronic invoicing guidelines confirm that VAT and applicable total amounts must be reported in AED and refer to conversion using the applicable Central Bank exchange rate.
Finance teams should retain sufficient documentation showing how foreign-currency VAT amounts were calculated.
Where the recipient is responsible for accounting for VAT under the reverse-charge mechanism, the applicable full invoice requirements should be considered along with any required wording or legal reference.
One important 2024 Executive Regulation amendment clarified that simplified invoices cannot be used where Article 48 reverse charge applies.
Businesses dealing with imported services, cross-border transactions or other reverse-charge scenarios should therefore review the VAT treatment before determining the invoice format.
Common UAE VAT Tax Invoice Mistakes
Many invoice problems are operational rather than intentional. Common errors include:
Incorrect TRN: A mistyped or outdated TRN can affect the reliability of the invoice record.
Missing Customer TRN: Where a registered recipient’s TRN is required, leaving it blank may create a compliance issue.
Duplicate Invoice Numbers: Invoice sequencing should provide a clear audit trail. Duplicate numbers can make transaction tracing difficult.
Incorrect Date of Supply: Using the invoice creation date without determining the actual date of supply can lead to incorrect VAT-period reporting.
Wrong VAT Rate: Not every UAE transaction is automatically subject to 5% VAT. Supplies may potentially be:
Standard-rated
Zero-rated
Exempt
Outside the scope
depending on the transaction and applicable legislation.
Incorrect VAT Calculation: Common issues include:
Calculating VAT before adjusting for a relevant discount
Incorrect VAT-inclusive calculations
Rounding errors
Incorrect totals
Applying VAT to non-taxable amounts
Missing AED Information: This often occurs where commercial invoices are generated in USD, EUR, GBP or another foreign currency.
Wrong Invoice Type: Issuing a simplified invoice where a full invoice is required can create compliance problems.
Late Invoice Issuance: The accounting system should be capable of identifying the date of supply and generating invoices according to the applicable deadline.
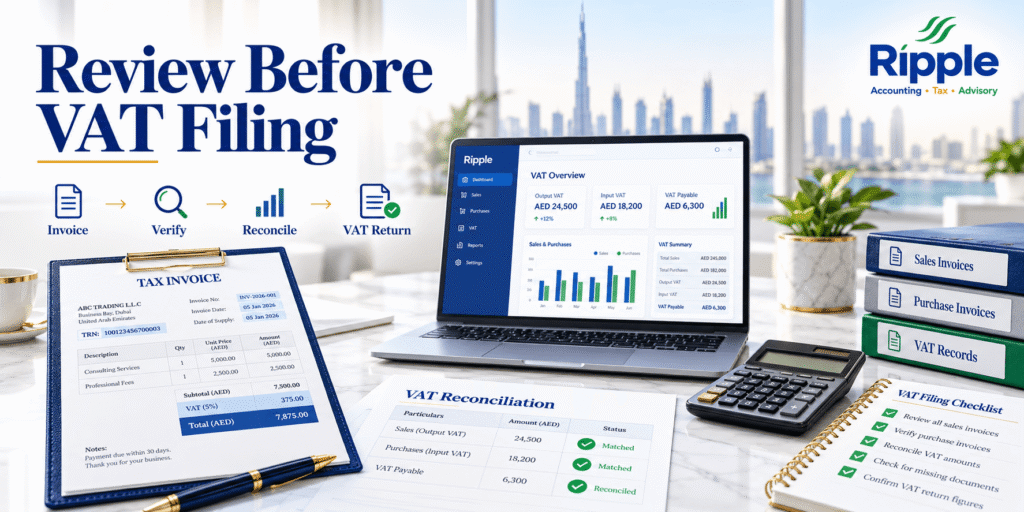
VAT Invoice Review Before Filing the VAT Return
A good VAT compliance process does not begin when the return is due. Businesses should review invoices throughout the tax period. Before preparing a VAT return, reconcile:
Sales invoices
Purchase invoices
Tax credit notes
Supplier and customer TRNs
Taxable sales
VAT amounts
Zero-rated supplies
Exempt supplies
Reverse-charge transactions
Accounting ledgers
VAT control accounts
The invoice records should ultimately support the amounts reported within the VAT return.
Regular reconciliation can identify errors while documents and supporting information are still readily available.
Tax Invoices and Input VAT Recovery
Purchase invoices are particularly important for businesses seeking to recover input VAT. A business should not rely simply on the fact that VAT appears on a supplier document. Finance teams should review whether:
The supplier is correctly identified
The document is an appropriate tax invoice
Required invoice information is present
The transaction relates to the business
The VAT treatment appears reasonable
Other input VAT recovery conditions are satisfied
Invoice validity is one element of input VAT recovery; businesses should assess the wider recovery conditions applying to the transaction.
Is a PDF Invoice the Same as a UAE eInvoice?
No.
This distinction is becoming increasingly important in 2026.
The UAE Ministry of Finance states that an eInvoice is structured invoice data that is electronically issued and exchanged between a supplier and buyer and reported electronically to the FTA.
Unstructured documents such as:
PDFs
Word documents
Images
Scanned invoices
Emails
are not, by themselves, eInvoices under the UAE Electronic Invoicing System.
A PDF can therefore still be a human-readable VAT tax invoice where applicable, but sending a PDF by email does not transform it into a structured UAE eInvoice.
UAE E-Invoicing: What Businesses Should Know in 2026
According to the Ministry of Finance’s latest September 2026 update, entities within the first mandatory phase with annual revenue of AED 50 million or more remain required to implement the Electronic Invoicing System from 1 January 2027.
The Ministry had previously extended the deadline for these businesses to appoint an Accredited Service Provider from 31 July 2026 to 30 October 2026, while keeping the January 2027 implementation date unchanged.
Businesses should therefore treat VAT invoice compliance and eInvoicing readiness as related but separate workstreams.
A correctly formatted PDF invoice alone will not satisfy future structured eInvoicing requirements where those requirements apply.
Practical UAE VAT Invoice Control Process
Finance teams can reduce errors by introducing a simple five-step process.
Step 1: Confirm the Customer
Check:
Legal name
Address
VAT status
TRN where relevant
Step 2: Determine the VAT Treatment
Identify whether the supply is:
Standard-rated
Zero-rated
Exempt
Outside the scope
Subject to reverse charge
Step 3: Select the Correct Invoice Type
Determine whether the transaction requires:
Full tax invoice
Simplified tax invoice
Summary tax invoice
Other relevant VAT documentation
Step 4: Verify the Numbers
Check:
Quantity
Unit price
Discount
Taxable value
VAT rate
VAT amount
Total
Currency conversion
Step 5: Reconcile Before VAT Filing
Match invoice data to:
Sales ledger
VAT ledger
Customer account
Bank/payment records where relevant
VAT return working papers
A systematic review is usually more reliable than trying to correct errors immediately before a filing deadline.
How Ripple Accounting, Tax & Advisory Can Help
Managing the UAE VAT tax invoice requirements becomes more difficult as transaction volumes increase, especially where a business deals with multiple VAT treatments, overseas customers, foreign currencies or different invoice systems.
Rather than checking invoices only after an error occurs, businesses can establish a repeatable compliance process that connects invoicing, bookkeeping and VAT reporting.
Need to check whether your current invoice format meets UAE VAT requirements? Speak with Ripple Accounting, Tax & Advisory for a tailored VAT compliance review.
Email: info@uaetaxcompliance.ae
Phone: +971 52 356 5409
WhatsApp: +971 4 250 0833
Frequently Asked Questions
1. What are the UAE VAT tax invoice requirements?
A full UAE tax invoice generally includes the words “Tax Invoice,” supplier details and TRN, recipient details and TRN where applicable, a unique invoice reference, issue date, date of supply where different, description of goods or services, pricing and quantity information, applicable VAT information, required totals and relevant amounts in AED. Article 59 of the VAT Executive Regulation provides the detailed requirements.
2. What is the difference between a full and simplified tax invoice in the UAE?
A full tax invoice contains detailed supplier, recipient and transaction information. A simplified tax invoice has fewer required fields and may generally be used where the recipient is not VAT registered or where a VAT-registered recipient receives a supply with consideration of AED 10,000 or less, subject to the applicable conditions.
3. When must a simplified tax invoice be issued?
Under the amended Article 59 rules, a simplified tax invoice must be issued on the date of supply.
4. How long does a business have to issue a full UAE VAT tax invoice?
Registrants are generally required to issue the relevant tax invoice within 14 days from the date of supply, subject to the applicable UAE VAT rules and specific exceptions.
5. Can I issue a simplified invoice for an AED 8,000 B2B transaction?
Potentially, if the recipient is VAT registered and the consideration does not exceed AED 10,000, provided the other applicable conditions are satisfied. A simplified invoice cannot be used merely based on the amount where the reverse-charge restriction or another requirement for a full invoice applies.
Conclusion
Meeting the UAE VAT tax invoice requirements is an important part of maintaining accurate VAT records. A full tax invoice may need detailed supplier, customer, transaction, VAT and currency information, while simplified invoices are available only where the relevant conditions are met. Businesses should pay particular attention to TRNs, invoice sequencing, dates of supply, VAT calculations, AED reporting and invoice deadlines. The amended rules also make timing important: full tax invoices are generally subject to the 14-day requirement, whereas simplified tax invoices must be issued on the date of supply. A clear internal UAE VAT invoice checklist, combined with regular VAT reconciliations, can help businesses maintain stronger records and identify issues before VAT returns are submitted.
Disclaimer: This article is provided for general informational and educational purposes only. It does not constitute tax, accounting or legal advice and should not be relied upon as a substitute for advice based on the specific facts of a transaction.
Is your construction project still profitable after you account for actual spending, outstanding purchase orders, subcontractor commitments, and the cost of completing…
Could your business explain every employee’s salary payment, deduction, overtime amount, and leave adjustment if an employee or regulator asked for proof?…
0 Comments