Corporate Tax Registration vs Filing in the UAE
Are you confused about whether registering for UAE Corporate Tax means that your company has already completed its tax filing obligation? Corporate…
Read article
Are small VAT return mistakes creating more work for your finance team than the VAT filing itself?
For VAT-registered businesses in the UAE, preparing a return requires more than entering figures into EmaraTax. Sales, purchases, input tax, output tax, credit notes, adjustments and supporting records all need to agree with the underlying accounting data. Even a small inconsistency can lead to additional checking, corrections or follow-up work. Understanding the most common UAE VAT return errors can help businesses identify problems before a return is submitted and reduce unnecessary rework.
Read on to see which VAT filing mistakes commonly require correction and how a structured pre-filing review can help.
A VAT return error occurs when information reported to the Federal Tax Authority (FTA) does not accurately reflect the business’s VAT position for the relevant tax period.
The error could relate to:
The issue is not always that the underlying transaction was recorded incorrectly. Sometimes the accounting records may be correct, but the VAT return preparation process does not transfer the information accurately.
For this reason, a VAT return review should compare the return with the accounting records and supporting documentation rather than relying only on the final figures displayed in the tax software.
A VAT return is usually prepared using information collected from several parts of a business.
Sales invoices may come from the sales team. Purchase invoices may be processed by accounts payable. Import information may come from customs or logistics records, while credit notes and adjustments may be processed separately.
If these records are not reviewed together, differences can remain unnoticed until the VAT return is being prepared or, in some cases, after submission.
For example, a business may have:
Each issue can require the finance team to return to the source records, investigate the transaction and determine the appropriate correction.
Here are the following UAE VAT return errors:
One of the first checks should be whether taxable sales recorded in the accounting system agree with the amounts reported in the VAT return.
Differences can arise because of:
A business should not assume that the accounting system’s total sales figure can simply be copied into the VAT return.
The finance team should understand what makes up the balance and whether each relevant transaction has been treated correctly for VAT purposes.
Output VAT represents VAT charged or otherwise accounted for on taxable supplies.
Errors can occur when the wrong VAT treatment is applied to a transaction or when the tax amount on invoices does not agree with the accounting records.
A useful review should compare:
Sales ledger → VAT report → tax invoices → VAT return
If these four sources do not reconcile, the difference should be investigated before filing.
Businesses may be entitled to recover input tax when the applicable conditions are met, but input tax should not simply be claimed because VAT appears on a supplier invoice.
The business should consider whether the expense is eligible for recovery and whether the required supporting documentation is available.
The FTA’s recent VAT clarification on tax invoices and input tax recovery specifically addresses supporting documentation and input tax recovery requirements.
The FTA’s input tax apportionment guidance also explains that input tax recovery depends on the use of goods or services and that special considerations can apply where costs relate to both recoverable and non-recoverable activities.
Therefore, businesses should review:
Credit notes can change the VAT position of a transaction. A common problem is that the original invoice is included in the VAT records, but the corresponding credit note is processed separately and not reflected correctly in the return.
Before filing, businesses should compare credit notes issued and received during the tax period with the relevant sales and purchase records.
The review should establish:
This can prevent differences between the sales ledger, purchase ledger and VAT return.
Not every transaction should automatically be treated in the same way. Businesses need to distinguish between relevant VAT categories based on the nature of the supply and applicable UAE VAT rules.
Errors can occur when businesses:
These errors can affect both output tax and the amount reported in the VAT return.
Where the VAT treatment is uncertain, the transaction should be reviewed before the return is submitted rather than corrected after filing.
Reverse-charge transactions can create additional VAT reporting requirements because the supplier may not charge UAE VAT in circumstances where the UAE recipient accounts for VAT under the reverse-charge mechanism.
The FTA’s VAT guidance explains that where the reverse charge applies, the recipient accounts for the VAT rather than the non-resident supplier charging UAE VAT.
This means finance teams should identify relevant transactions involving overseas suppliers and determine whether reverse-charge treatment applies.
A review can include:
The treatment should be based on the specific transaction and applicable rules rather than simply using the supplier’s invoice as the VAT treatment.
Businesses involved in importing goods may have VAT information coming from sources outside their normal purchase ledger. For this reason, import VAT should be reconciled with the relevant accounting and VAT records.
A useful review may compare:
Import records → customs information → accounting entries → VAT report → VAT return
Differences should be investigated before the VAT return is finalised.
This is particularly important for businesses with frequent imports because even small recurring differences can accumulate over several reporting periods.
Another common source of rework is assigning a transaction to the wrong tax period. For example, an invoice may be entered into the accounting system after month-end even though the relevant VAT treatment belongs to an earlier period.
The finance team should therefore review transactions around the beginning and end of each tax period. Pay particular attention to:
The FTA states that VAT returns and related payments are generally due within 28 days from the end of the relevant tax period.
A clear month-end and VAT-period closing process can reduce the risk of last-minute corrections.
A VAT return should not be reviewed in isolation. The finance team should be able to explain the relationship between the return and the underlying accounting records.
A practical reconciliation may compare:
| Record | Review against |
| Sales ledger | Output VAT report |
| Purchase ledger | Input VAT report |
| General ledger | VAT control accounts |
| Credit notes | VAT adjustments |
| Import records | Import VAT |
| VAT report | VAT return |
| VAT return | Previous period and expected movement |
Large or unusual differences should be investigated before submission.
The objective is not simply to make the numbers match. The finance team should understand why the figures match and retain appropriate supporting records.
Manual VAT adjustments can be necessary in some circumstances, but they should not become unexplained figures in the VAT working papers. Each material adjustment should have:
This becomes particularly important when a reviewer is trying to understand why the VAT return differs from the standard accounting reports.
A documented adjustment is much easier to review than a figure that appears without explanation.
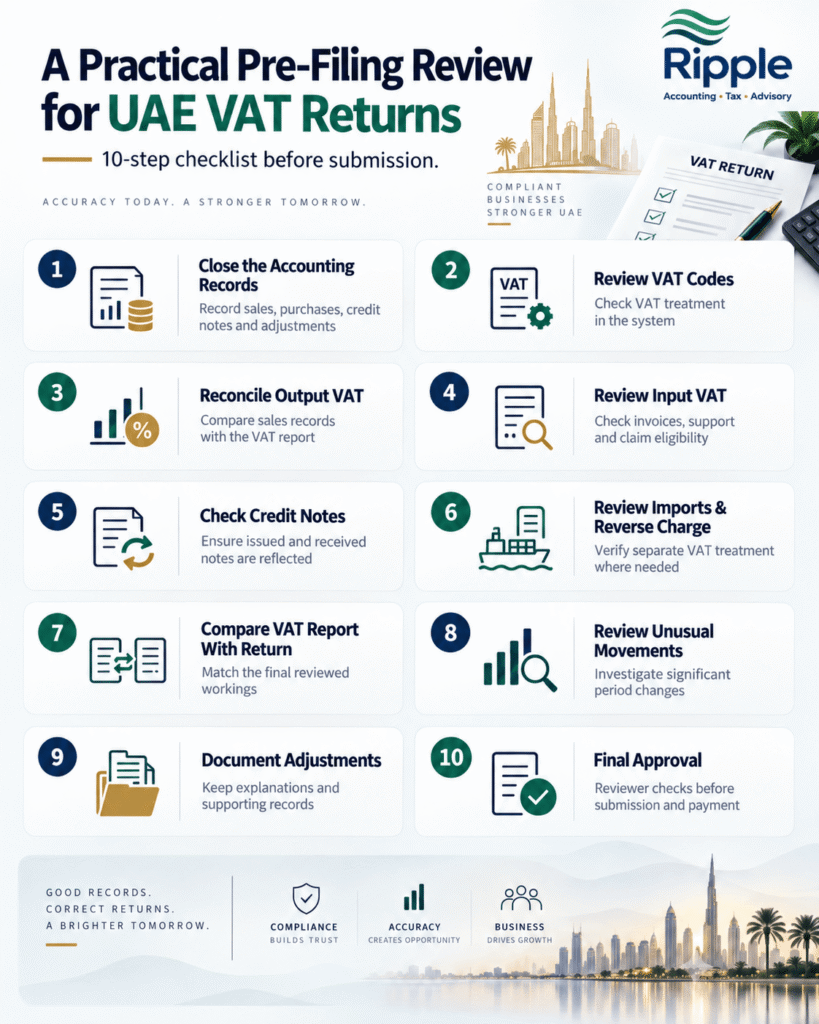
Businesses can reduce rework by introducing a standard review before every VAT return is submitted.
Ensure relevant sales, purchases, credit notes and adjustments for the tax period have been recorded.
Check whether transactions have been assigned the appropriate VAT treatment in the accounting system.
Compare sales records with the VAT report and investigate significant differences.
Check purchase invoices, supporting documentation and the eligibility of input tax claims.
Confirm that credit notes issued and received have been reflected correctly.
Identify transactions that require separate VAT consideration and verify their treatment.
Make sure the figures entered into the VAT return agree with the final reviewed VAT workings.
Compare the current period with previous periods and investigate significant changes.
Keep explanations and supporting records for manual adjustments or corrections.
Have an appropriate reviewer check the return before submission and payment.
Finding an error does not automatically mean that the same correction process applies to every situation.
The appropriate action depends on the nature and amount of the error and the applicable UAE tax procedures.
The FTA’s current FAQ states that where an error in a previously submitted VAT return resulted in payable tax being understated by no more than AED 10,000, the correction can be made in the current VAT return in which the error is discovered, subject to the applicable requirements. Where the error resulted in payable tax being understated by more than AED 10,000, the FTA states that a Voluntary Disclosure should be submitted.
The FTA’s VAT Return User Guide also sets out the correction treatment and explains that the VAT amount of an eligible correction is reported in the relevant correction field.
Businesses should therefore assess the error before deciding how to correct it rather than automatically changing the next VAT return.
Correcting an error is important, but preventing recurring errors can save considerably more time. Businesses can strengthen their VAT process by:
VAT filing becomes more manageable when the underlying accounting records are complete, reconciled and reviewed before the return is prepared.
Ripple Accountants can support UAE businesses with VAT-related accounting and filing processes, including reviewing accounting records, organizing VAT information, reconciling relevant figures, and helping businesses identify discrepancies before they create additional filing work.
So, If your business is spending too much time correcting VAT figures, reconciling records or investigating filing differences, contact Ripple Accountants to discuss your requirements.
Common errors include incorrect sales figures, input VAT claims without adequate review, missed credit notes, incorrect VAT treatment, omitted reverse-charge transactions, import VAT differences and transactions reported in the wrong tax period.
Businesses can reduce errors by reconciling sales and purchase records with VAT reports, reviewing VAT codes, checking supporting documents, investigating unusual movements and completing a documented pre-filing review before submitting the VAT return.
The correction method depends on the nature and amount of the error and the applicable FTA requirements. The FTA states that certain errors involving an understatement of payable tax of no more than AED 10,000 can be corrected through the current VAT return, while an understatement of more than AED 10,000 requires a Voluntary Disclosure.
No. The presence of VAT on an invoice does not by itself mean that the entire amount is recoverable. Businesses should consider the applicable input tax recovery requirements, the nature and use of the expense and whether the necessary supporting documentation is available.
VAT records should be reviewed for each tax period before the return is submitted. A regular review allows businesses to identify differences between accounting records and VAT workings while supporting documents and transaction details are still readily available.
UAE VAT return errors often begin with small differences between accounting records, transaction documents and VAT workings. A structured pre-filing review can help businesses identify these issues before submission. The process should connect the VAT return with the underlying sales, purchases, accounting records and supporting documents. Where an error has already been identified in a submitted return, businesses should determine the appropriate correction procedure based on the applicable FTA requirements rather than simply adjusting the next return.
Disclaimer: This article is provided for general informational purposes and does not constitute tax, legal or accounting advice. UAE VAT legislation, FTA guidance and administrative procedures may change. The appropriate treatment of a transaction or VAT return error depends on the specific facts and applicable rules. Businesses should review the latest FTA guidance and obtain professional advice where required before filing or correcting a VAT return.
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
 Corporate Tax
Are you confused about whether registering for UAE Corporate Tax means that your company has already completed its tax filing obligation? Corporate…
Read article VAT
Are you a UAE-based consultancy or agency selling services overseas while managing a remote team across different countries? Cross-border business can create…
Read article Compliance
Do you receive monthly financial reports but still struggle to answer one simple question: “What actually needs my attention right now?” For…
Read articlePage 1 of 44
Book a free consultation and get clear answers for your business.
0 Comments