Accounting for Non-Current Assets and Capital Expenditures
Non-current assets and capital expenditures play a critical role in a company’s long-term financial health. Whether you own a startup, manage an…
Read article
When does VAT registration become mandatory for a UAE business, and when is it simply an option?
For UAE businesses, the answer depends on the UAE VAT registration threshold. Registration is generally mandatory when taxable supplies and imports exceed AED 375,000, while businesses reaching AED 187,500 may be eligible for voluntary registration.
These thresholds are not based simply on total revenue or money received in the bank. Businesses need to assess their taxable supplies, imports and, for voluntary registration, qualifying taxable expenses under the UAE VAT rules. This guide explains how the thresholds work, what counts toward them, and when a business needs to register for VAT.
The UAE VAT registration threshold determines when a business becomes required to register for VAT or becomes eligible to register voluntarily.
There are two main thresholds:
The rules differ depending on whether registration is mandatory or voluntary.
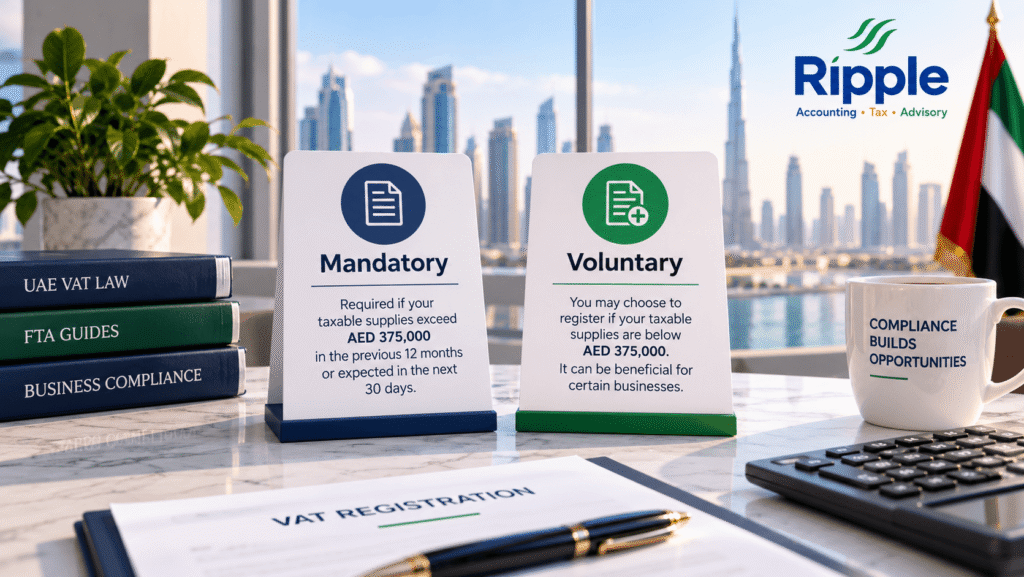
A UAE-resident business generally must register for VAT when the total value of its taxable supplies and imports exceeds AED 375,000 over the previous 12 months, or when it expects that amount to exceed AED 375,000 during the next 30 days.
This is not a threshold that businesses can choose to ignore once the applicable conditions are met.
For example, if a UAE-resident trading business reaches AED 380,000 in relevant taxable supplies and imports during the applicable period, it should assess its mandatory VAT registration obligation rather than waiting until the end of the financial year.
A UAE-resident business that does not meet the mandatory registration criteria may generally apply for VAT registration voluntarily if its taxable supplies and imports or qualifying taxable expenses exceed AED 187,500 over the previous 12 months, or are expected to exceed that amount during the next 30 days.
The important distinction is:
Mandatory registration means the business is required to register. Voluntary registration means the business is eligible to register but is not required to do so solely because it has reached the voluntary threshold.
Voluntary registration can be useful for some growing businesses, but it also creates ongoing VAT compliance responsibilities.
| Threshold | Registration type | What it means |
| AED 375,000 | Mandatory | A UAE-resident business generally must register when the applicable conditions are met |
| AED 187,500 | Voluntary | An eligible UAE-resident business may choose to register |
| Below AED 187,500 | Generally below threshold | No VAT registration based solely on the threshold, although special rules may apply |
The AED 375,000 mandatory threshold does not apply to foreign businesses in the same way. Non-resident businesses can have a VAT registration obligation regardless of the value of their UAE taxable supplies where the applicable conditions are met.
The first question is not simply, “How much did my business earn?”
Instead, determine what type of supplies the business makes, whether it is resident or non-resident for VAT purposes, and which registration test applies.
If a UAE-resident business exceeds the mandatory registration threshold based on the applicable previous-12-month or next-30-day test, it generally needs to register for VAT.
The business should identify the date on which the registration obligation arose and submit its application within the required timeframe.
If the business does not meet the mandatory registration conditions but exceeds the voluntary registration threshold, it may be eligible to register voluntarily.
At this point, registration is a business decision, not automatically a legal requirement based solely on the voluntary threshold.
The business should consider factors such as its customers, input VAT, expected growth, nature of supplies and administrative requirements.
A UAE-resident business that remains below the voluntary threshold generally does not need to register based solely on turnover.
However, businesses should not rely on this conclusion without checking their circumstances. Non-resident businesses and certain other situations can be subject to different VAT rules.
A new business may not have 12 months of historical transactions to review. The forward-looking test becomes particularly important in such situations. If a business expects its taxable supplies and imports to exceed the mandatory threshold during the next 30 days, it may become required to register even though its historical turnover is low.
For example, a new company that signs a large taxable contract should not assume that having little historical revenue means it can ignore VAT registration.
One of the most common mistakes is treating the threshold as total accounting revenue.
The FTA’s VAT User Guide explains that turnover for registration is based on the value of taxable supplies, which includes zero-rated supplies and excludes exempt supplies.
Taxable supplies are supplies that fall within the UAE VAT system and are subject to either the standard rate or zero rate.
For threshold purposes, the business should assess the value of relevant taxable supplies rather than simply taking the total figure from its income statement.
For example, a service company with AED 300,000 in standard-rated consulting services has relevant taxable turnover that should be considered when assessing its VAT registration position.
Zero-rated supplies are particularly important because zero-rated does not mean exempt. A zero-rated supply is still a taxable supply, even though VAT is charged at 0%. Therefore, a business should not remove zero-rated sales from its threshold calculation simply because the invoices show 0% VAT.
For example, if a business has AED 250,000 of standard-rated supplies and AED 150,000 of qualifying zero-rated supplies, it should not automatically treat its taxable turnover as only AED 250,000.
Exempt supplies are treated differently. The FTA’s VAT User Guide distinguishes taxable supplies, including zero-rated supplies, from exempt supplies. Exempt supplies are not included in taxable turnover in the same way.This distinction can materially affect whether a business has reached the registration threshold.
Businesses may also have transactions that fall outside the scope of UAE VAT. These should not automatically be treated as taxable supplies simply because they appear as revenue or receipts in the accounting records.
The correct VAT treatment should be established before including a transaction in the registration calculation.
Imports can also be relevant to the VAT registration test. The FTA’s current registration guidance specifically refers to the total value of taxable supplies and imports for the mandatory threshold.
Businesses that regularly import goods or services should therefore include their relevant import activity when assessing their registration position rather than looking only at domestic sales.
The UAE VAT registration threshold is not simply a January-to-December annual test. The applicable rules use two important time periods: the previous 12 months and the next 30 days.
The first test looks at the relevant activity during the previous 12 months.
For mandatory registration, a UAE-resident business must assess whether the total value of taxable supplies and imports exceeded AED 375,000 during that period. For voluntary registration, the business can assess whether its taxable supplies and imports, or qualifying taxable expenses, exceeded AED 187,500 during the relevant period.
This means the business should maintain a rolling calculation, rather than checking its turnover only once at year-end.
The FTA also considers what the business expects to happen during the next 30 days. For mandatory registration, a UAE-resident business can become required to register if it anticipates that the value of its taxable supplies and imports will exceed AED 375,000 during the next 30 days.
For voluntary registration, the AED 187,500 threshold can similarly be assessed using expected taxable supplies, imports or qualifying taxable expenses during the next 30 days.
This forward-looking test is important for businesses about to enter a major contract or complete a significant taxable transaction.
Businesses should ideally begin monitoring their VAT position from the start of their commercial activity.
A monthly review can track:
This makes it easier to identify a registration obligation before the deadline becomes urgent.
A UAE trading company has AED 390,000 of relevant taxable supplies and imports over the applicable previous 12-month period. Because the amount exceeds AED 375,000, the business should assess its mandatory VAT registration obligation. It should not wait until the end of the calendar year simply because its financial year has not yet closed.
A consulting business has AED 220,000 of relevant taxable supplies and imports over the applicable period. It has not crossed the AED 375,000 mandatory threshold, but it is above the AED 187,500 voluntary threshold. The business may therefore be eligible to register voluntarily, subject to the applicable rules. It should then consider whether voluntary registration makes commercial and administrative sense.
Suppose a business reports AED 400,000 of total revenue:
Because zero-rated supplies are still taxable supplies, the business cannot simply exclude the AED 150,000 from its taxable turnover calculation.
This example shows why total accounting revenue and taxable turnover are not always interchangeable concepts.
Once a UAE-resident business becomes required to register, the next priority is completing the registration process correctly and on time.
The FTA currently states that a person required to register must submit the VAT registration application within 30 days of becoming required to register. After registration, the business will generally need to manage its VAT obligations, including appropriate invoicing, record keeping, VAT accounting and return filing.
The effective registration position is particularly important because the business needs to know when VAT obligations begin to apply.
Reaching AED 187,500 does not automatically mean that every business should register. Voluntary registration is a business decision that should be considered alongside the company’s customers, costs, growth plans and VAT position.
Voluntary registration may be useful where a business:
For example, a growing company investing heavily in equipment, software and professional services may want to evaluate whether voluntary registration could provide a commercial benefit.
Voluntary registration also creates ongoing responsibilities.
A registered business generally needs to manage:
Therefore, voluntary registration should not be viewed simply as a way to recover VAT on purchases.
A small business may decide that voluntary registration is not worthwhile if it has:
The right decision depends on the business rather than the threshold alone.
The relevant taxable activity and registration conditions therefore matter more than the label used for the business.
This is particularly important where one activity is standard-rated, another is zero-rated and another is exempt.
A trade licence and VAT registration are separate matters.
Having a trade licence does not automatically mean that a business must register for VAT. Similarly, the absence of a particular trade licence does not necessarily remove VAT obligations where a person is carrying out an economic activity covered by the VAT rules.
The VAT position depends on the applicable registration rules and the nature and value of the business’s relevant activities.
For example, adding a new business activity does not automatically create a VAT registration obligation. The business should assess whether the new activity creates taxable supplies and how those supplies affect its overall VAT position.
Some businesses cannot rely solely on the standard AED 375,000 comparison.
The mandatory AED 375,000 threshold is not applicable to foreign businesses in the same way it applies to UAE-resident businesses.
The FTA states that a non-resident business making taxable supplies in the UAE may be required to register regardless of the value of its supplies where there is no other person in the UAE responsible for accounting for the VAT.
This means an overseas business should not assume that UAE taxable sales below AED 375,000 automatically mean no VAT registration is required.
Being located in a free zone does not automatically remove VAT registration requirements.
The FTA has clarified that taxable turnover exceeding the mandatory threshold can require registration whether a business is based in a free zone or on the mainland.
Businesses operating in designated zones should also assess whether special VAT treatment applies to their particular transactions.
A business that makes only qualifying zero-rated supplies may have a different VAT registration position.
The FTA states that a business may apply for an exception from VAT registration if it only makes zero-rated supplies and does not import goods or services subject to the reverse charge, subject to the applicable conditions. A business making both zero-rated and standard-rated supplies is not eligible for this exception.
This is an area where businesses should verify their exact circumstances rather than assuming that all zero-rated businesses can simply remain unregistered.
Failing to act after becoming required to register can create both administrative and financial consequences.
The FTA currently requires a person who is required to register to submit the application within 30 days of becoming required to register. Businesses should therefore identify the point at which the registration obligation arises and retain records supporting that calculation.
The FTA states that a late registration penalty applies when a required person fails to submit the application within the specified timeframe.
A delayed registration can create additional work around:
The safest approach is to monitor the threshold regularly and act as soon as the business identifies a registration obligation.
A monthly review can include the following:
This simple process can help businesses identify changes in their VAT registration position before they become urgent.
VAT registration is completed through the FTA’s EmaraTax platform.
The business needs an active EmaraTax account before beginning the VAT registration application.
The FTA’s current process involves creating a taxable person profile, accessing the taxable person’s account and selecting registration under Value Added Tax.
The applicant completes the required information and uploads the supporting documents relevant to its legal form and circumstances.
The FTA reviews the completed application. The current service page states an estimated processing time of 20 business days from receipt of a completed application.
Once the application is approved, the VAT registration certificate is made available through the taxpayer’s e-Services account.
The exact information required can vary depending on the legal form and circumstances of the applicant.
The FTA’s current VAT registration service identifies supporting information and documents that can include:
For individuals, the FTA indicates that a personal or sole establishment account can be used where applicable.
Businesses should prepare their supporting records before beginning the application so that information submitted to the FTA is complete and consistent.
VAT registration and VAT filing are two different stages of VAT compliance.
Therefore, crossing the registration threshold does not mean a business can simply begin adding VAT to invoices without completing the required registration process.
Once registered, the business needs to establish processes for recording transactions, issuing appropriate tax invoices, reconciling VAT and preparing its VAT returns.
Ripple Accountants helps UAE businesses manage their VAT obligations from VAT registration and threshold assessment to VAT return filing and VAT refund support. The team also provides accounting and bookkeeping, bank reconciliation and financial reporting, helping businesses maintain accurate records for their VAT calculations and compliance.
Contact Ripple Accountant to discuss your requirements.
Learn more about Ripple’s VAT Registration & Filing Services and get support in reviewing your VAT position and registration requirements.
For UAE-resident businesses, the mandatory VAT registration threshold is AED 375,000, while the voluntary registration threshold is AED 187,500, subject to the applicable VAT rules.
For a UAE-resident business, VAT registration is generally mandatory when the value of taxable supplies and imports exceeds AED 375,000 over the previous 12 months or is expected to exceed that amount during the next 30 days.
Yes. A UAE-resident business that does not meet the mandatory registration criteria may generally apply voluntarily if its taxable supplies and imports or qualifying taxable expenses exceed AED 187,500 under the applicable previous-12-month or next-30-day test.
Zero-rated supplies can count because they are taxable supplies. Exempt supplies are treated differently and are not included in taxable turnover in the same way.
For mandatory registration, the business looks at taxable supplies and imports over the previous 12 months and what it expects during the next 30 days. Voluntary registration can additionally consider qualifying taxable expenses.
They may need to register if the applicable VAT registration conditions are met. VAT registration provisions can apply to natural persons carrying out economic activities, so being a freelancer or small business does not automatically remove VAT obligations.
The UAE VAT registration threshold helps determine whether a business must register for VAT or may choose to register voluntarily. For UAE-resident businesses, AED 375,000 is the mandatory registration threshold, while AED 187,500 is the voluntary registration threshold, subject to the applicable rules. The calculation is not simply based on total bank receipts or a calendar year’s revenue. Businesses need to assess taxable supplies, zero-rated supplies, relevant imports and the applicable previous-12-month and next-30-day tests. For non-resident businesses and other special situations, separate rules may apply.
Disclaimer: This article is provided for general informational purposes only and does not constitute tax, accounting, legal or other professional advice. UAE VAT registration requirements, thresholds, procedures and administrative rules may change, and the correct treatment depends on the facts and circumstances of each business. Businesses should refer to the latest guidance and legislation issued by the Federal Tax Authority and obtain professional advice where necessary.
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
 Bookkeeping
Non-current assets and capital expenditures play a critical role in a company’s long-term financial health. Whether you own a startup, manage an…
Read article Bookkeeping
Expanding into international markets is an exciting milestone for any business. It opens the door to new customers, increased revenue, and long-term…
Read article Compliance
Financial instruments play a critical role in modern business, from trade receivables and business loans to investments and corporate debt. To improve…
Read articlePage 41 of 45
Book a free consultation and get clear answers for your business.
0 Comments