Input VAT vs Output VAT UAE: A Practical Guide
Do you know the difference between the VAT your business charges customers and the VAT it pays on business expenses? Understanding input…
Read article
Has your UAE business accumulated more recoverable input VAT than output VAT, and are you unsure whether you can claim the difference back?
A UAE VAT refund may be available when a VAT-registered business is in a net refundable position after filing its VAT return. However, having a VAT credit does not mean the refund should be claimed without checking the underlying transactions and supporting records. Businesses should verify that the input VAT is recoverable, that the VAT return is accurate and that the documents supporting the claim are available before submitting a refund request. Understanding the eligibility conditions and records required can help businesses prepare a more complete claim and reduce avoidable delays.
A VAT refund occurs when a taxable person has a refundable VAT balance that can be claimed from the Federal Tax Authority (FTA).
For a VAT-registered business, the VAT position for a tax period is generally determined by comparing recoverable input VAT with output VAT. When recoverable input VAT exceeds output VAT, the business may have a net refundable position.
The FTA’s VAT guidance confirms that a taxable person can request a refund when there is a credit or when input VAT is greater than output VAT.
A business may therefore have a VAT credit because, for example, it has made substantial purchases or incurred significant business expenses during a period while generating comparatively lower taxable sales. However, the existence of a credit balance should not be treated as automatic evidence that every amount of input VAT is refundable.
The most common situation is when a business has more recoverable input VAT than output VAT for a tax period.
For example, suppose a business has:
The difference is AED 30,000. Subject to the applicable VAT recovery conditions and the accuracy of the return, the business may have a refundable VAT position of AED 30,000.
The business can request the refund after submitting the relevant VAT return. The FTA confirms that a refund request can be submitted when a taxable person is in a net refundable position.
A business does not necessarily have to request a refund immediately every time it has a VAT credit. A business may instead carry a credit forward and use it against future VAT liabilities, depending on its circumstances.
The FTA’s EmaraTax FAQ confirms that VAT311 can be used to request refunds relating to one or more tax periods where the taxpayer was in a refundable position.
This gives businesses an opportunity to consider whether receiving the cash refund or carrying the credit forward better fits their circumstances.
VAT refunds are not limited to ordinary taxable persons with refundable VAT positions.
The FTA identifies several refund categories, including:
Each category has its own eligibility conditions and application process. This article focuses primarily on VAT refunds relevant to UAE VAT-registered businesses rather than tourist or other special refund schemes.
Before submitting a refund request, businesses should review the transactions included in the VAT return.
Not every expense automatically gives a business the right to recover VAT. The business should determine whether the underlying purchase relates to activities for which input VAT recovery is permitted under UAE VAT rules.
The FTA’s VAT return guidance states that recoverable input tax requires appropriate evidence of the VAT charged and that the relevant payment conditions must also be satisfied. Businesses should therefore review large or unusual input VAT amounts before including them in a refund claim.
Tax invoices provide important evidence supporting input VAT recovery. Businesses should check whether invoices are available and contain the relevant information required under UAE VAT rules.
Missing, incomplete or inconsistent invoices can make it more difficult to substantiate the input VAT included in a refund position.
The VAT return should agree with the underlying accounting records. Before requesting a refund, businesses can reconcile:
This helps identify differences before the refund application is submitted.
The FTA’s current refund service page identifies the following documents for VAT311 refund requests:
The FTA may also request additional information where the application requires further review.
Businesses should therefore maintain a clear evidence trail rather than preparing documents only after the refund application has been submitted.
A structured review can help businesses identify issues before filing the refund request.
Start by determining whether the submitted VAT return shows a net refundable position. Compare total recoverable input VAT with output VAT and confirm the resulting balance.
Large transactions should receive particular attention. Check the underlying invoices, suppliers, VAT amounts, payment records and accounting entries.
Reconcile the input and output VAT reports against the VAT return and general ledger. Any unexplained differences should be investigated before the refund request is submitted.
Make sure the business can produce the invoices and other records supporting the refund position. The FTA can request additional information where required, so businesses should retain relevant evidence in an organised format.
After the VAT return has been submitted and the business is in a net refundable position, the refund request can be submitted through EmaraTax using VAT311. The FTA confirms this process in its current service information and FAQs.
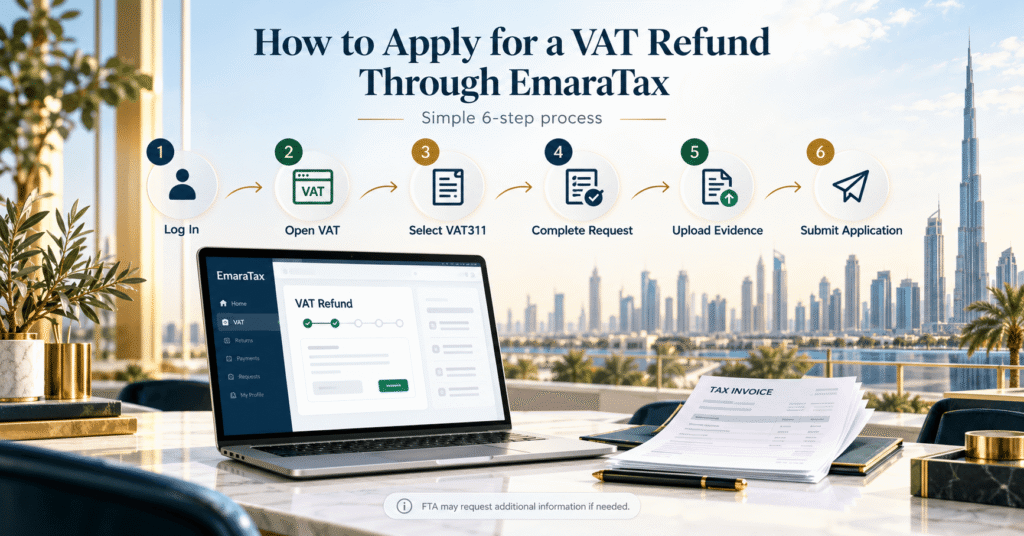
For a standard refund claim by a VAT-registered taxable person, the process involves:
Access the business’s EmaraTax account.
Go to the VAT section of the dashboard.
The FTA identifies VAT311 as the relevant refund request for VAT.
Provide the required information and identify the relevant refundable VAT position.
Upload the required tax reports, invoices and supporting documents.
The FTA’s EmaraTax information confirms that supporting evidence can be submitted online with the refund claim.
Review the information and submit the refund request through the platform. The FTA may review the claim and request additional information if required.
The FTA’s current service page states that a completed refund application is generally processed within 25 business days from receipt. Where the request requires additional investigation by audit, the FTA states that processing may take 55 working days from the date all requested information is provided.
Businesses should therefore avoid treating the refund as immediately available cash when preparing short-term cash-flow forecasts.
The actual timing can depend on whether the application is complete and whether additional information or review is required.
A refund request may require additional information where the FTA needs to verify the claim. Potential areas that businesses should review include:
Before submitting a refund request, businesses can use this checklist:
A business with a VAT credit may have a practical choice between requesting a refund and retaining the credit for future VAT liabilities, depending on the applicable rules and its circumstances.
For example, a business with regular taxable sales and expected VAT liabilities may choose to use the credit against future obligations. Another business may have a significant cash requirement and prefer to request a refund where it is eligible.
The decision should be based on the business’s cash-flow position, expected future VAT liabilities and the quality of the supporting documentation. The important point is that a VAT credit should be reconciled and understood before management decides how to use it.
VAT is often treated as a compliance issue, but refundable VAT can also affect business cash flow. A company that has paid substantial VAT on business purchases may have a significant amount tied up in its VAT account while waiting to recover it.
Accurate bookkeeping and timely VAT reconciliations can help management identify refundable positions earlier. They can also help the business distinguish between:
This makes the refund process part of a broader financial control process rather than simply an administrative filing task.
A VAT refund claim requires more than identifying a credit balance. The underlying transactions, VAT treatment, accounting records and supporting documents should be reviewed before a claim is submitted.
Ripple Accounting, Tax & Advisory can support UAE businesses with VAT compliance, VAT return preparation and related tax requirements. If your business has a refundable VAT position, Ripple can help review the VAT records, reconcile input and output VAT, identify documentation gaps and prepare the business for the relevant refund process.
Contact Ripple Accounting, Tax & Advisory for a tailored VAT compliance review and practical support with your UAE VAT requirements.
A VAT-registered business that is in a net refundable position can submit a refund request through EmaraTax using VAT311 after submitting the relevant VAT return. The FTA may require supporting tax reports, invoices and other documents.
The FTA’s current refund service identifies the output and input tax report, tax invoices and supporting documents for VAT311 refund requests. The FTA may request additional information where required.
Yes, a taxable person may request a refund when it is in a net refundable position, subject to the applicable VAT recovery rules and supporting evidence.
The FTA currently states that a completed refund application generally takes 25 business days to process. If further audit investigation is required, the FTA states that the process may take 55 working days from the date all requested information is provided.
A business may be able to retain a VAT credit and use it against future VAT liabilities rather than requesting an immediate refund. The appropriate approach depends on the business’s VAT position and circumstances.
A UAE VAT refund can help a business recover eligible input VAT when it is in a net refundable position. However, the refund process should begin with accurate VAT reporting and a review of the transactions supporting the claim. Businesses should reconcile input and output VAT, verify the recoverability of input tax and maintain tax invoices and other supporting records before submitting a VAT311 request through EmaraTax. A well-organised VAT refund process can also help businesses manage cash flow while maintaining reliable tax records.
Disclaimer: This article is provided for general informational purposes only and does not constitute tax, legal or financial advice. VAT recovery and refund eligibility depend on the nature of the transactions, applicable UAE VAT legislation, FTA guidance and the specific circumstances of the business. FTA procedures, processing times and documentation requirements may change. Businesses should verify the latest requirements with the Federal Tax Authority or seek professional tax advice before submitting a refund claim.
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
 VAT
Do you know the difference between the VAT your business charges customers and the VAT it pays on business expenses? Understanding input…
Read article VAT
Are small VAT return mistakes creating more work for your finance team than the VAT filing itself? For VAT-registered businesses in the…
Read article Compliance
Are you sure your construction payroll shows not only who was paid, but also which site and project incurred the labor cost?…
Read articlePage 4 of 45
Book a free consultation and get clear answers for your business.
0 Comments