When Does a UAE SME Need a Virtual CFO?
Is your UAE SME making more money but still struggling to understand where the money is going? Many small and medium-sized businesses…
Read article
How long should your UAE business keep VAT invoices, credit notes, import records and other tax documents and what happens if the FTA needs them later?
UAE VAT record keeping is an important part of maintaining accurate tax records and supporting VAT returns. Businesses registered for VAT need to retain specific records, invoices and supporting documents for the required period and in a way that allows the Federal Tax Authority (FTA) to verify their tax obligations. The standard retention period for taxable persons is generally five years, although specific records and circumstances can require a longer period.
Let’s look at what UAE businesses need to retain and how to organise their VAT records properly.
UAE VAT record keeping means maintaining the documents, accounting information and transaction records needed to support a business’s VAT position. These records help establish:
The UAE VAT legislation requires taxable persons to maintain specific records, including records of supplies and imports, tax invoices, tax credit notes, export records and VAT-related adjustments.
Good record keeping therefore creates an audit trail between business transactions, accounting records and VAT returns.
For most taxable persons, the general record-keeping period is five years after the end of the relevant Tax Period.
The current Tax Procedures Executive Regulation provides that accounting records, commercial books and information must generally be retained for five years following the Tax Period to which they relate for a taxable person.
The FTA also specifically confirms that taxable persons must retain VAT invoices issued and received for a minimum of five years.
However, businesses should not assume that five years always represents the maximum period for every document. Additional retention requirements can apply in particular circumstances.
The Tax Procedures Executive Regulation provides additional periods in certain situations.
If there is a dispute between the taxpayer and the FTA concerning tax obligations, records may need to be retained for an additional four years or until the dispute is finally settled, whichever is later.
This means a business involved in a tax dispute should not automatically destroy documents merely because the normal five-year period has passed.
If the business is subject to an ongoing tax audit, the records may need to be retained for an additional four years.
The same consideration applies where the FTA has notified the business of its intention to conduct a tax audit before the normal retention period expires.
The regulation also provides an additional one-year retention period in a specific situation where a taxable person submits a Voluntary Disclosure in the fifth year from the end of the relevant Tax Period.
Businesses should therefore check whether any dispute, audit or disclosure is connected with the records before applying their normal document-destruction policy.
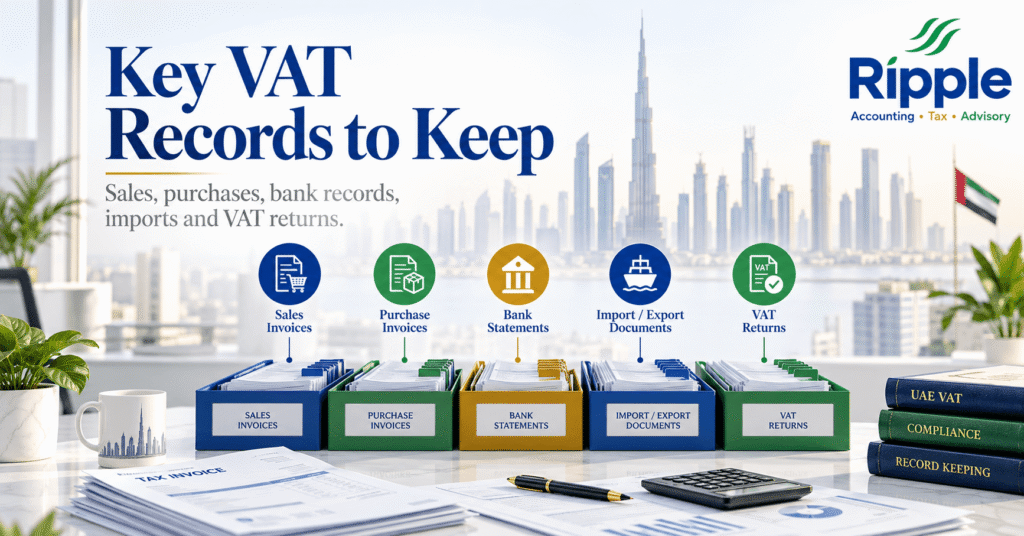
The UAE VAT legislation identifies several categories of records that taxable persons must maintain.
Businesses should maintain records of their supplies and imports of goods and services. These records help establish the transactions that form part of the business’s VAT position. For example, a business may need records showing:
The information should be detailed enough to support the VAT treatment reported in the business’s records and returns.
Businesses should retain tax invoices and alternative documents received from suppliers. These documents are particularly important when the business claims input VAT. A proper invoice trail can help establish:
The FTA specifically confirms that VAT invoices received and issued must be retained for a minimum of five years.
Businesses should also retain copies or appropriate records of tax invoices issued to customers. These records support the output VAT reported by the business. Businesses should have a consistent method for storing invoices so that individual transactions can be retrieved when required.
Tax credit notes can affect the VAT originally reported on a transaction. Businesses should therefore retain both credit notes received and credit notes issued, along with the relevant supporting transaction information. This becomes particularly important when an adjustment changes the amount of VAT originally accounted for.
Businesses making exports should retain appropriate records supporting those transactions. Export transactions can involve specific VAT treatment, so the business should maintain sufficient evidence to support the treatment applied. This can include relevant commercial and shipping documentation depending on the transaction.
VAT records should not only show the original transaction. Businesses should also maintain records of adjustments or corrections made to accounts or tax invoices.
For example, if an accounting error is identified and corrected, the supporting documentation should explain:
This creates a clearer audit trail.
In addition to individual transaction records, taxable persons must maintain a VAT record containing relevant information about their VAT position. The VAT legislation identifies information including:
This information should be capable of supporting the figures reported in the business’s VAT returns.
A well-maintained VAT record can therefore provide a bridge between the underlying transactions and the VAT return.
A practical VAT retention checklist can help businesses avoid missing important documents.
The exact documents required will depend on the nature and activities of the business.
Keeping documents for five years is only useful if the business can retrieve them when needed. Businesses should establish a consistent document-management process.
VAT records can be organised by:
The chosen structure should be consistent across the business.
Many businesses now retain VAT records electronically. Digital storage can make it easier to search and retrieve documents, but businesses should consider:
The goal is to ensure that records remain available and usable throughout the required retention period.
A good record-keeping system should allow a transaction to be followed from the original document through accounting records and ultimately to the relevant VAT return.
For example:
Supplier invoice → Accounting entry → Input VAT calculation → VAT return → Payment/refund position
Similarly, for sales:
Customer invoice → Accounting entry → Output VAT → VAT return
This type of audit trail can make it easier to explain VAT figures during an internal review or FTA interaction.
Missing VAT records can make it difficult for a business to demonstrate how it calculated its VAT position.
For example, a business may report input VAT in its VAT return but struggle to produce the supporting invoices when asked to substantiate the claim.
Similarly, incomplete sales records may make it harder to demonstrate how output VAT was calculated.
This is why businesses should not wait for an FTA request before checking whether their records are complete. A periodic records review can identify gaps while the relevant employees, suppliers and systems are still available to resolve them.
Businesses should have appropriate procedures for transferring records when employees change roles or leave.
Ripple Accounting, Tax & Advisory supports UAE businesses with a range of accounting, tax and financial services, including VAT registration and filing, accounting and bookkeeping, financial reporting, budgeting and forecasting, payroll services, Corporate Tax support, audit support and compliance review. For VAT-related requirements, Ripple can assist businesses with maintaining organized VAT records, reviewing transaction documentation, supporting VAT return preparation and identifying record-keeping gaps. periods.
If your business is unsure whether its VAT records are complete or properly organised, contact Ripple Accounting, Tax & Advisory for a tailored VAT record review and compliance assessment.
Taxable persons generally need to retain relevant tax records for five years after the end of the Tax Period to which they relate. VAT invoices issued and received must also be retained for a minimum of five years. Certain circumstances can require longer retention.
Businesses should retain records of supplies and imports, tax invoices issued and received, credit notes, export records, records of adjustments and corrections, and VAT records showing output and recoverable input VAT.
Businesses may maintain records electronically, provided the records are maintained in a manner that supports the relevant tax obligations and allows the information to be retrieved when required. Businesses should use secure, organised storage and appropriate backup procedures.
No. Additional retention periods can apply in circumstances such as an ongoing tax dispute, an ongoing tax audit or where the FTA has notified the business of its intention to conduct a tax audit. The Tax Procedures Executive Regulation sets out these additional periods.
Yes. Ripple Accounting, Tax & Advisory can support businesses with VAT registration and filing, VAT record reviews, accounting and bookkeeping, financial reporting, compliance reviews and other related accounting and tax services.
UAE VAT record keeping requires more than simply saving tax invoices. Businesses should maintain the records needed to support their VAT calculations, including sales and purchase records, tax invoices, credit notes, import and export records, VAT accounts, adjustments and supporting documentation. For taxable persons, the general retention period is five years after the end of the relevant Tax Period, while specific circumstances can require records to be kept for longer. A structured filing system, regular reconciliation and clear audit trail can help businesses retrieve the right documents when needed and support the VAT position reported to the FTA.
Disclaimer: This article provides general information about UAE VAT record keeping and is not tax or legal advice. Retention requirements can vary depending on the type of record, the taxpayer’s circumstances and applicable UAE legislation. Businesses should verify the current requirements with the Federal Tax Authority or obtain professional advice before destroying or disposing of tax records.
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
 Compliance
Is your UAE SME making more money but still struggling to understand where the money is going? Many small and medium-sized businesses…
Read article Bookkeeping
Is your trading business profitable on paper but still struggling to keep enough cash available for suppliers, inventory and day-to-day expenses? Trading…
Read article Compliance
Could your startup produce accurate VAT and Corporate Tax records if the FTA asked for them tomorrow? For many UAE startups, accounting…
Read articlePage 9 of 59
Book a free consultation and get clear answers for your business.
0 Comments