UAE Tax Residency Certificate Requirements: Documents and Eligibility
M Maria October 16, 2026 13 min read
Are you planning to apply for a UAE Tax Residency Certificate but unsure which documents you need or whether you qualify?
Understanding the UAE TRC requirements before submitting an application can help you avoid missing paperwork and unnecessary delays. Whether you are an individual, entrepreneur or company, reviewing your residency evidence and financial records is an important first step.
This guide explains the eligibility criteria, required documents and application process for obtaining a UAE Tax Residency Certificate. Exploring the tax residency certificate support available from Ripple Accountants can also help you prepare for the process with greater confidence.
Let’s get started!
What Is a UAE Tax Residency Certificate?
A UAE Tax Residency Certificate (TRC), also referred to as a tax domicile certificate, is an official certificate issued by the Federal Tax Authority (FTA) to eligible applicants who meet the applicable requirements.
The certificate may be used to establish UAE tax residency for a particular period. Depending on the certificate type and the applicable rules, it can support an individual’s or company’s request to benefit from an agreement for the avoidance of double taxation between the UAE and another country.
For example, a UAE-based professional receiving income from abroad may need evidence of UAE tax residency when dealing with a foreign tax authority. Similarly, a company conducting cross-border business may need a certificate to support its treaty-related tax position.
However, obtaining a TRC does not automatically guarantee tax relief in another country. The relevant tax treaty, income type, supporting evidence and foreign jurisdiction’s procedures must also be considered.
The FTA distinguishes between certificates for domestic purposes and treaty purposes. Selecting the correct category is essential because the eligibility criteria and supporting documents can differ.
Who Is Eligible for a UAE Tax Residency Certificate?
Eligibility depends on the applicant’s legal status, physical presence, residence arrangements, financial circumstances and intended use of the certificate.
1. Individuals
Individuals may apply if they meet the relevant UAE tax residency criteria for the requested period. Depending on the application category, this may involve demonstrating the number of days spent in the UAE, holding appropriate residency documents, establishing a permanent place of residence, or showing that the UAE is their usual or primary residence and the centre of their financial and personal interests.
The evidence required will depend on the circumstances and the certificate’s purpose.
2. Companies and other legal persons
A company may be eligible if it satisfies the applicable conditions for UAE tax residency and provides the required corporate documentation.
For a treaty-purpose application, the FTA’s published guidance states that a legal person must generally have been established in the UAE for at least one year. The applicant must also provide evidence relevant to the requested period and its legal and financial position.
3. Applicants with international income or business interests
Individuals and businesses involved in cross-border transactions may seek a TRC to support their tax position under an applicable double taxation agreement.
Before applying, applicants should confirm that the certificate is appropriate for their circumstances. A TRC is not a substitute for checking the specific treaty conditions or determining whether the foreign country will accept the certificate for the intended claim.
UAE TRC Requirements for Individuals
The documents required for an individual application depend on the certificate purpose and the applicant’s residency circumstances.
Physical presence and residency evidence
For domestic-purpose applications, the FTA’s guidance identifies different categories based on the number of days spent in the UAE. These include applicants who have spent more than 183 days, between 90 and 183 days, or fewer than 90 days in the UAE.
The relevant eligibility criteria and supporting evidence must be assessed for the application type. The categories should not be interpreted as guaranteeing approval solely because an applicant falls within a particular day-count range.
For treaty-purpose applications, the FTA FAQ states that an individual must have been a UAE resident for at least 183 days during the required financial year. Applicants should verify the applicable requirements for their particular application and requested period.
Evidence of residence and personal circumstances
Depending on the circumstances, an applicant may need to provide:
A valid Emirates ID and UAE residence visa, where applicable.
A passport copy and official entry-and-exit report.
A certified tenancy contract or lease agreement.
A property title deed and relevant utility bills, where applicable.
Evidence of employment, salary or business income.
Local bank statements covering the relevant period.
Applicants relying on the UAE as their primary residence or the centre of their financial and personal interests may need additional evidence to demonstrate their circumstances.
The FTA may request further documents where necessary to determine whether the applicant meets the applicable tax residency criteria.
Documents Required for a UAE TRC
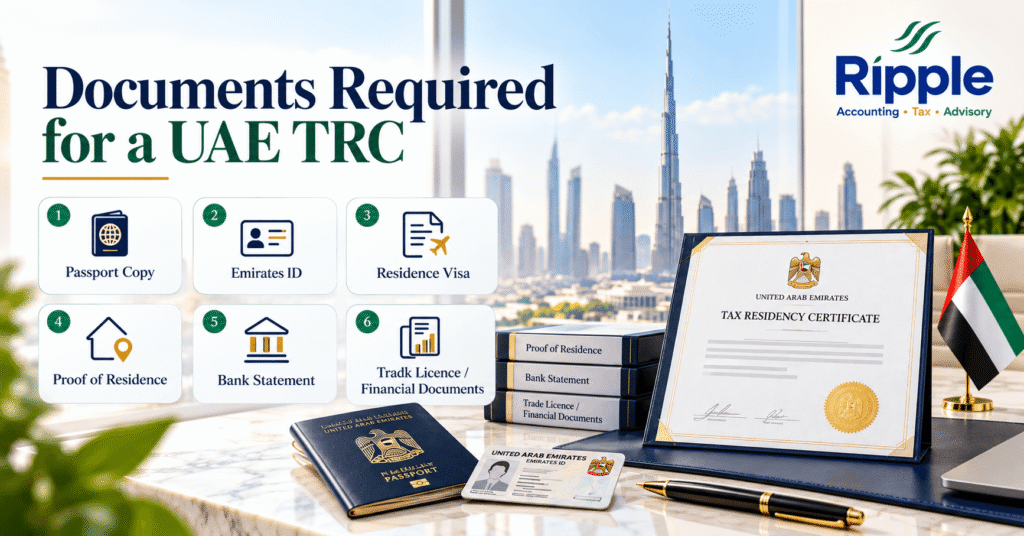
Preparing a complete document file before applying can make the process easier. The following checklist outlines common supporting documents; the exact requirements depend on the applicant’s category and the period requested.
Documents for individuals
Document
Why it may be required
Passport copy
Establishes identity and supports immigration records
Emirates ID and residence visa
Supports UAE residency information, where applicable
Entry-and-exit report
Demonstrates physical presence in the UAE
Tenancy agreement or title deed
Supports evidence of a permanent place of residence
Utility bills
May support the claimed residential address and period
Salary certificate or employment evidence
Supports employment and income information
Local bank statements
Provides evidence of financial activity during the relevant period
Business licence or other business evidence
May be required for self-employed applicants
Additional supporting documents
Addresses individual circumstances or country-specific requirements
Not every applicant will need every document. For example, an individual relying on employment income may submit different evidence from a self-employed applicant or a person relying on investments.
The FTA’s application guidance also identifies supporting documents such as marriage certificates in certain spouse-sponsored cases, property lease agreements for rental income, and evidence of savings or investments for some retired applicants.
Documents for companies
Companies applying for a TRC should prepare their corporate and financial records in advance. Common requirements for treaty-purpose applications include:
A valid UAE trade licence.
A certificate of incorporation or equivalent establishment document, where applicable.
Memorandum of Association or other constitutional documents, where applicable.
Proof that the authorised representative can submit the application.
An audited financial report certified by an independent auditor, as specified in the FTA’s application guidance.
An office lease or tenancy contract.
A local bank statement covering six months within the relevant financial year.
The FTA’s published user manual also specifies that the financial audit report should cover the requested financial year’s start date or the preceding year, as applicable to the application instructions.
Companies should check the current portal requirements before submitting their files, particularly if their legal structure, reporting period or establishment date differs from a straightforward UAE-incorporated business.
Domestic-Purpose TRC vs Treaty-Purpose TRC
One of the most important UAE TRC requirements is choosing the correct certificate purpose.
Area
Domestic-purpose TRC
Treaty-purpose TRC
Intended use
Evidence of UAE tax residency for a domestic purpose
Supporting a claim under an applicable double taxation agreement
Individual eligibility
Assessed under the relevant UAE domestic criteria
Includes the treaty-purpose conditions specified by the FTA
Day-count consideration
Relevant categories include more than 183 days, 90–183 days and fewer than 90 days
FTA guidance specifies at least 183 days during the required financial year for individuals
Company eligibility
Assessed according to the relevant domestic requirements
FTA guidance generally requires at least one year of establishment
Supporting evidence
Depends on the applicant’s circumstances
May include residency, financial, corporate and treaty-related evidence
These are broad distinctions rather than a complete eligibility test. The FTA’s published rules and portal instructions should be checked for the specific certificate being requested.
For example, an individual who needs to demonstrate tax residency to a foreign tax authority may require a treaty-purpose certificate rather than one intended only for domestic use. Selecting the wrong purpose could mean that the resulting certificate does not meet the applicant’s intended needs.
Applicants should also check whether the destination country requires a specific form, additional certification or other documentation alongside the UAE TRC.
If you want to explore the key differences between UAE Tax Residency Certificates for domestic and treaty purposes in detail, read our comprehensive guide: Domestic-Purpose TRC vs Treaty-Purpose TRC
How to Apply for a UAE Tax Residency Certificate
The FTA provides an online application process through its tax services platform. Applicants can follow these general steps.
Step 1: Identify the correct certificate type
Determine whether the application is for domestic purposes or treaty purposes. Consider why the certificate is needed, the relevant period and any requirements communicated by the foreign tax authority.
Step 2: Gather the supporting documents
Collect identification, immigration, residence, employment, banking or corporate documents appropriate to the application. Ensure that they cover the relevant period and that the information is consistent.
Enter the requested applicant details, certificate purpose and relevant period. Upload the supporting documents according to the instructions displayed in the application.
Step 5: Review and submit
Check that names, identification numbers, dates and corporate information match the supporting documents. Confirm that all required files are legible and relate to the correct applicant.
Step 6: Pay the applicable fees
Review the fee displayed for the selected application category and applicant status. Keep the payment confirmation for your records.
Step 7: Monitor the application
Check the portal for updates or requests for additional information. Respond promptly if the FTA asks for clarification or further evidence.
The FTA’s published FAQ provides a reference processing period of five working days for reviewing an application, but applicants should check current service information and allow for additional time if clarification or further documents are required.
UAE TRC Application Fees and Processing Time
The cost of obtaining a Tax Residency Certificate depends on the applicant’s category and whether the applicant is registered with the FTA.
The FTA’s published FAQ lists the following fees:
Fee component
Individuals
Legal persons
Application submission fee
AED 50
AED 50
Certificate fee for registered applicants
AED 500
AED 500
Certificate fee for non-registered applicants
AED 1,000
AED 1,750
Printed certificate, if requested
AED 250
AED 250
These amounts are based on the FTA’s published fee information. Applicants should verify the current fees shown in the official portal before submitting an application, as the applicable charge may depend on the service selected.
The published FAQ states that the FTA reviews applications within five working days. This should be treated as a reference rather than a guarantee of issuance within that period. Incomplete applications, discrepancies in supporting records or requests for further evidence may affect the overall timeline.
Common Mistakes to Avoid When Applying for a UAE TRC
Even applicants who appear to meet the eligibility criteria can encounter problems if their documents do not adequately support their applications.
Choosing the wrong certificate purpose: Applying for a domestic-purpose certificate when a foreign tax authority requires treaty-related evidence may not achieve the intended outcome.
Submitting incomplete residency evidence: Missing immigration reports, insufficient address documentation or gaps in the requested period can make it harder to establish eligibility.
Providing inconsistent personal information: Differences in names, identification details, addresses or dates across documents may require clarification.
Overlooking company documentation: Businesses may need valid licences, authorisation documents, audited financial statements and banking evidence, depending on the application category.
Assuming that a residence visa automatically qualifies the applicant: Immigration status and tax residency are not interchangeable. The applicable tax residency criteria must still be met.
Ignoring foreign-country requirements: A UAE TRC does not automatically establish eligibility for treaty relief in another jurisdiction. The applicant should review the relevant treaty and the receiving authority’s requirements.
A careful document review before submission can help identify these issues early and reduce avoidable delays.
How Ripple Accounting, Tax & Advisory Can Help
Determining the appropriate Tax Residency Certificate (TRC) purpose and preparing supporting documents can be challenging, particularly for applicants with overseas income, company interests or cross-border transactions.
Ripple Accounting, Tax & Advisory can help individuals and businesses understand the documentation requirements for a UAE Tax Residency Certificate, organize relevant financial records and navigate the application process. Whether you need a TRC for domestic administrative purposes or to explore benefits under a double taxation agreement, obtaining guidance on the applicable requirements can help you prepare more effectively.
If you need assistance with your UAE Tax Residency Certificate application, explore Ripple Accountants services to discuss your circumstances, documentation requirements and the support available for your tax residency needs.
Email: info@uaetaxcompliance.ae
Phone: +971 52 356 5409
WhatsApp: +971 4 250 0833
Frequently Asked Questions About UAE TRC Requirements
1. What are the main UAE TRC requirements?
The main requirements depend on whether the applicant is an individual or a company and whether the certificate is for domestic or treaty purposes. Supporting evidence may include identification documents, immigration records, proof of residence, income records, bank statements and corporate documents.
2. Can I apply for a UAE TRC with fewer than 183 days in the country?
Eligibility depends on the certificate purpose and the applicable criteria. The FTA identifies different day-count categories for domestic-purpose applications, including applicants who have spent between 90 and 183 days or fewer than 90 days in the UAE. Treaty-purpose applications have separate conditions, and applicants should check the requirements applicable to their circumstances.
3. Is a UAE residence visa enough to obtain a TRC?
No. A residence visa can support an application, but it does not automatically establish eligibility. The applicant must meet the relevant tax residency criteria and provide the required supporting evidence.
4. How long does it take to obtain a UAE Tax Residency Certificate?
The FTA’s published FAQ refers to a five-working-day application review period. Actual processing may vary depending on the application, the completeness of the documents and whether additional information is requested.
5. Does a UAE TRC guarantee tax exemption in another country?
No. A TRC may support a claim under an applicable double taxation agreement, but it does not guarantee an exemption, refund or reduced tax rate. The relevant treaty provisions and the foreign jurisdiction’s requirements must also be satisfied.
Conclusion
Understanding the UAE TRC requirements before applying can help individuals and companies identify the appropriate certificate type, establish eligibility and prepare the necessary documents. Residency evidence, financial records and corporate documentation should be consistent with the requested period and the purpose of the application.
Before submitting your request, review the latest guidance from the Federal Tax Authority and confirm whether additional documentation is needed for your circumstances. Where financial records or business documentation require attention, Ripple Accounting, Tax & Advisory can provide relevant accounting, bookkeeping and tax advisory support to help you prepare more effectively.
Disclaimer: This article is for general informational purposes only and does not constitute tax or legal advice. UAE Tax Residency Certificate eligibility, documentation requirements, fees and processing arrangements may vary according to the applicant’s circumstances and the applicable rules. Always consult the latest Federal Tax Authority guidance or a qualified adviser before applying.
Non-profit organizations play a vital role in supporting communities, advancing education, promoting healthcare, protecting the environment, and delivering humanitarian aid across the…
Businesses have traditionally relied on financial reports such as revenue, profit, cash flow, and expenses to evaluate performance. While these metrics remain…
Auditing different types of businesses is essential because every industry operates with unique financial processes, regulations, and risks. A manufacturing company manages…



0 Comments