Businesses in the UAE regularly purchase goods and services from overseas suppliers. While these suppliers may not charge UAE Value Added Tax (VAT), the transaction may still be subject to VAT under the UAE Reverse Charge Mechanism (RCM). Understanding how the reverse charge works is essential for maintaining accurate accounting records, filing VAT returns correctly, and complying with the requirements of the UAE’s Federal Tax Authority (FTA).
The Reverse Charge Mechanism shifts the responsibility for accounting for VAT from the foreign supplier to the UAE VAT-registered recipient. Instead of paying VAT to the supplier, the UAE business records both output VAT and, where eligible, recoverable input VAT in its accounting records and VAT return.
What Is the UAE Reverse Charge Mechanism?
The UAE Reverse Charge Mechanism is a VAT accounting method under which the responsibility for accounting for VAT shifts from the supplier to the recipient of goods or services. Instead of the overseas supplier charging UAE VAT, the VAT-registered business in the UAE calculates and reports the VAT itself.
The mechanism is designed to ensure that imported goods and services are taxed consistently with locally supplied goods and services. It also prevents foreign suppliers that are not registered for UAE VAT from having to register solely because they supply goods or services to UAE businesses.
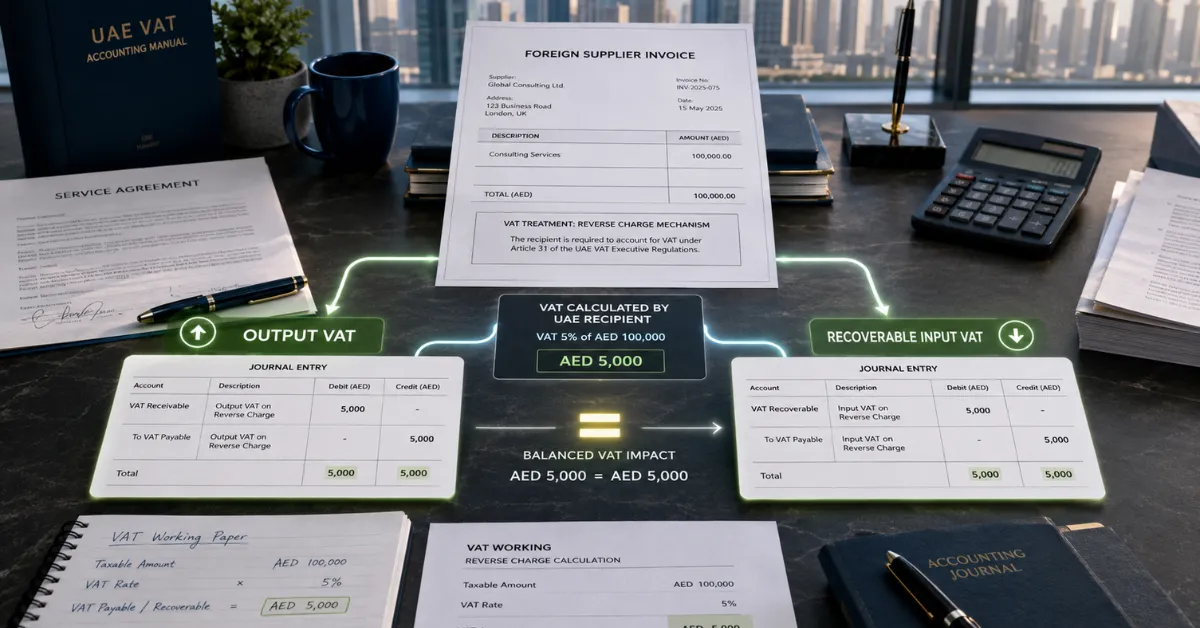
When the reverse charge applies, the UAE business must calculate the VAT due on the transaction at the applicable UAE VAT rate. If the business is entitled to recover input VAT under the UAE VAT rules, it may claim the same amount as recoverable input tax in the same VAT period, subject to the normal recovery conditions.
This process helps maintain VAT neutrality for fully taxable businesses while ensuring compliance with UAE VAT legislation.
Key Features of the UAE Reverse Charge Mechanism
Applies mainly to VAT-registered businesses.
Transfers VAT accounting responsibility to the UAE recipient.
Commonly applies to imported goods and imported services.
Requires businesses to account for both output VAT and recoverable input VAT where permitted.
Must be reported correctly in the UAE VAT return.
Requires accurate accounting records and supporting documentation.
Why Was the Reverse Charge Mechanism Introduced?
The Reverse Charge Mechanism supports the UAE VAT system by ensuring imported transactions receive the same VAT treatment as domestic supplies. Without this mechanism, overseas suppliers would often need to register for UAE VAT, creating unnecessary administrative burdens.
The objectives of the reverse charge include:
Ensuring fair taxation between local and foreign suppliers.
Simplifying VAT compliance for overseas businesses.
Protecting government tax revenue.
Reducing opportunities for VAT avoidance.
Supporting efficient VAT administration.
Maintaining consistency across international business transactions.
For UAE businesses, the reverse charge simplifies cross-border purchasing while placing greater responsibility on finance teams to account for VAT correctly.
When Does the Reverse Charge Mechanism Apply in the UAE?
The Reverse Charge Mechanism applies only in specific situations defined under the UAE VAT framework. Businesses should review every overseas purchase to determine whether reverse charge accounting is required.
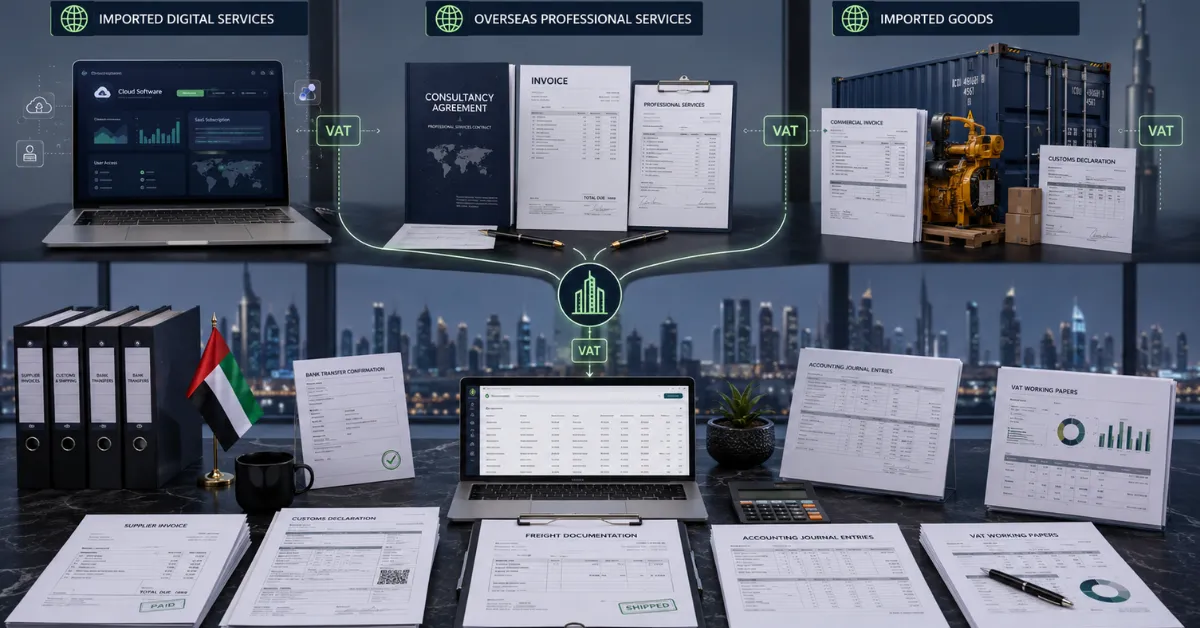
Imported Services
The reverse charge commonly applies when a UAE VAT-registered business purchases services from suppliers located outside the UAE that are not required to charge UAE VAT.
Common examples include:
Software as a Service (SaaS) subscriptions
Cloud computing services
Digital advertising campaigns
Online marketing services
IT support services
Website development services
Software licensing fees
Legal consultancy from overseas firms
International accounting or audit consultancy
Business management consultancy
Engineering and technical consulting
Design and creative services
Training delivered by foreign providers
In these situations, the UAE business generally accounts for VAT under the reverse charge rules instead of paying VAT to the supplier.
Imported Goods
The reverse charge may also apply to imported goods in circumstances specified under UAE VAT and customs regulations.
Examples include:
Machinery imports
Manufacturing equipment
Commercial inventory
Raw materials
Electronic equipment
Office equipment purchased from overseas suppliers
Businesses should distinguish between customs procedures and VAT reporting requirements, as import VAT treatment can vary depending on the import process and applicable regulations.
Purchases from Overseas Suppliers
Businesses frequently purchase products and services from suppliers established outside the UAE. If the supplier is not charging UAE VAT and the transaction falls within the UAE reverse charge rules, the recipient is generally responsible for accounting for the VAT.
Examples include:
Foreign consulting firms
International software companies
Overseas technology providers
Global digital marketing agencies
Foreign engineering consultants
International licensing providers
Precious Metals and Other Specified Transactions
The UAE VAT legislation also provides for reverse charge treatment in certain domestic transactions specified by law, including particular supplies of precious metals and other qualifying transactions where the applicable legal conditions are met.
Businesses involved in these industries should review the relevant VAT rules carefully before determining the correct VAT treatment.
When Does the Reverse Charge Mechanism Not Apply?
The reverse charge does not apply to every purchase from outside the UAE. Businesses should assess each transaction individually before applying reverse charge accounting.
It generally does not apply in the following situations:
Purchases from UAE suppliers that correctly charge UAE VAT.
Exempt supplies under UAE VAT legislation.
Transactions that fall outside the scope of UAE VAT.
Personal purchases that are not related to business activities.
Non-business expenses that do not qualify for VAT recovery.
Transactions where specific VAT rules require a different treatment.
Supplies that do not satisfy the conditions for applying the reverse charge.
Applying the reverse charge incorrectly can result in inaccurate VAT returns and unnecessary compliance risks.
How Does the UAE Reverse Charge Mechanism Work?
The Reverse Charge Mechanism follows a straightforward accounting process, but each step should be completed accurately to remain compliant with FTA requirements.
Step 1: Receive the Supplier Invoice
The overseas supplier issues an invoice without charging UAE VAT because it is not responsible for collecting UAE VAT on the transaction.
The invoice should clearly identify the supplier, describe the services or goods supplied, and include the transaction value.
Step 2: Determine Whether Reverse Charge Applies
Before recording the transaction, the business should confirm:
The supplier is located outside the UAE.
The transaction falls within the UAE reverse charge rules.
The business is VAT registered.
The purchase relates to taxable business activities.
The applicable VAT treatment has been reviewed.
This assessment helps ensure the transaction is recorded correctly from the outset.
Step 3: Calculate the VAT
If the reverse charge applies, the business calculates VAT using the applicable UAE VAT rate based on the taxable value of the supply.
The calculated amount is treated as output VAT for reporting purposes.
Step 4: Record Output VAT and Input VAT
The business records:
Output VAT payable under the reverse charge.
Recoverable input VAT, where the business has the right to recover VAT under UAE VAT rules.
For businesses making fully taxable supplies, the output VAT and recoverable input VAT often offset each other within the same VAT period. However, businesses making exempt or partially exempt supplies may only recover input VAT to the extent permitted under the applicable VAT recovery rules.
Step 5: Report the Transaction in the VAT Return
The transaction must be reported accurately in the relevant sections of the UAE VAT return based on FTA reporting requirements. Incorrect reporting may lead to discrepancies during VAT reviews or audits, making proper bookkeeping and recordkeeping an essential part of ongoing VAT compliance.
Accounting Entries for Reverse Charge Transactions
Accurate accounting entries are essential when applying the UAE Reverse Charge Mechanism. Since the overseas supplier does not charge UAE VAT, the VAT-registered business must record both the output VAT and, where eligible, the recoverable input VAT in its accounting records.
The journal entries depend on the nature of the transaction, but the accounting principle remains the same. Businesses should ensure that all entries are supported by supplier invoices, contracts, and other relevant documents.
Example 1: Imported Consultancy Services
A UAE VAT-registered company receives management consultancy services from an overseas supplier.
Invoice Value: AED 20,000
VAT Rate: 5%
VAT Amount: AED 1,000
Journal Entry
Account
Debit (AED)
Credit (AED)
Consultancy Expense
20,000
Input VAT Recoverable
1,000
Accounts Payable
20,000
Output VAT Payable
1,000
If the consultancy service is used solely for taxable business activities, the business may generally recover the input VAT subject to the UAE VAT recovery rules.
Example 2: Imported Software Subscription
A UAE company purchases an annual cloud-based accounting software subscription from a foreign supplier.
Invoice Value: AED 12,000
VAT Rate: 5%
VAT Amount: AED 600
Journal Entry
Account
Debit (AED)
Credit (AED)
Software Subscription Expense
12,000
Input VAT Recoverable
600
Accounts Payable
12,000
Output VAT Payable
600
Businesses should retain the supplier agreement and invoice as evidence supporting the VAT treatment.
Example 3: Imported Goods
A manufacturing company imports machinery from an overseas supplier for business operations.
Invoice Value: AED 100,000
VAT Rate: 5%
VAT Amount: AED 5,000
Journal Entry
Account
Debit (AED)
Credit (AED)
Machinery
100,000
Input VAT Recoverable
5,000
Accounts Payable
100,000
Output VAT Payable
5,000
The VAT treatment for imported goods should also be reconciled with customs documentation where applicable to ensure accurate accounting and VAT reporting.
VAT Return Reporting for Reverse Charge Transactions
Recording the accounting entry alone is not sufficient. Businesses must also report reverse charge transactions correctly in their UAE VAT return.
Incorrect VAT return reporting may result in errors, delayed VAT assessments, or administrative penalties. Finance teams should reconcile accounting records with VAT return figures before submission.
Taxable Supplies Subject to Reverse Charge
The taxable value of supplies subject to the reverse charge should be reported in the relevant section of the UAE VAT return designated for reverse charge transactions.
Businesses should ensure that:
The taxable value is reported accurately.
The applicable VAT is calculated correctly.
The transaction is included in the correct tax period.
Output VAT
The VAT calculated under the Reverse Charge Mechanism must be reported as output VAT in the appropriate section of the VAT return.
Businesses should verify that:
The VAT amount matches the accounting records.
Exchange rates are applied correctly where foreign currency invoices are involved.
Duplicate reporting is avoided.
Recoverable Input VAT
Where the business is entitled to recover VAT, the same VAT amount may generally be claimed as recoverable input tax, subject to the normal recovery conditions.
Input VAT recovery depends on factors such as:
The purchase relates to taxable business activities.
The business holds adequate supporting documents.
No blocked input tax provisions apply.
Recovery complies with UAE VAT legislation.
Reconciliation Before Filing
Before submitting the VAT return, businesses should reconcile:
Purchase ledger
General ledger
VAT control accounts
Supplier invoices
Import documentation
Accounting journals
VAT return figures
Regular reconciliations reduce the risk of reporting errors and improve audit readiness.
Example of Reverse Charge VAT Calculation
The following example illustrates how reverse charge VAT is calculated.
Scenario
A UAE VAT-registered business purchases digital marketing services from a supplier established outside the UAE.
Invoice Value: AED 20,000
Applicable VAT Rate: 5%
Description
Amount (AED)
Service Value
20,000
Output VAT (5%)
1,000
Recoverable Input VAT
1,000
Net VAT Payable
0*
*The net VAT impact may be nil where the business is fully entitled to recover the input VAT. Businesses making exempt or partially exempt supplies may not be able to recover the full amount.
This example demonstrates that the Reverse Charge Mechanism is primarily an accounting and reporting requirement rather than an additional VAT cost for businesses with full input tax recovery rights.
Documents Required for Reverse Charge Compliance
Maintaining complete documentation is essential for demonstrating compliance with UAE VAT requirements. Businesses should keep records for the retention period required under applicable UAE tax legislation.
The following documents should be maintained:
Overseas supplier invoice.
Purchase order.
Signed contract or service agreement.
Import documentation, where applicable.
Customs documents for imported goods.
Shipping documents.
Payment confirmation.
Bank transfer records.
Accounting journal entries.
General ledger records.
VAT calculation worksheets.
Exchange rate calculations for foreign currency transactions.
VAT return working papers.
Correspondence supporting the transaction, where relevant.
Complete documentation helps support the VAT treatment during FTA reviews or audits.
Common Reverse Charge VAT Mistakes Businesses Make
Many VAT errors arise because businesses overlook reverse charge obligations or apply the rules incorrectly. Identifying these issues early helps reduce compliance risks.
Common mistakes include:
Failing to identify imported services that are subject to the Reverse Charge Mechanism.
Recording supplier invoices without calculating reverse charge VAT.
Claiming input VAT without meeting the eligibility requirements.
Reporting transactions in the wrong VAT return period.
Using incorrect taxable values.
Applying incorrect exchange rates to foreign currency invoices.
Recording incomplete accounting entries.
Omitting reverse charge transactions from the VAT return.
Failing to reconcile accounting records with VAT return figures.
Misclassifying business and non-business expenses.
Not reviewing updates to UAE VAT legislation and FTA guidance.
Relying on manual calculations without adequate review procedures.
Implementing strong accounting controls and periodic VAT reviews can significantly reduce the likelihood of reporting errors and improve overall compliance with UAE VAT requirements.
How the Reverse Charge Mechanism Impacts Cash Flow
The UAE Reverse Charge Mechanism can improve cash flow for businesses that are fully entitled to recover input VAT. Instead of paying UAE VAT to an overseas supplier, the business accounts for both output VAT and recoverable input VAT through its VAT return.
For many fully taxable businesses, this means there is no immediate cash outflow relating to VAT on qualifying reverse charge transactions. However, the accounting and reporting obligations remain significant, and inaccurate reporting can result in penalties.
Businesses should regularly review reverse charge transactions to ensure:
VAT is calculated correctly.
Accounting records are accurate.
Input VAT recovery conditions are satisfied.
Transactions are reported in the correct tax period.
Supporting documents are complete.
Reverse Charge vs Standard VAT in the UAE
Feature
Reverse Charge Mechanism
Standard VAT
Supplier Location
Outside the UAE or qualifying specified transactions
UAE VAT-registered supplier
Who Accounts for VAT
UAE recipient
Supplier
VAT on Invoice
No UAE VAT charged by overseas supplier
UAE VAT charged on the invoice
Output VAT
Recorded by the recipient
Collected and reported by the supplier
Input VAT Recovery
Subject to eligibility under UAE VAT rules
Subject to eligibility under UAE VAT rules
Accounting Responsibility
Recipient
Supplier
VAT Return Reporting
Reported by the recipient
VAT recovered from supplier invoice
Compliance Responsibility
Higher for the recipient
Shared between supplier and recipient
Understanding these differences helps businesses apply the correct VAT treatment and avoid reporting errors.
Best Practices for Reverse Charge VAT Compliance
Businesses should establish clear internal procedures for reviewing overseas purchases and recording VAT accurately.
Recommended best practices include:
Verify whether the supplier is established outside the UAE.
Review every overseas invoice before processing payment.
Confirm whether the Reverse Charge Mechanism applies.
Calculate VAT using the applicable UAE VAT rate.
Record output VAT and recoverable input VAT correctly.
Reconcile VAT accounts before filing each VAT return.
Maintain complete supporting documentation.
Monitor transactions involving imported services and imported goods.
Use reliable accounting software with VAT reporting capabilities.
Conduct periodic internal VAT reviews.
Train finance and accounting teams on UAE VAT requirements.
Keep up to date with guidance issued by the Federal Tax Authority (FTA).
Seek professional advice for complex or high-value cross-border transactions.
Following these practices reduces compliance risks and supports accurate VAT reporting.
FAQ
What is the UAE Reverse Charge Mechanism?
The Reverse Charge Mechanism is a VAT rule that transfers the responsibility for accounting for VAT from the supplier to the VAT-registered recipient in qualifying transactions.
Who must apply the Reverse Charge Mechanism?
It generally applies to VAT-registered businesses in the UAE that receive qualifying goods or services from overseas suppliers or enter into other transactions specified under UAE VAT legislation.
Does the reverse charge apply to imported services?
Yes. Many imported business services, such as consultancy, software subscriptions, cloud services, digital advertising, and professional services supplied by overseas providers, may fall within the Reverse Charge Mechanism, depending on the facts of the transaction.
Can businesses recover input VAT under the reverse charge?
Businesses may recover input VAT if the purchase is used for taxable business activities and the recovery conditions under the UAE VAT legislation are satisfied.
How should reverse charge transactions be reported?
Businesses should report qualifying reverse charge transactions in the appropriate sections of the UAE VAT return and maintain supporting accounting records and documentation.
What documents should businesses retain?
Businesses should keep:
Supplier invoices
Contracts and agreements
Import and customs documents where applicable
Payment records
Accounting journals
VAT calculations
VAT return working papers
Bank transfer confirmations
What happens if reverse charge VAT is reported incorrectly?
Incorrect reporting may lead to VAT adjustments, administrative penalties, additional tax assessments, or increased scrutiny during an FTA review or audit.
Why Choose Ripple Accountants for UAE VAT Compliance and Accounting
Managing reverse charge transactions requires more than recording accounting entries. Businesses must ensure that every qualifying transaction is assessed correctly, reported accurately, and supported by complete documentation. A proactive approach helps reduce compliance risks and prepares businesses for future VAT reviews or audits.
Ripple Accountants provides practical support for businesses across the UAE through:
VAT registration and deregistration assistance.
VAT return preparation and review.
Reverse charge VAT assessments.
Accounting and bookkeeping services.
Input VAT recovery reviews.
VAT health checks and compliance reviews.
Corporate tax and VAT advisory.
Audit-ready financial record preparation.
Ongoing accounting support for SMEs, mainland companies, and free zone businesses.
Whether your business regularly imports services, purchases software from overseas providers, or manages international supplier relationships, professional VAT support can help ensure accurate reporting and compliance with UAE tax requirements.
If you need assistance with UAE VAT compliance, reverse charge accounting, or bookkeeping, Ripple Accountants can help you establish reliable accounting processes and meet your VAT obligations with confidence.
The UAE Reverse Charge Mechanism is an essential component of the country’s VAT system and plays a significant role in the taxation of imported goods and services. Businesses that purchase from overseas suppliers must understand when the reverse charge applies, how to record the correct accounting entries, and how to report transactions accurately in their VAT returns.
Disclaimer: This article is for general informational purposes only and does not constitute legal, tax, or financial advice. UAE VAT laws and Federal Tax Authority (FTA) guidance may change over time. Businesses should consult a qualified VAT professional or tax advisor for advice specific to their circumstances.
Share
Free Consultation
Have a tax or accounting question?
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
0 Comments
No comments yet. Be the first to start the conversation.
Is your construction project still profitable after you account for actual spending, outstanding purchase orders, subcontractor commitments, and the cost of completing…
Could your business explain every employee’s salary payment, deduction, overtime amount, and leave adjustment if an employee or regulator asked for proof?…
0 Comments