UAE Corporate Tax Return Filing 2026: Deadlines, Requirements & Process
M Maria October 15, 2026 14 min read
Is your UAE Corporate Tax return filing deadline approaching, and are you sure your business is ready to file without errors or penalties?
UAE Corporate Tax return filing is an essential compliance requirement for most businesses subject to Corporate Tax. Companies must report their financial information, calculate taxable income and submit the required return to the Federal Tax Authority (FTA) within the prescribed deadline. Whether you operate a Mainland company, a Free Zone business or work independently, timely and accurate filing is important for avoiding penalties and maintaining compliance.
In this guide, you’ll learn who must file a Corporate Tax return, the applicable deadlines, required documents, step-by-step filing process and penalties, along with how Ripple Accountants can simplify the process for you.
What Is Corporate Tax Return Filing in the UAE?
UAE Corporate Tax return filing is the process of declaring a business’s taxable income, applicable tax adjustments and Corporate Tax liability to the FTA for a specific tax period.
Corporate Tax applies to financial years beginning on or after 1 June 2023. Under the standard regime, taxable income up to AED 375,000 is subject to a 0% rate, while the portion exceeding AED 375,000 is generally taxed at 9%. Different rules may apply to certain businesses.
The Corporate Tax return allows the FTA to assess the business’s reported tax position and determine the amount payable.
A typical return may include:
Business identification and Corporate Tax Registration Number.
Relevant financial and accounting information.
Taxable income and applicable adjustments.
Eligible deductions, reliefs and tax losses.
Corporate Tax payable for the tax period.
Businesses should ensure that the return accurately reflects their financial records and applicable tax treatment.
Corporate Tax Registration vs Return Filing
Although both are Corporate Tax obligations, registration and return filing serve different purposes.
Corporate Tax Registration
Corporate Tax Return Filing
Registers a taxable person with the FTA
Reports financial and tax information for a tax period
Results in a Corporate Tax Registration Number
Determines and declares applicable tax liability
Generally completed when registration becomes required
Generally completed after the relevant tax period ends
Usually a one-time process, with updates as needed
Usually an annual obligation
Registering for Corporate Tax does not mean the business has completed its return filing obligations.
If your business is registered but has not prepared its first return, Ripple Accountants can help assess the filing requirements and organise the information needed for submission.
Who Must File a Corporate Tax Return in the UAE?
Most taxable persons registered for UAE Corporate Tax must submit a return for each applicable tax period.However, obligations can vary based on business structure, tax status and eligibility for specific reliefs.
1. Mainland Companies
UAE Mainland companies, including Limited Liability Companies (LLCs), trading businesses, consultancies and professional service firms, generally need to file Corporate Tax returns. Filing is normally required even where taxable income does not exceed AED 375,000.
For example, a consulting company with AED 300,000 in taxable income may have no Corporate Tax payable under the standard rates, but it generally must still submit its return.
2. Free Zone Companies
Free Zone companies are also generally subject to Corporate Tax return filing requirements. This includes companies operating in Free Zones such as DMCC, JAFZA, IFZA and Meydan. A business qualifying for the 0% rate as a Qualifying Free Zone Person must still meet the relevant reporting and filing obligations.
A 0% Corporate Tax rate does not automatically mean exemption from return filing.
Free Zone businesses should review their qualifying income, transactions and tax status before submission.
Ripple Accountants can assist with reviewing Free Zone financial information and preparing returns based on the relevant Corporate Tax requirements.
3. Freelancers and Individuals
Individuals conducting business activities in the UAE may be subject to Corporate Tax when their relevant annual business turnover exceeds AED 1 million. Where a natural person becomes a taxable person, the applicable Corporate Tax filing obligations must also be considered.
Salary income and specified personal investment and real estate investment income are excluded under the relevant natural-person rules.
4. Companies with No Profit or Tax Payable
A common misconception is that businesses only need to file Corporate Tax returns when they make a profit. In reality, a taxable business may still need to file even if it records a loss, earns no revenue or has no Corporate Tax payable.
For example, a newly established company may incur operating expenses without generating sales. It may still have a return filing obligation for the relevant tax period.
5. Businesses Claiming Small Business Relief
Eligible businesses can elect for Small Business Relief, subject to the applicable conditions. The general revenue threshold is AED 3 million, considering the current and relevant previous tax periods. The Ministry of Finance extended the availability of this relief to tax periods ending on or before 31 December 2029.
Eligible businesses must still submit a simplified Corporate Tax return within the applicable filing deadline.
Small Business Relief does not automatically eliminate filing requirements, and not every type of taxable person is eligible.
Not sure whether your company needs to file? Ripple Accountants can review your business structure, financial position and relief eligibility to help identify the applicable filing obligations.
UAE Corporate Tax Return Filing Deadlines
The standard UAE Corporate Tax return filing deadline is nine months after the end of the relevant tax period. Businesses must generally file their returns and pay any Corporate Tax due within this period, unless a different deadline or special provision applies.
How to Determine Your Filing Deadline
Your filing deadline depends on your company’s applicable tax period, which generally follows its financial year. For example, a company with a January-to-December financial year normally has until the end of September of the following year to submit its return.
The deadline is not necessarily the same for every UAE business.
Financial year ending
General filing deadline
31 December 2025
30 September 2026
31 March 2026
31 December 2026
30 June 2026
31 March 2027
31 December 2026
30 September 2027
These examples assume the standard nine-month deadline applies.
Important 2026 update: The FTA confirmed that taxable persons with a tax period ending on 31 December 2025 were required to file their Corporate Tax returns and settle any Corporate Tax due by 30 September 2026.
If your business missed an applicable deadline, you should review its filing status and potential penalty exposure promptly.
Should Businesses File Before the Deadline?
Yes. Preparing and submitting the return in advance helps businesses identify missing records, investigate accounting discrepancies and address technical filing issues. Waiting until the final day can create unnecessary compliance risks.
Businesses should finalise their financial records, review relevant tax adjustments and confirm the amount payable before submission.
Need help meeting your Corporate Tax filing deadline? Ripple Accountants assists UAE businesses with return preparation, financial reviews and filing support to reduce last-minute complications.
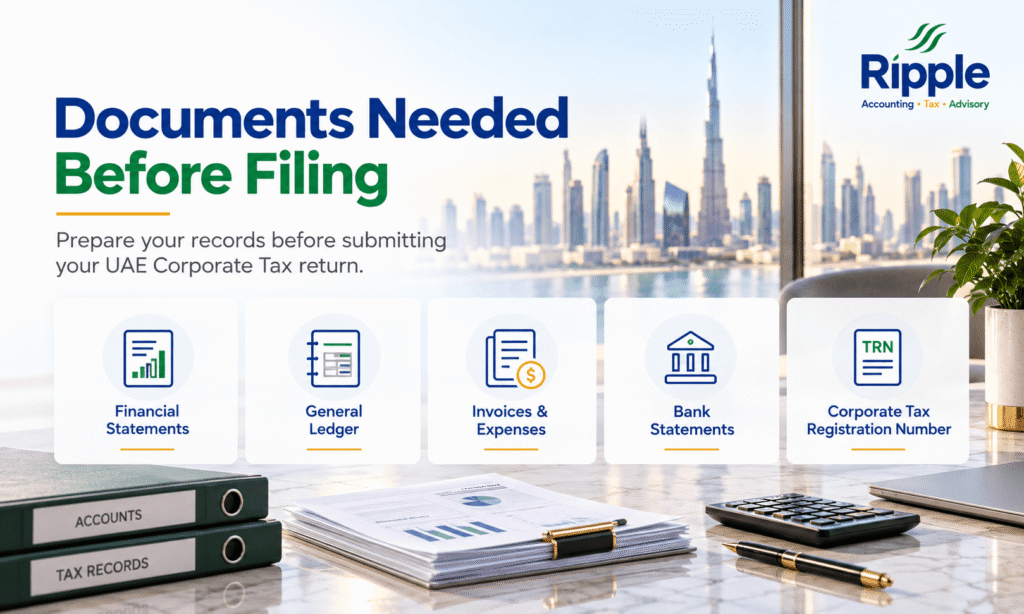
Documents Required for UAE Corporate Tax Return Filing
Accurate Corporate Tax filing begins with reliable financial records. The information required depends on the company’s activities, tax status and transactions during the relevant period.
Document or information
Why it is needed
Trade licence and business details
To confirm business information
Corporate Tax Registration Number
To identify the taxpayer
Financial statements
To establish financial performance
Profit and loss statement
To identify revenue and expenses
Balance sheet
To review assets, liabilities and equity
General ledger
To verify recorded transactions
Invoices and expense records
To support income and expense figures
Bank statements
To help reconcile financial transactions
Supporting tax schedules
To calculate adjustments, reliefs and tax liabilities
Some businesses may need additional information relating to related-party transactions, foreign income, tax losses, interest expenses or Free Zone qualifying income.
Not every document must necessarily be uploaded with the return. However, businesses should maintain the records required to support the submitted information and provide them if requested by the FTA.
Why Financial Record Accuracy Matters
Corporate Tax is calculated using taxable income, which is generally determined by adjusting accounting income according to the applicable tax rules.
For example, not every expense appearing in the profit and loss statement is automatically deductible for Corporate Tax purposes.
Businesses may need to consider non-deductible expenses, applicable reliefs and other adjustments before completing the return.
A simple accounting error can affect the final taxable-income calculation. Businesses are generally required to retain relevant Corporate Tax records for at least seven years following the end of the relevant tax period.
Ripple Accountants provides bookkeeping, financial statement preparation and Corporate Tax review services to help businesses organise their records before filing.
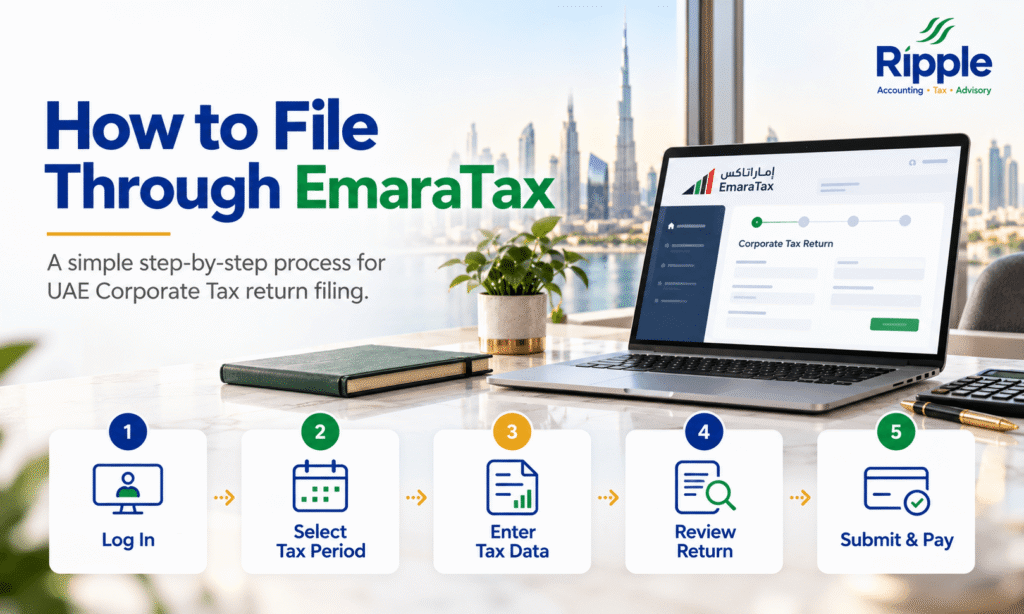
How to File a Corporate Tax Return Through EmaraTax
UAE Corporate Tax returns are submitted electronically through EmaraTax, the FTA’s official tax services platform. Businesses can complete the filing directly or obtain support from an appropriately authorised representative.
This is a simplified illustration. The actual calculation depends on the company’s taxable income and applicable provisions.
Ripple Accountants can assist with reviewing financial statements, determining relevant tax adjustments and preparing the appropriate figures for the return.
Step 5: Review and Submit the Return
Before submitting, carefully review all information entered.
Check the taxable income, relief elections, tax payable and supporting figures against the financial records.
Ensure that the return reflects the correct tax period and taxable person.
Once satisfied, submit the return through EmaraTax and retain the filing confirmation for your records.
If information is incorrect, the business may need to take corrective action under the applicable tax procedures.
Step 6: Pay Any Corporate Tax Due
Where Corporate Tax is payable, the business must settle the amount by the applicable payment deadline. The FTA provides electronic payment options through EmaraTax.
Filing a return and paying Corporate Tax are separate steps. A successfully submitted return does not necessarily mean that an outstanding tax liability has been paid.
Businesses should verify the amount due, use the available payment instructions and retain confirmation of payment. Payment should be initiated sufficiently early to allow for processing.
Want a smoother Corporate Tax filing process? Ripple Accountants supports businesses with financial reviews, tax calculations, return preparation and EmaraTax filing assistance.
UAE Corporate Tax Return Filing Penalties
Failure to submit a Corporate Tax return or pay tax within the prescribed timeframe can result in administrative penalties. Understanding these penalties helps businesses avoid unnecessary compliance costs.
1. Penalty for Late Corporate Tax Return Filing
Under the Corporate Tax administrative penalty framework, late return filing can result in:
Delay
Administrative penalty
First 12 months
AED 500 for each month or part of a month
From the 13th month onwards
AED 1,000 for each month or part of a month
For example, submitting a return two months after the deadline can result in AED 1,000 in late filing penalties under the standard monthly calculation.
The penalty can apply even where no Corporate Tax is payable.
2. Penalties for Late Corporate Tax Payment
Failure to settle Corporate Tax payable can result in an additional late-payment penalty. Under the applicable penalty framework, this is calculated at a rate equivalent to 14% per annum, imposed monthly on the unpaid amount, with a month or part of a month treated according to the prescribed rules. Late payment and late return filing are separate compliance failures.
3. Penalties for Incorrect Returns
Submitting inaccurate information may also result in penalties. The applicable consequences depend on the nature of the error, relevant legal provisions and whether the business corrects the information within the permitted timeframe. Where an error is discovered, the business should review the appropriate correction or voluntary disclosure process.
How to Avoid Corporate Tax Filing Penalties
Businesses can reduce compliance risks by:
Confirming the correct filing deadline.
Maintaining complete and accurate accounting records.
Reviewing tax adjustments and relief eligibility.
Preparing the return before the deadline.
Checking the submission confirmation.
Paying any outstanding Corporate Tax on time.
Professional preparation can help identify discrepancies before submission.
How Ripple Accountants Can Help with Corporate Tax Return Filing
Preparing a Corporate Tax return involves more than entering figures into EmaraTax. Businesses need reliable financial records, accurate tax calculations and a clear understanding of applicable filing requirements.
At Ripple Accountants, we help UAE businesses manage the Corporate Tax filing process with practical accounting and tax support.
Ongoing Corporate Tax compliance: Assisting with future filing requirements, accounting support and compliance reviews.
Whether you manage a Mainland company, operate in a UAE Free Zone or are preparing your first Corporate Tax return, our team can help you understand the requirements and complete the process.
Email: info@uaetaxcompliance.ae
Phone: +971 52 356 5409
WhatsApp: +971 4 250 0833
Frequently Asked Questions About UAE Corporate Tax Return Filing
Is Corporate Tax return filing mandatory in the UAE?
Most taxable persons subject to UAE Corporate Tax must file a return for each applicable tax period. Filing requirements generally apply even where there is no Corporate Tax payable. Certain exempt persons have different reporting obligations.
Do companies with zero profit need to file?
Yes, generally. A taxable company may still need to submit a Corporate Tax return even if it has no revenue, reports a loss or has no Corporate Tax liability.
Do Free Zone companies need to file Corporate Tax returns?
Yes. Free Zone companies generally must file Corporate Tax returns, including Qualifying Free Zone Persons benefiting from the relevant 0% tax treatment on qualifying income.
What is the UAE Corporate Tax filing deadline?
The general deadline is nine months after the end of the applicable tax period. For example, a tax period ending on 31 December 2026 would normally have a filing deadline of 30 September 2027.
Can I file my Corporate Tax return myself?
Yes. Businesses can file through EmaraTax. However, professional assistance may be useful where financial records, tax adjustments, relief elections or business structures are complex.
What happens if I miss the filing deadline?
Late return filing can result in an administrative penalty of AED 500 per month or part of a month for the first 12 months, increasing to AED 1,000 per month or part of a month thereafter. Separate penalties may apply to unpaid tax.
Can I correct a Corporate Tax return after submission?
Yes, errors may be corrected through the applicable FTA procedures, including voluntary disclosure where required. The correct method depends on the nature and significance of the error and applicable rules.
Conclusion
UAE Corporate Tax return filing is an important responsibility for businesses operating in the UAE. Understanding the filing requirements, deadlines, documents and EmaraTax submission process can help avoid errors, penalties and unnecessary delays.
Need help filing your UAE Corporate Tax return? Contact Ripple Accountants today for expert guidance and reliable Corporate Tax filing support.
Disclaimer: This article provides general information based on UAE Corporate Tax rules reviewed as of 15 October 2026. Specific filing obligations, relief eligibility and penalties depend on the taxpayer’s circumstances and applicable legislation. Consult official FTA guidance or a qualified tax professional for advice relating to your business.
Is your construction project still profitable after you account for actual spending, outstanding purchase orders, subcontractor commitments, and the cost of completing…
Could your business explain every employee’s salary payment, deduction, overtime amount, and leave adjustment if an employee or regulator asked for proof?…
0 Comments