Accounting for Leases under IFRS 16: A Complete Guide to Lease Accounting
Lease accounting has become one of the most important areas of financial reporting for businesses that rent offices, warehouses, vehicles, machinery, or…
Read article
Are your accounting records actually ready for a UAE Corporate Tax return, or are you relying on a trial balance that has not been properly reviewed?
A Corporate Tax return is only as reliable as the financial records behind it. Missing transactions, unreconciled balances, incorrectly classified expenses, or unsupported adjustments can affect the calculation of taxable income.
The Federal Tax Authority (FTA) requires Taxable Persons to maintain records and documents that support the information reported in their Corporate Tax returns and enable taxable income to be determined. These records generally need to be retained for at least seven years after the end of the relevant Tax Period.
A proper UAE Corporate tax records review before CT filing should therefore go beyond checking whether the bookkeeping software shows a completed year. The purpose is to establish whether the accounting records are complete, reconciled, supported, and suitable for the Corporate Tax computation.
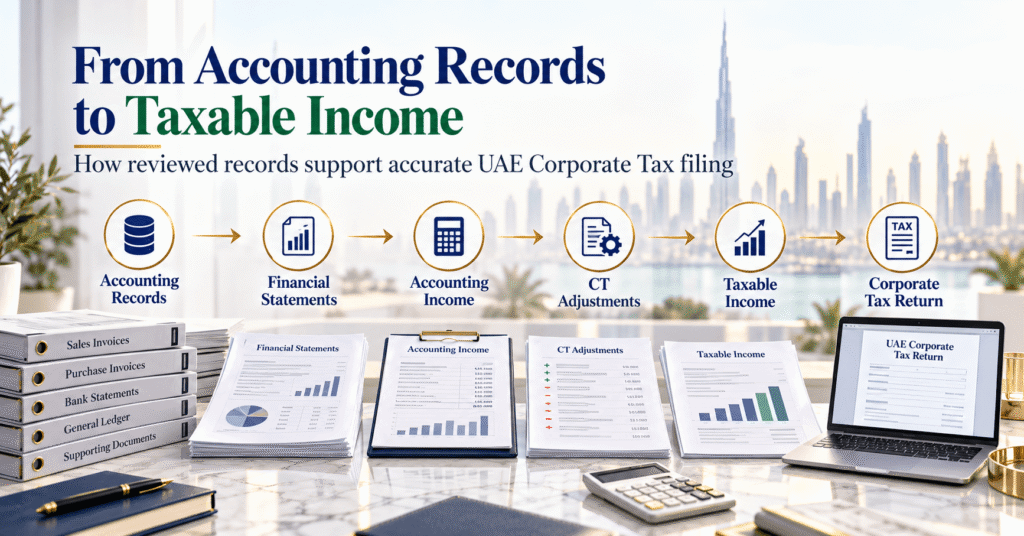
The UAE Corporate Tax calculation starts with accounting income and then applies the adjustments required under the Corporate Tax Law.
The FTA explains that taxable income is generally based on the accounting net profit or loss after adjustments for items specified under the Corporate Tax Law. These can include non-deductible expenditure, exempt income, certain related-party transactions, unrealized gains or losses where relevant, tax-loss relief, and other applicable adjustments.
This means a business should not move directly from an unreviewed trial balance to the CT return. A pre-filing records review helps identify accounting issues before they affect the tax computation.
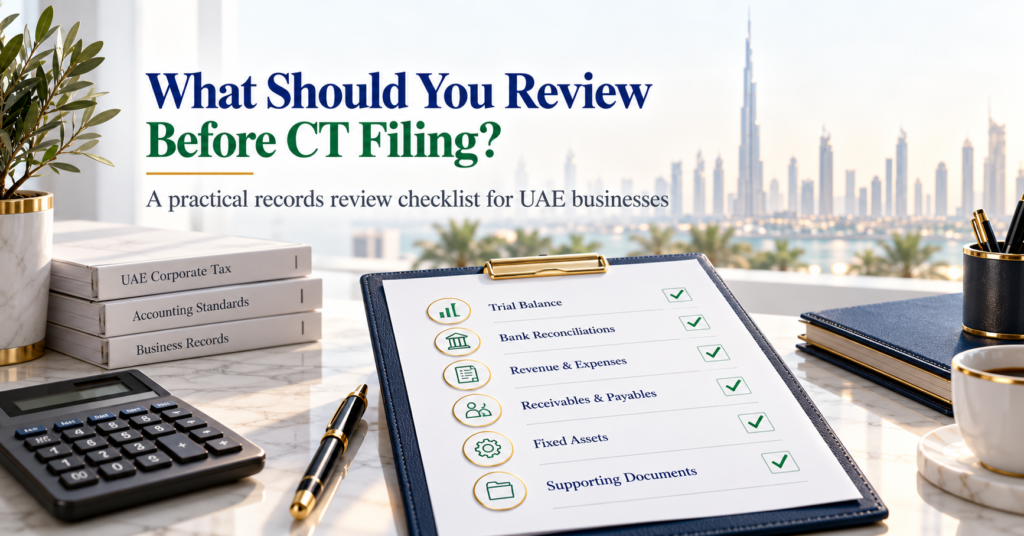
A practical review should cover the main accounting records and supporting documents for the relevant Tax Period.
The trial balance provides the starting point for reviewing the company’s accounting records.
Check whether:
A trial balance should not simply be accepted because the debits and credits balance. The individual balances should also make commercial and accounting sense.
Bank reconciliation is an important part of a trial balance review UAE businesses should complete before preparing their CT computation.
Compare the accounting records with the company’s bank statements and investigate:
A bank balance that has not been reconciled can affect both income and expenses reported in the accounts.
Review customer balances before finalizing the accounting figures.
Check:
The purpose is to confirm that revenue and receivable balances are supported by the underlying transactions.
Supplier balances should also be reviewed before the CT computation.
Look for:
This can help identify expenses that have been missed or incorrectly classified.
Revenue should be reviewed against the underlying accounting records.
Consider whether:
The FTA has specifically highlighted the importance of maintaining records of transactions during the Tax Period so that revenue and taxable income can be verified.
Not every accounting expense necessarily receives identical treatment for Corporate Tax purposes.
Review significant expense categories and identify items that may require tax adjustments.
Check areas such as:
The FTA states that legitimate business expenses incurred to derive taxable income are generally deductible, although specific rules and limitations can apply.
The accounting treatment should therefore be reviewed before deciding how an expense is treated in the CT computation.
A fixed asset review should form part of the pre-filing process.
Check the:
The FTA has identified an asset record, including details of asset purchases and disposals, as one of the essential records that Taxable Persons may need to maintain.
This makes the fixed asset register an important document when reviewing the accounts before filing.
Liability balances should also be checked.
Review:
The FTA specifically includes records of liabilities among the records that Taxable Persons should maintain.
Unusual or unsupported liability balances should be investigated rather than carried forward automatically.
Businesses should identify transactions involving related parties and Connected Persons before preparing their CT return.
Review transactions such as:
The FTA confirms that transfer pricing rules apply to UAE businesses with transactions involving Related Parties and Connected Persons, including transactions with parties in the UAE mainland, Free Zones, or foreign jurisdictions.
A records review can therefore help identify transactions that require additional consideration before filing.
Once the accounting records have been reviewed, identify the adjustments required to move from accounting income to taxable income.
The FTA describes this as a two-stage process: determine accounting income and then apply the relevant adjustments to arrive at taxable income.
Depending on the business and Tax Period, the review may need to consider:
The key point is that these adjustments should be based on reviewed accounting figures and supporting documentation.
A tax computation should be supported by appropriate accounting records.
Before filing, check whether important balances and transactions can be supported by documents such as:
The FTA has reiterated that Taxable Persons must retain documents supporting information provided in their Tax Returns.
Corporate Tax records should not simply be discarded after the return is filed.
Under Article 56 of the Corporate Tax Law, Taxable Persons must maintain relevant records and documents for seven years following the end of the Tax Period to which they relate.
This includes records that support information provided in a Tax Return and records that allow taxable income to be determined.
Businesses should therefore have a clear document-retention system before closing the Tax Period.
A year-on-year comparison can highlight unexpected accounting movements.
For example, investigate:
This does not mean that every unusual movement is incorrect. The purpose is to identify figures that require explanation or additional documentation before filing.
The records review should be completed well before the CT filing deadline.
The FTA states that Taxable Persons must generally submit their Corporate Tax return and settle the Corporate Tax due within nine months from the end of the relevant Tax Period.
For example, the FTA confirmed that businesses with a Tax Period ending 31 December 2025 were required to file and pay by 30 September 2026.
This makes an early records review particularly useful. Waiting until the filing deadline approaches can leave little time to correct bookkeeping errors or obtain missing supporting documents.
Use this checklist before finalizing the CT computation:
| Review area | Check |
|---|---|
| Trial balance | ☐ |
| Bank reconciliations | ☐ |
| Accounts receivable | ☐ |
| Accounts payable | ☐ |
| Revenue and other income | ☐ |
| Business expenses | ☐ |
| Fixed assets | ☐ |
| Liabilities and loans | ☐ |
| Related-party transactions | ☐ |
| Connected Person transactions | ☐ |
| Tax adjustments | ☐ |
| Supporting documents | ☐ |
| Tax losses and reliefs | ☐ |
| Prior-period adjustments | ☐ |
| Records retention | ☐ |
| Final CT computation review | ☐ |
Some issues may not be obvious from a basic trial balance.
Common examples include:
These issues are easier to address before the CT return is finalized rather than after filing.
A structured compliance review can provide an additional layer of checking before the Corporate Tax return is prepared.
The review can connect the accounting records with the CT requirements by examining:
The FTA’s current legislation also includes FTA Decision No. 4 of 2026, which sets out rules and requirements for maintaining information contained in accounting records and commercial books. The decision was published on 20 August 2026.
Ideally, the review should begin before the filing deadline rather than during the final days of the filing period.
A practical sequence is:
Bookkeeping completion → Account reconciliation → Trial balance review → Supporting-document review → Tax adjustment review → CT computation → Final filing review
This approach gives the business time to investigate discrepancies and correct accounting records before the Corporate Tax return is submitted.
Preparing a Corporate Tax return from incomplete or unreconciled accounting records can make the filing process more difficult.
Ripple Accounting, Tax & Advisory can help businesses review their accounting records and identify areas that may need attention before Corporate Tax filing.
For businesses that need help connecting bookkeeping records with their CT filing requirements, a compliance review can provide a structured pre-filing assessment.
Need to check whether your records are ready for Corporate Tax filing? Request a free consultation or send a WhatsApp enquiry to discuss the scope and pricing.
Businesses should review the trial balance, bank reconciliations, receivables, payables, revenue, expenses, fixed assets, liabilities, related-party transactions, supporting documents, and relevant tax adjustments before finalizing the CT computation.
Taxable Persons generally need to maintain relevant Corporate Tax records and documents for seven years following the end of the Tax Period to which they relate.
The trial balance provides the accounting figures used as the starting point for determining accounting income. Reviewing it can help identify unreconciled balances, classification issues, unusual transactions, and missing records before the tax computation is prepared.
The FTA has highlighted records such as transaction records, asset records including purchases and disposals, liability records, and records of shares or ownership interests, along with other documentation needed to support the Tax Return and taxable income.
Taxable Persons generally have up to nine months from the end of the Tax Period to file their Corporate Tax return and settle the Corporate Tax due.
A records review before CT filing UAE businesses should complete is more than a quick check of the trial balance. It involves reviewing reconciliations, income, expenses, assets, liabilities, related-party transactions, supporting documents, and potential tax adjustments. The FTA requires Taxable Persons to maintain records supporting their Tax Returns and taxable income, with relevant records generally retained for seven years. Completing this review before the CT computation gives businesses an opportunity to identify accounting gaps, resolve discrepancies, and organize supporting documentation before filing.
Disclaimer: This article provides general information about UAE Corporate Tax record reviews and should not be treated as tax, accounting, or legal advice. Corporate Tax treatment can vary depending on the business, transactions, accounting method, and applicable legislation. Businesses should verify the current UAE requirements and obtain professional advice where appropriate.
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
 Compliance
Lease accounting has become one of the most important areas of financial reporting for businesses that rent offices, warehouses, vehicles, machinery, or…
Read articlePage 58 of 58
Book a free consultation and get clear answers for your business.
0 Comments