Key Differences Between Bookkeepers and Accountants: Complete Business Guide
Managing business finances is one of the most important responsibilities for any business owner. Whether you run a startup, a small business,…
Read article
How do you turn your company’s accounting profit into the amount of income that is actually subject to UAE Corporate Tax?
Understanding UAE Corporate Tax calculation starts with one important point: Corporate Tax is not simply applied to a company’s total revenue or automatically to the profit shown in its accounts. The calculation generally starts with accounting income and then applies the adjustments required under the UAE Corporate Tax Law to arrive at Taxable Income. For most businesses, this means reviewing exempt income, deductible and non-deductible expenses, tax losses and other relevant adjustments before applying the applicable Corporate Tax rate.
Let’s look at the calculation step by step.
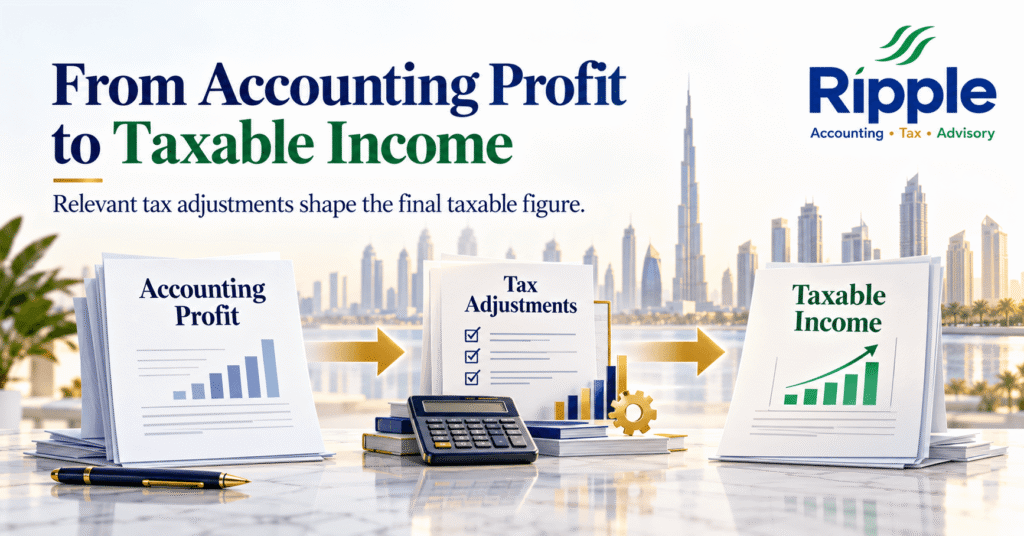
Taxable Income is the amount on which Corporate Tax is calculated for a Tax Period. The Federal Tax Authority explains that the starting point is generally the accounting net profit or loss before tax shown in the financial statements. Businesses then make the required tax adjustments to arrive at Taxable Income. These adjustments can include items such as exempt income and expenditure that is not deductible for Corporate Tax purposes.
A simplified calculation can be shown as:
Accounting Income + Tax Adjustments − Exempt Income − Allowable Deductions − Eligible Tax Loss Relief = Taxable Income
The actual calculation can be more detailed depending on the business, its transactions and the applicable Corporate Tax rules.
One of the most important concepts for business owners and finance teams is the difference between accounting profit and taxable income UAE businesses use for Corporate Tax.
Accounting profit is prepared under the applicable accounting standards and reflects the company’s financial performance.
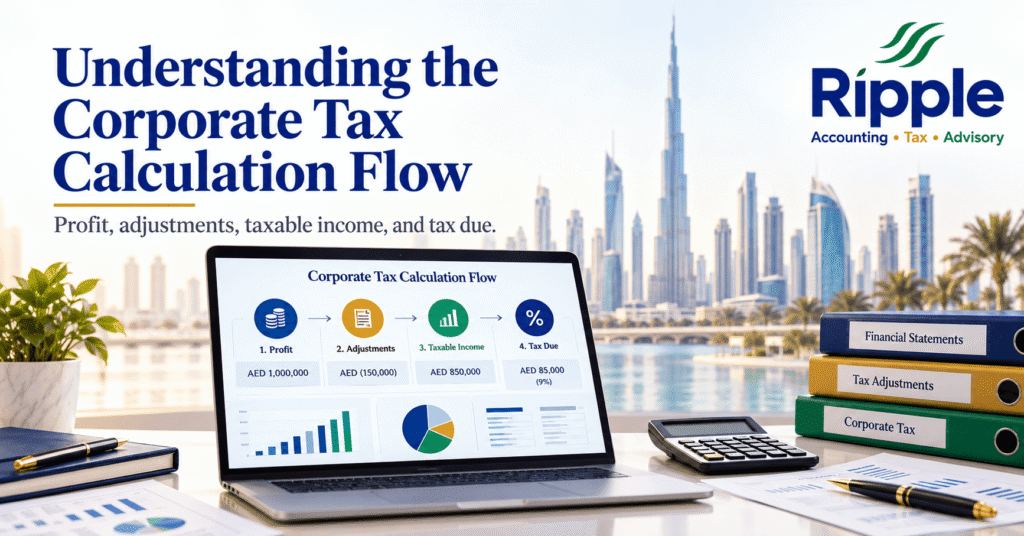
Taxable Income is determined after applying the Corporate Tax rules to that accounting result. For example, assume a UAE company has:
It may be tempting to simply calculate 9% on AED 500,000.
However, the company must first determine whether all of the expenses are deductible for Corporate Tax purposes and whether any income or other adjustments need to be considered.
If AED 50,000 of the accounting expenses is not deductible, the calculation could become:
The Corporate Tax would then be calculated on the resulting Taxable Income, subject to the applicable rules.
This is why accounting profit and Taxable Income should not automatically be treated as the same amount.
For a standard taxable person, the current UAE Corporate Tax structure applies:
The AED 375,000 threshold is applied to Taxable Income for the relevant Tax Period.
The calculation is therefore progressive across these two portions rather than applying 9% to the entire Taxable Income once the threshold is exceeded.
Example: Taxable Income of AED 300,000
Suppose a company has Taxable Income of AED 300,000.
The calculation is:
AED 300,000 × 0% = AED 0
Therefore, the Corporate Tax liability before considering any applicable tax credits or other relevant matters would be AED 0.
Example: Taxable Income of AED 500,000
Suppose another company has Taxable Income of AED 500,000.
The first AED 375,000 is subject to 0%.
The remaining AED 125,000 is subject to 9%.
The FTA provides a similar calculation example for taxable income of AED 1 million, where only the amount exceeding AED 375,000 is subject to the 9% rate.
The first step is to establish the company’s accounting income for the relevant Tax Period. For Corporate Tax purposes, accounting income generally means the accounting net profit or loss before tax as reflected in the financial statements.
This makes accurate bookkeeping and financial reporting important parts of the Corporate Tax process. Businesses should therefore ensure that:
A weak accounting base can make the subsequent tax computation more difficult.
Not every amount appearing in accounting income necessarily remains taxable under the Corporate Tax rules. Certain types of income may qualify for exemption if the relevant conditions are met.
For example, the UAE Corporate Tax framework contains rules concerning exempt income, including certain dividends and participation interests, as well as certain foreign permanent establishment income where the applicable requirements are satisfied.
This means the finance team should identify potentially exempt income before finalising the Taxable Income calculation. The treatment should not be assumed simply because an amount has been recorded as income in the financial statements.
Businesses generally need to review their expenses to determine whether they can be deducted for Corporate Tax purposes. The FTA’s guidance covers different categories of expenditure, including expenditure incurred wholly and exclusively for the purposes of the business, capital expenditure, expenditure relating to exempt income, non-deductible expenses and entertainment expenditure.
Some expenses may therefore require an adjustment to accounting profit.
A common example is business entertainment. Under the Corporate Tax Law, generally 50% of qualifying entertainment, amusement or recreation expenditure incurred for customers, shareholders, suppliers or other business partners is deductible.
For example, if qualifying entertainment expenditure is AED 20,000:
The non-deductible portion would generally be added back when determining Taxable Income.
Certain fines and penalties are also non-deductible for Corporate Tax purposes, subject to the specific provisions of the law. Other categories of expenditure, such as certain donations, gifts and illicit payments, may also require tax adjustments.
This is why a company should not simply take the expense total from its profit and loss account and assume that every item is deductible.
Some businesses may need to make additional adjustments for financing costs and interest expenditure. The Corporate Tax framework includes a General Interest Deduction Limitation Rule, subject to its conditions and exceptions. The FTA’s Determination of Taxable Income guide provides detailed guidance on net interest expenditure, adjusted EBITDA and the relevant limitation rules.
The rules can become particularly relevant for businesses with significant borrowing or financing arrangements. Finance teams should therefore identify interest-related adjustments separately rather than treating all finance costs as automatically deductible.
A company that has a Tax Loss may, subject to the applicable conditions, carry it forward and use it to reduce Taxable Income in future Tax Periods.
However, the amount of Taxable Income that can generally be reduced through carried-forward Tax Losses is limited to 75% of the Taxable Income for the relevant period.
For example, assume a company has:
The maximum amount that can generally be used against AED 1,000,000 of Taxable Income is:
The resulting Taxable Income would therefore be:
The remaining unused Tax Loss may be carried forward, subject to the applicable conditions. Tax-loss rules can therefore materially affect the final Corporate Tax calculation.
Consider a UAE company with the following figures for a Tax Period:
| Item | Amount |
| Accounting profit before tax | AED 800,000 |
| Non-deductible expenditure | AED 40,000 |
| Exempt income adjustment | AED 20,000 |
| Eligible Tax Loss used | AED 100,000 |
The calculation could be presented as:
Corporate Tax:
This is a simplified illustration. The actual calculation depends on the company’s financial statements, transactions, applicable deductions, exemptions, Tax Losses and other provisions.
Free Zone businesses should not automatically assume that all of their Taxable Income will be taxed at 0%.
The UAE Corporate Tax framework applies to Free Zone Persons as well. A Qualifying Free Zone Person may benefit from a 0% rate on Qualifying Income, while Taxable Income that does not qualify for the 0% treatment can be subject to the applicable 9% rate.
Therefore, Free Zone businesses need to assess whether they meet the conditions for Qualifying Free Zone Person status and whether particular income falls within the relevant qualifying treatment.
The calculation can consequently be different from the standard calculation for other taxable persons.
Corporate Tax calculation begins with accounting income, so the quality of the underlying accounting records can directly affect the tax computation.
Businesses should consider reviewing:
Sales, service income, other operating income and relevant adjustments should be properly recorded and supported.
Expenses should be classified correctly and supported by invoices, contracts, payment records and other relevant documentation.
Bank balances should be reconciled with the accounting records so that missing or duplicated transactions do not distort the financial results.
Capital expenditure should be separately identified from ordinary operating expenses and treated according to the applicable Corporate Tax and accounting rules.
Transactions involving related parties and connected persons may require additional consideration under the Corporate Tax framework.
The finance team should maintain a clear reconciliation between accounting profit and Taxable Income rather than calculating the tax amount without documenting the adjustments.
Businesses may encounter avoidable errors when they treat Corporate Tax as a simple 9% calculation.
Common issues include:
A structured tax computation can help finance teams identify these issues before the Corporate Tax return is submitted.
Before finalising a Corporate Tax calculation, businesses can review the following:
A Corporate Tax calculation should not be treated as a last-minute exercise before filing. Ideally, businesses should review their accounting records throughout the year so that potential tax adjustments can be identified early.
Monthly bookkeeping and reconciliations can make the year-end Corporate Tax process more manageable. A pre-filing review can then focus on the specific adjustments, exemptions, deductions and Tax Losses that apply to the business.
This approach can also help management understand why the accounting profit differs from the final Taxable Income.
Ripple Accounting, Tax & Advisory can support businesses with Corporate Tax-related accounting and compliance requirements.
Depending on the business’s needs, relevant support can include:
Need help reviewing your Corporate Tax calculation? Contact Ripple Accounting, Tax & Advisory for a tailored review of your accounting records, Taxable Income and Corporate Tax compliance requirements!
UAE Corporate Tax is generally calculated by first determining Taxable Income from accounting income after applying the relevant tax adjustments. For a standard taxable person, 0% applies to the portion up to AED 375,000 and 9% applies to the portion exceeding AED 375,000, subject to the applicable rules.
Not necessarily. Accounting profit is generally the starting point, but businesses may need to make adjustments for exempt income, non-deductible expenditure, interest limitations, Tax Losses and other applicable Corporate Tax rules before arriving at Taxable Income.
For a standard taxable person, the current rates are 0% on the portion of Taxable Income up to AED 375,000 and 9% on the portion exceeding AED 375,000. Qualifying Free Zone Persons are subject to specific rules for Qualifying Income and other Taxable Income.
Subject to the applicable conditions, Tax Losses can generally be carried forward and used to reduce Taxable Income in future Tax Periods. The amount used is generally limited to 75% of the relevant Taxable Income.
No. A Free Zone company must meet the relevant conditions to be treated as a Qualifying Free Zone Person and benefit from the 0% rate on Qualifying Income. Income that does not qualify for the relevant 0% treatment may be subject to the applicable Corporate Tax rate.
UAE Corporate Tax calculation generally starts with accounting income and then applies the adjustments required under the Corporate Tax rules to arrive at Taxable Income. The applicable 0% and 9% rates are then applied to the relevant portions of that Taxable Income. For businesses, the key is to maintain accurate accounting records and understand which income and expenses require tax adjustments. A documented reconciliation between accounting profit and Taxable Income can make the Corporate Tax process clearer and easier to review.
Disclaimer: This article provides general information about UAE Corporate Tax calculation and is not tax, legal or accounting advice for a specific business. Corporate Tax treatment can vary depending on the taxpayer’s activities, transactions, accounting policies, Free Zone status and applicable legislation. Businesses should review the current UAE Corporate Tax Law, Cabinet and Ministerial Decisions and relevant FTA guidance or obtain professional advice before making tax decisions.
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
 Bookkeeping
Managing business finances is one of the most important responsibilities for any business owner. Whether you run a startup, a small business,…
Read article Bookkeeping
Businesses no longer have the luxury of waiting until the end of the month to understand their financial performance. Markets change quickly,…
Read article Bookkeeping
The education sector in the UAE has experienced remarkable growth over the past decade. From private schools and universities to vocational training…
Read articlePage 56 of 58
Book a free consultation and get clear answers for your business.
0 Comments