Segregation of Duties in UAE SME: Low-Cost Accounting Controls
M Maria August 21, 2026 11 min read
Can a small UAE business really maintain strong financial controls without hiring a large finance team?
For many SMEs, the finance team may consist of only two or three people. One employee may record invoices, prepare payments, manage suppliers, and even perform bank reconciliations. While this approach may save time and money, it can also create a significant control weakness.
This is where segregation of duties in UAE SME becomes important. It means dividing key financial responsibilities so that one person does not control an entire transaction from beginning to end.
What Is Segregation of Duties?
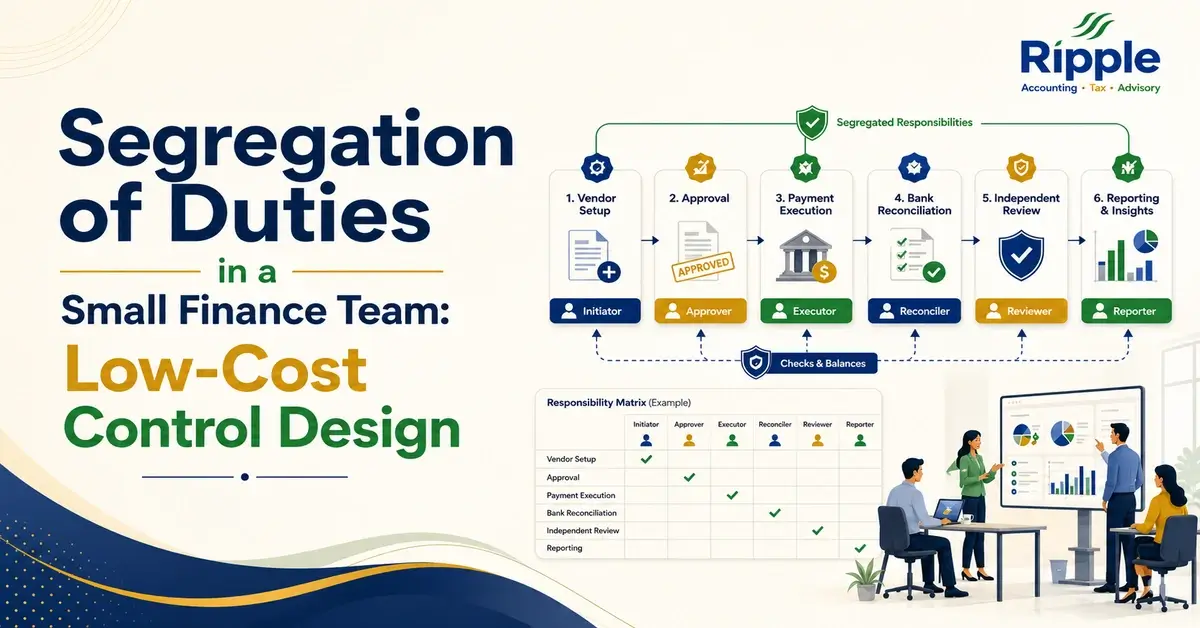
Segregation of duties is an internal control principle that divides important financial responsibilities among different people. In simple terms, the person who creates a transaction should not normally be the same person who approves, processes, and reconciles it. For example, consider a supplier payment:
Ideally, these steps should not all be controlled by one individual.
The purpose is to reduce the risk of:
Fraud
Unauthorized payments
Accounting errors
Duplicate transactions
Manipulation of financial records
Unapproved changes to supplier or customer information
The COSO Internal Control—Integrated Framework recognizes internal controls as an important part of reliable information, effective operations, and organizational integrity.
However, segregation of duties is not the same as simply having multiple employees. The important question is whether incompatible responsibilities are separated.
Why Segregation of Duties in UAE SME Matters
Small businesses often operate with limited staff and resources. This makes it difficult to create the same level of separation found in large organizations. A single finance employee may be responsible for:
Recording transactions
Preparing supplier payments
Managing customer receipts
Updating vendor details
Processing payroll
Preparing reconciliations
Posting journal entries
This creates a situation where mistakes or unauthorized transactions may go unnoticed.
The Association of Certified Fraud Examiners (ACFE) has specifically highlighted the vulnerability of small organizations where limited staffing creates fewer checks and balances. Its 2024 Report to the Nations also shows that smaller organizations generally have fewer anti-fraud controls than larger organizations.
For UAE businesses, reliable accounting controls also support proper financial recordkeeping. The UAE Federal Tax Authority expects taxable persons to maintain records and documents supporting information reported in corporate tax returns.
For VAT-registered businesses, maintaining a clear audit trail is also important. FTA guidance states that records should allow VAT amounts to be traced from source documents through to the tax return.
Therefore, SoD is not simply an accounting theory. It can form part of a broader financial control environment that supports accurate records and better business governance.
The Biggest SoD Challenge in a Small Finance Team
The main challenge is simple: there may not be enough people to separate every task.
Imagine a UAE company with only:
One accountant: The accountant records invoices and prepares payment batches
One accounts assistant: The assistant manages customer receipts and performs bookkeeping tasks
One business owner: the owner approves payments.
This may not provide perfect segregation, but it can still create meaningful checks. The objective for a small business should not be to copy the structure of a multinational company. Instead, the objective should be
Separate the highest-risk duties and introduce independent checks where complete separation is impossible.
This approach makes SoD practical for SMEs.
Key Duties That Should Be Separated
Not every accounting task carries the same level of risk. Small businesses should focus first on activities involving money, assets, financial reporting, and sensitive system access.
1. Vendor Setup and Payment
The person who creates or changes supplier details should ideally not be the person who approves the supplier payment.
For example:
Employee A: Requests and enters vendor information Employee B: Reviews vendor details Owner/Manager: Approves significant payments
This can reduce the risk of fictitious vendors or unauthorized bank account changes.
2. Invoice Processing and Payment Approval
The person entering an invoice should not normally have unrestricted authority to approve and release its payment.
A simple arrangement could be:
Accounts Assistant → Enters invoice
Accountant → Checks supporting documents
Manager/Owner → Approves payment
This creates an additional review without requiring another full-time employee.
3. Bank Reconciliation and Payment Processing
Bank reconciliation is an important control because it compares accounting records with actual bank activity. Ideally, the person processing payments should not be the only person reconciling the bank account. If staffing makes this impossible, an owner, manager, or external accountant can perform an independent review.
ACFE guidance for small businesses specifically recommends that someone who does not handle deposits or payments perform the monthly bank reconciliation, with an independent contractor being an option where staffing is limited.
4. Payroll Preparation and Approval
Payroll should also receive appropriate separation.
For example:
HR/Admin: Maintains employee information
Accountant: Prepares payroll
Manager/Owner: Reviews and approves payroll
Bank/Payroll platform: Processes payment
This reduces the opportunity for unauthorized employees, altered salaries, or unsupported payroll adjustments.
Low-Cost Accounting Controls for Small UAE Teams
Complete SoD may not be possible for every SME. Fortunately, several practical controls can provide additional protection without significant expense.
1. Create a Simple Approval Matrix
An approval matrix defines who can approve specific financial activities. For example:
Transaction
Finance Team
Manager
Owner
Routine expense
Prepare
Review
—
Supplier payment
Prepare
Approve
—
High-value payment
Prepare
Review
Approve
New vendor
Enter
Review
Approve
Refund
Prepare
Approve
—
Major contract
Review
Recommend
Approve
The exact thresholds should be based on the company’s size and risk profile. For example, an SME could decide that payments above AED 10,000 require owner approval.
The important point is to document the rules rather than rely on verbal instructions.
2. Use Dual Approval for High-Risk Transactions
A dual-approval control means two authorized people must approve an important transaction. This can be particularly useful for:
Large bank transfers
New vendors
Changes to supplier bank details
Refunds
Payroll changes
Significant journal entries
For a two-person finance team, the second approver could be the business owner or senior manager. This is often much cheaper than hiring another accountant.
3. Rotate Certain Responsibilities
Small businesses can periodically rotate selected finance duties.
For example:
Month 1: Accountant A performs reconciliation.
Month 2: Accountant B performs reconciliation.
The change gives another employee an opportunity to notice unusual transactions or inconsistencies. Job rotation is not a substitute for permanent separation where stronger controls are necessary, but it can provide an additional layer of review.
4. Introduce Independent Reviews
When two people cannot perform every step separately, an independent review can act as a compensating control. For example, if the same accountant must process payments and prepare the bank reconciliation, the owner can review:
Bank statements
Payment listings
Reconciliation reports
Unusual transactions
Large or unusual suppliers
The review should be documented rather than being a simple verbal conversation. Small businesses can also use an external accountant periodically to review important financial processes.
ACFE notes that small businesses can use basic controls such as segregation of duties, restricted system access, and independent reconciliations without creating an unnecessarily expensive control environment.
Use Accounting Software to Strengthen Segregation of Duties
Technology can help small teams implement accounting segregation of duties without increasing headcount.
Most modern accounting systems allow businesses to assign different permissions to different users. For example:
Accounts Assistant
Enter invoices
Upload documents
View relevant records
Accountant
Post accounting entries
Prepare reconciliations
Prepare payment batches
Manager/Owner
Approve payments
Review reports
Access sensitive financial information
Avoid giving every finance employee administrator-level access simply because it is convenient. Access should match job responsibilities.
Businesses should also periodically review user permissions, particularly when employees change roles or leave the organization.
Use Checklists for High-Risk Processes
A checklist is one of the simplest low-cost accounting controls for SMEs.
1. Vendor Setup Checklist
Before adding a supplier, confirm:
Supplier name
Trade license or registration details where appropriate
Contact information
Bank details
Supporting contract or purchase documentation
Approval from an authorized person
Duplicate-vendor check
The person entering the vendor should not be the only person verifying the information.
2. Payment Checklist
Before releasing a payment, confirm:
Invoice is available
Purchase or service is legitimate
Amount is correct
Supporting documents are attached
Required approvals are complete
Supplier bank details are verified
Payment is not duplicated
3. Journal Entry Checklist
For manual journal entries, review:
Reason for the entry
Supporting documentation
Correct accounts
Correct amount
Date and accounting period
Appropriate approval
Reviewer independent from the preparer
These simple checklists create consistency and provide an audit trail.
What If Your Finance Team Has Only Two People?
This is one of the most common SME challenges. Suppose a company has only:
Accountant + Accounts Assistant
The accountant may prepare payments and reconciliations because there is no third finance employee. In this situation, the business can use compensating controls. For example:
The Accounts Assistant enters invoices.
The accountant reviews and prepares payment.
The owner approves the payment.
The accountant performs the bank reconciliation.
The owner independently reviews the bank reconciliation each month.
Unusual transactions are investigated and documented.
The goal is to prevent one person from having unchecked control over the entire process.
ACFE has long emphasized that small businesses can improve controls even when staffing is limited, including through independent reviews and appropriate segregation of responsibilities.
A Practical SoD Model for a Small UAE Business
Consider a UAE trading company with three finance-related employees.
Accounts Assistant
Responsible for:
Invoice entry
Supporting documents
Customer receipts
Accountant
Responsible for:
General ledger
Bank reconciliation
Payment preparation
Financial reporting
Owner/Finance Manager
Responsible for:
Payment approval
High-value transactions
Vendor changes
Payroll approval
Monthly financial review
This arrangement does not create perfect segregation. However, it introduces important independent checkpoints.
The company can strengthen it further by using system permissions and periodic external reviews.
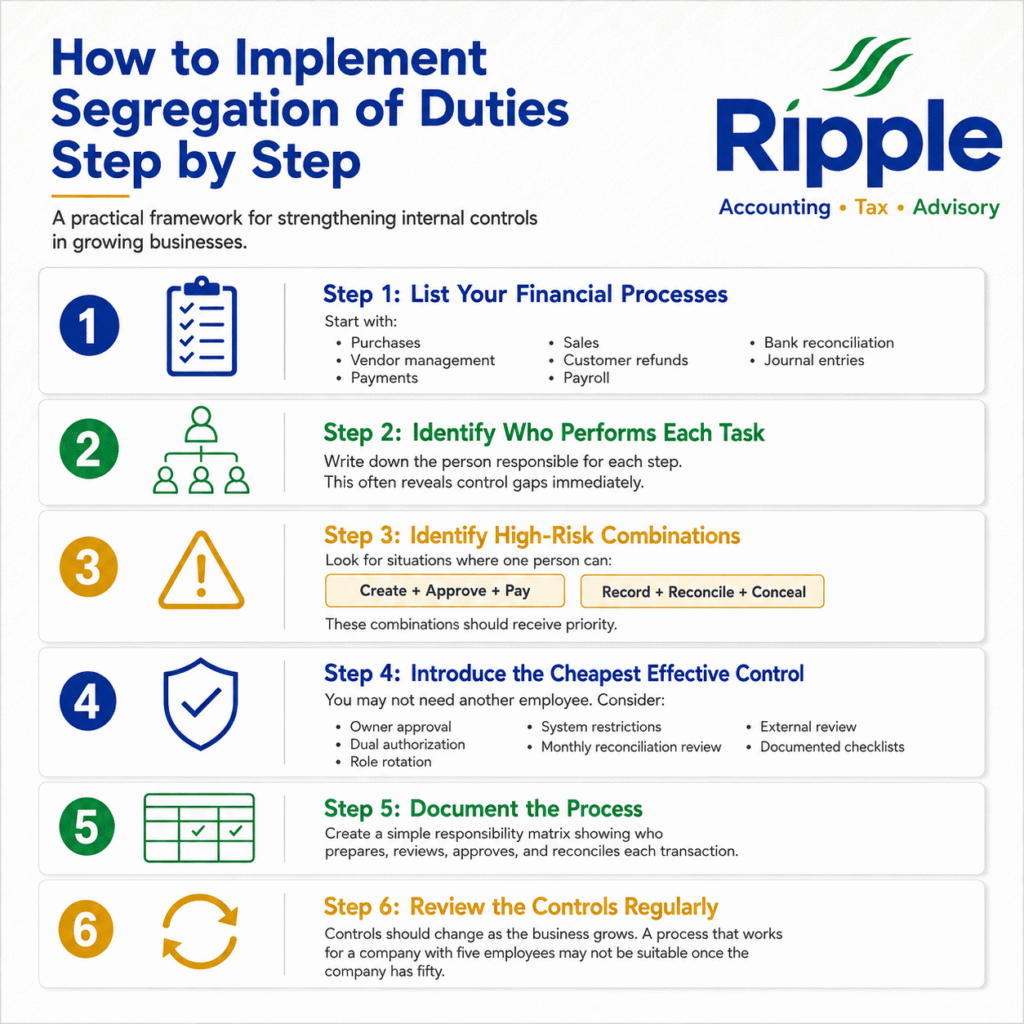
How to Implement Segregation of Duties Step by Step
Step 1: List Your Financial Processes
Start with:
Purchases
Vendor management
Payments
Sales
Customer refunds
Payroll
Bank reconciliation
Journal entries
Step 2: Identify Who Performs Each Task
Write down the person responsible for each step. This often reveals control gaps immediately.
Step 3: Identify High-Risk Combinations
Look for situations where one person can:
Create + Approve + Pay
or
Record + Reconcile + Conceal
These combinations should receive priority.
Step 4: Introduce the Cheapest Effective Control
You may not need another employee.
Consider:
Owner approval
Dual authorization
Role rotation
System restrictions
Monthly reconciliation review
External review
Documented checklists
Step 5: Document the Process
Create a simple responsibility matrix showing who prepares, reviews, approves, and reconciles each transaction.
Step 6: Review the Controls Regularly
Controls should change as the business grows. A process that works for a company with five employees may not be suitable once the company has fifty.
Segregation of Duties In UAE SME
How a Ripple Accountant Can Help
Designing segregation of duties for an SME can be difficult when business owners are already managing sales, employees, customers, and daily operations.
Ripple Accountant can support UAE SMEs in developing a more structured financial control and reporting environment. We also review the existing finance process and identify where responsibilities overlap. We help businesses improve payment records, bank reconciliations, financial reporting, and transaction reviews. We can also help management establish clearer processes to monitor cash movements and identify discrepancies.
Contact the Ripple Accountant support team today to discuss your payment, reconciliation, and financial control requirements.
Phone: +971 52 356 5409
WhatsApp: +971 4 250 0833
Email: info@uaetaxcompliance.ae
FAQs
1. What is segregation of duties in accounting?
Segregation of duties is an internal control approach that separates important financial responsibilities among different people. The aim is to prevent one person from controlling an entire transaction process.
2. Is segregation of duties only for large companies?
No. It is particularly useful for small businesses because limited staffing can create significant control gaps. Small companies may use simpler controls and compensating reviews instead of creating separate departments.
3. What if my SME has only two finance employees?
Use compensating controls. For example, one employee can prepare transactions while the owner or manager approves them. The owner can also independently review bank reconciliations and unusual transactions.
4. What are examples of accounting segregation of duties?
Examples include separating invoice entry from payment approval, vendor creation from payment processing, payroll preparation from payroll approval, and payment processing from bank reconciliation.
5. Can accounting software help with SoD?
Yes. User permissions can restrict what each employee can create, edit, approve, or access. Audit logs can also help management review financial activity.
6. Is segregation of duties a guarantee against fraud?
No. SoD reduces risk but cannot eliminate it. Collusion, management override, weak monitoring, or other control failures can still create risks. Preventive controls should therefore be supported by monitoring and independent reviews.
Conclusion
Segregation of duties for UAE SMEs does not have to mean hiring a large finance department. The most important step is identifying where one person has too much control over a financial process and introducing an independent checkpoint. A simple approval matrix, restricted accounting-system access, monthly bank reconciliation review, dual approval for high-value payments, and documented checklists can significantly strengthen SME accounting controls without creating high costs.
Disclaimer: This article is intended for general educational and informational purposes only. It does not constitute legal, tax, accounting, audit, or regulatory advice. UAE requirements can vary depending on the business structure, activity, location, tax status, and applicable regulatory framework. Businesses should obtain professional advice based on their specific circumstances.
Share
Free Consultation
Have a tax or accounting question?
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
0 Comments
No comments yet. Be the first to start the conversation.
Non-profit organizations play a vital role in supporting communities, advancing education, promoting healthcare, protecting the environment, and delivering humanitarian aid across the…
Businesses have traditionally relied on financial reports such as revenue, profit, cash flow, and expenses to evaluate performance. While these metrics remain…
Auditing different types of businesses is essential because every industry operates with unique financial processes, regulations, and risks. A manufacturing company manages…



0 Comments