Monthly Accounting Compliance Calendar for UAE SMEs
M Maria August 31, 2026 11 min read
Are your UAE business’s accounting tasks truly under control each month?
Missed reconciliations, unrecorded invoices, or delayed VAT checks can quickly turn into bigger compliance and reporting problems. A monthly accounting calendar UAE for SMEs helps businesses stay organized by scheduling bookkeeping, reconciliations, tax reviews, payroll, receivables, payables, and financial reporting throughout the year. Instead of reacting to deadlines, SMEs can follow a clear monthly routine that keeps their accounts accurate, up to date, and ready for upcoming compliance requirements.
What Is a Monthly Accounting Compliance Calendar?
A monthly accounting calendar UAE is a structured schedule that identifies the accounting, bookkeeping, tax and financial-control activities a business should complete during each month. It can include routine tasks such as:
For SMEs, the purpose is not simply to “complete the books.” The objective is to ensure that financial information remains accurate, complete, supported and available when management or regulators need it.
A calendar also makes responsibilities clearer. The business owner, accountant, bookkeeper and finance manager can each know what needs to be completed and when.
Why UAE SMEs Need a Regular Accounting Calendar
Many small businesses do their bookkeeping only when a tax return or year-end deadline approaches. This creates a backlog and increases the risk of errors. A monthly process provides several advantages.
1. Better financial visibility
When transactions are recorded regularly, owners can see revenue, expenses, receivables, payables and cash flow more accurately.
This makes it easier to answer questions such as:
How much cash is actually available?
Which customers have overdue invoices?
Are expenses increasing?
Is the business profitable?
Can upcoming supplier payments be covered?
2. Easier tax compliance
Tax compliance becomes considerably easier when accounting records are maintained throughout the year rather than reconstructed immediately before a deadline. For VAT-registered businesses, transaction records need to be reviewed regularly so that VAT treatment can be identified and supporting documents retained.
3. Fewer bookkeeping errors
Regular reconciliations can identify duplicated transactions, missing entries, incorrect amounts and unexplained balances before they become difficult to investigate.
4. Faster year-end closing
A business that closes its accounts every month has much less work to do at year-end.
5. Stronger audit trail
Consistent records make it easier to connect transactions with invoices, receipts, contracts, bank statements and other supporting documentation.
Monthly Bookkeeping Checklist for UAE SMEs
A practical monthly bookkeeping checklist UAE businesses can use should cover the complete accounting cycle rather than focusing only on data entry.
1. Collect and Record Sales Invoices
Start by ensuring that all sales made during the month have been recorded correctly. Check:
Customer name and details
Invoice number
Invoice date
Description of goods or services
Amount charged
VAT treatment, where applicable
Payment status
Missing sales invoices can distort revenue, receivables and tax calculations. Businesses should also investigate gaps in invoice numbering where appropriate.
2. Record Purchases and Business Expenses
The finance team should collect supplier invoices, receipts and other supporting documents and record eligible business expenses. Review expenses for:
Correct account classification
Supporting documentation
VAT treatment
Duplicate entries
Unusual or unusually large transactions
Avoid simply recording expenses under broad categories such as “miscellaneous” when a more accurate classification is available.
Proper categorisation improves both financial reporting and tax analysis.
3. Reconcile Bank Accounts
Bank reconciliation should be one of the most important recurring tasks in the calendar. Compare the accounting records with the company’s bank statements and identify:
Unrecorded bank charges
Missing receipts
Outstanding payments
Deposits not yet reflected
Duplicate transactions
Incorrect entries
Unidentified transfers
If a company has multiple bank accounts, each account should be reconciled separately.
Example: Suppose the accounting system shows AED 150,000 in the bank, but the statement shows AED 143,500. The difference should not simply be carried forward. The accountant should investigate whether the difference relates to outstanding payments, bank charges, unrecorded transactions or accounting errors.
4. Review Accounts Receivable
A monthly review of accounts receivable helps SMEs control cash flow. Prepare an ageing report showing amounts that are:
Current
30 days overdue
60 days overdue
90+ days overdue
The finance team should identify customers requiring follow-up and communicate significant overdue balances to management.
This is particularly important for SMEs because strong reported revenue does not necessarily mean strong cash flow.
5. Review Accounts Payable
Supplier balances should also be reviewed monthly. Check:
Outstanding supplier invoices
Due dates
Duplicate invoices
Credit notes
Unpaid supplier balances
Upcoming major payments
A proper review can help management plan cash requirements and avoid unnecessary late-payment issues.
VAT Tasks in the Accounting Calendar
VAT should be integrated into the accounting process rather than treated as a separate activity performed only before filing. The Federal Tax Authority generally requires VAT returns and related payments within 28 days from the end of the relevant tax period, subject to the applicable rules and the business’s assigned tax period.
However, businesses should not assume that every UAE company has a monthly VAT filing period. The VAT tax period assigned to a business can differ.
Therefore, a good UAE tax compliance calendar should include the company’s actual VAT return period and deadline.
Before a VAT return is prepared, review:
Output VAT
Input VAT
Sales transactions
Purchase transactions
Credit notes
Debit notes
Zero-rated transactions
Exempt transactions
Transactions requiring special VAT treatment
Supporting tax invoices
Monthly bookkeeping makes this review much easier because the underlying transactions are already organised.
Corporate Tax Should Also Be Monitored
Corporate Tax is another important component of the compliance calendar.
For UAE businesses subject to Corporate Tax, accounting records should be maintained in a way that supports the calculation of taxable income and the preparation of the Corporate Tax return. The FTA states that Corporate Tax returns and the payment of Corporate Tax are generally due within nine months from the end of the relevant tax period, subject to the applicable legislation.
This does not mean Corporate Tax work should wait until the ninth month.
Instead, SMEs should monitor Corporate Tax throughout the year.
Monthly activities can include:
Reviewing revenue
Reviewing deductible expenses
Identifying unusual transactions
Maintaining supporting documentation
Monitoring related-party transactions
Reviewing accounting classifications
Maintaining tax-relevant records
Tracking adjustments that may be required for tax purposes
This approach reduces the risk of discovering major accounting issues immediately before the Corporate Tax filing deadline.
Payroll and Employee-Related Accounting
Payroll should also have a fixed place in the monthly accounting process. Depending on the business structure, the accounting team may need to record:
Salaries
Allowances
Employee benefits
Leave-related balances
End-of-service-related accounting
Payroll liabilities
Other employee-related costs
The accounting records should be reconciled with the relevant payroll documentation.
Where payroll-related payments involve separate systems or bank transfers, these should also be checked against the accounting ledger.
Monthly Financial Close
Once transactions have been recorded and reconciliations completed, the business should perform a monthly financial close.
A basic close can include:
Confirm all sales are recorded.
Confirm supplier invoices have been entered.
Complete bank reconciliations.
Reconcile receivables.
Reconcile payables.
Review VAT-related balances.
Review payroll entries.
Investigate unusual ledger balances.
Review accruals and prepayments.
Generate management reports.
The objective is to ensure the accounting system reflects the company’s financial position as accurately as possible.
A Practical UAE SME Accounting Calendar
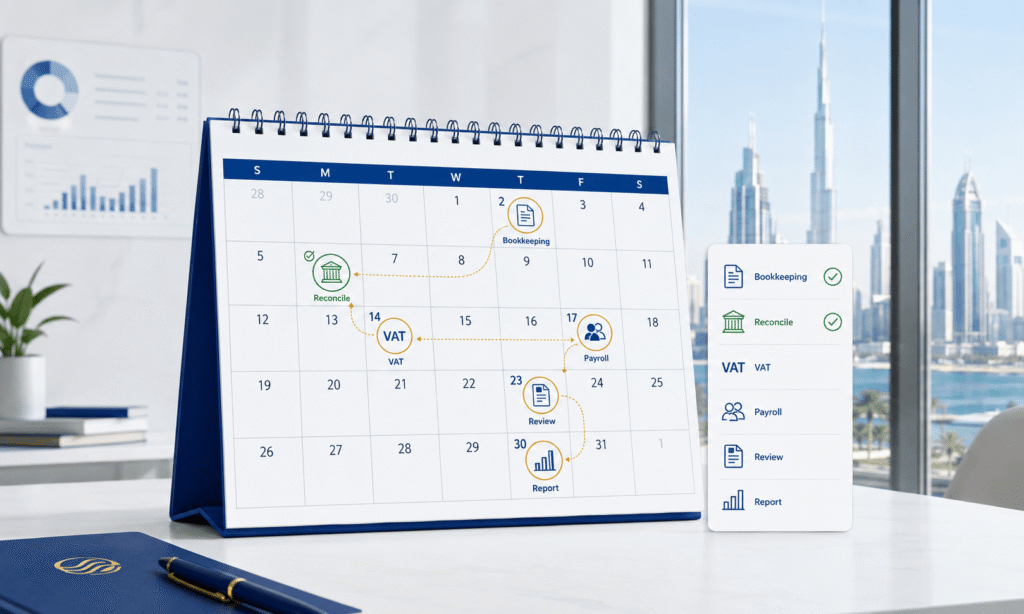
A simple UAE SME compliance calendar can be organised as follows:
Frequency
Key Activity
Weekly
Collect invoices and receipts
Weekly
Update sales and purchase records
Weekly
Monitor customer collections
Monthly
Complete bank reconciliations
Monthly
Review accounts receivable
Monthly
Review accounts payable
Monthly
Process payroll accounting
Monthly
Review VAT transactions
Monthly
Review general ledger
Monthly
Close accounts and prepare reports
Quarterly/As applicable
Prepare and file VAT return
Throughout the year
Monitor Corporate Tax position
Annually/As applicable
Prepare Corporate Tax return
Annually
Review financial records and supporting documentation
The exact schedule should be adapted to the company’s VAT tax period, financial year, business activity and other applicable obligations.
What Happens When SMEs Do Not Follow a Calendar?
Without a consistent accounting process, several problems can develop.
Accounting backlog: Transactions accumulate for weeks or months, making it harder to determine the actual financial position.
Cash-flow surprises: If receivables and payables are not monitored regularly, management may discover cash shortages too late.
Tax filing pressure: Incomplete bookkeeping makes VAT and Corporate Tax preparation more difficult.
Incorrect financial reports: Missing transactions or unreconciled balances can make profit, cash and liabilities appear different from their actual position.
Weak documentation: When supporting documents are not collected promptly, invoices and receipts can be difficult to locate later.
Increased compliance risk: Errors that could have been identified through monthly reviews may remain hidden until a tax or financial review.
How to Make the Calendar Work
Creating a calendar is only the first step. SMEs need a process for actually using it.
Assign responsibility
Every task should have an owner. For example, the bookkeeper may handle transaction recording while the accountant reviews reconciliations and the business owner reviews management reports.
Set internal deadlines before official deadlines
Don’t make the legal deadline your internal deadline. For example, if a VAT return is due on a particular date, set an earlier internal review date so there is time to correct errors.
Use accounting software
Accounting software can automate recurring tasks, generate reports and help track outstanding invoices. However, automation does not replace review.
Keep supporting documents organised
Invoices, receipts, contracts, bank statements and other records should be stored systematically and remain accessible.
Review the calendar periodically
UAE tax and regulatory requirements can change. The calendar should therefore be reviewed whenever the FTA or another relevant authority introduces new rules or requirements.
How Ripple Accountant Can Help UAE SMEs
Maintaining a monthly accounting calendar can become difficult when business owners are already managing operations, customers and employees. Ripple Accountant can support UAE businesses with bookkeeping, accounting, reconciliations, financial reporting, VAT support and Corporate Tax-related accounting processes.
The goal is not simply to record transactions but to help businesses maintain organized financial records throughout the year. A structured monthly accounting process can give management better visibility while reducing the pressure associated with tax and year-end deadlines.
1. How often should a UAE SME update its accounting records?
Ideally, transactions should be recorded continuously or at least weekly, followed by a formal monthly close. Waiting until the end of the quarter or year increases the risk of errors and backlogs.
2. Is a monthly accounting calendar mandatory in the UAE?
There is not necessarily a legal requirement to maintain a document specifically called a “monthly accounting calendar.” However, businesses have accounting, record-keeping and tax obligations, and a monthly calendar is a practical way to manage them.
3. Does every UAE business file VAT every month?
No. VAT tax periods can differ depending on the business and the period assigned by the FTA. Businesses should follow their actual VAT filing requirements rather than assuming that all VAT returns are monthly.
4. Should Corporate Tax be reviewed every month?
Yes. Even though the Corporate Tax return is generally due within nine months after the end of the relevant tax period, monitoring accounting and tax-related information throughout the year makes the eventual filing process much easier.
5. What is the most important monthly accounting task?
There is no single task that is most important for every business, but bank reconciliation, complete transaction recording, receivables/payables review and tax-related checks are among the key recurring controls.
Conclusion
A monthly accounting calendar UAE SMEs can use is more than a list of deadlines. It is a financial-control system that helps businesses keep their books current, monitor cash flow, identify errors and prepare for VAT and Corporate Tax obligations. The most effective approach is to separate routine monthly accounting tasks from tax filing deadlines. Every month, businesses should focus on recording transactions, reconciling accounts, reviewing receivables and payables, checking VAT treatment, processing payroll and closing the books.
Disclaimer: This article is provided for general informational and educational purposes only. The information in this article should not be considered legal, tax, accounting, or financial advice. Businesses should review their specific circumstances and consult a qualified UAE accounting or tax professional and, where appropriate, the Federal Tax Authority before making tax, accounting or compliance decisions.
Environmental, Social, and Governance (ESG) reporting has become a critical part of modern corporate reporting. Investors, regulators, customers, and financial institutions increasingly…
Businesses are under constant pressure to process financial data faster, reduce manual work, and improve accuracy. Traditional accounting methods often rely on…
Businesses are expanding beyond domestic markets more than ever before. Companies buy products from overseas suppliers, sell to international customers, receive payments…
0 Comments