Month-End Close Checklist UAE: A Fast 7-Day Guide for Businesses
M Maria August 22, 2026 15 min read
Month-end can feel stressful when financial records are scattered, invoices are missing, and several transactions still need to be checked. For UAE businesses, a proper month-end close is more than simply updating the accounts. It helps management understand the business’s financial position and keeps accounting records ready for reporting and tax-related requirements.
The good news is that month-end closing does not have to become a long, confusing process. With a structured month-end close checklist UAE businesses can use the same seven-day workflow every month to organize transactions, reconcile accounts, review tax-related records, and finalize financial reports.
What Is a Month-End Close?
A month-end close is the process of reviewing, completing, reconciling, and finalizing a business’s financial records for a particular month. In simple terms, it means checking that the money coming into and going out of your business has been recorded correctly before you rely on the numbers for decision-making.
The process normally includes reviewing sales, purchases, expenses, bank transactions, customer balances, supplier balances, payroll, and other financial information. It can also include adjustments for items such as accruals and prepayments before financial reports are finalized.
Month-end close is different from basic bookkeeping. Bookkeeping records financial transactions, while month-end close checks whether those records are complete, accurate, and properly reconciled.
Why Is Month-End Close Important for UAE Businesses?
A well-managed close gives business owners and managers a clearer picture of:
How much revenue the business generated
What expenses it incurred
How much customers owe
How much the business owes suppliers
How much cash is available
Whether expenses or income have been recorded correctly
Whether financial results are changing unexpectedly
It also creates more reliable records for financial reporting and tax-related work. The Federal Tax Authority (FTA) expects businesses subject to Corporate Tax to maintain financial statements and supporting records that substantiate information reported to the Authority.
Important: A monthly close is an internal accounting process, not a UAE tax filing deadline. The seven-day framework in this article is a practical workflow for organizing your accounts.
What Should Be Completed Before Month-End Close?
Before starting the seven-day close, gather the information your finance or accounting team will need.
Start by checking that:
All sales have been recorded.
Purchase invoices have been received and entered.
Business expenses have supporting documents.
Bank transactions have been imported or recorded.
Customer invoices are up to date.
Supplier bills are recorded.
Payroll-related entries are available.
Missing receipts or invoices have been identified.
Any unusual transactions have been flagged.
The aim is simple: do not begin the final review while important transactions are still missing.
For UAE businesses, maintaining organized records is particularly important because accounting information may support VAT and Corporate Tax obligations. FTA guidance identifies records such as accounting entries, purchases, sales, expenses, balance sheets, income statements, wages, fixed assets, and relevant tax documentation among the records businesses may need to maintain.
7-Day Month-End Close Checklist UAE Businesses
Now let’s break the entire process into seven manageable days.
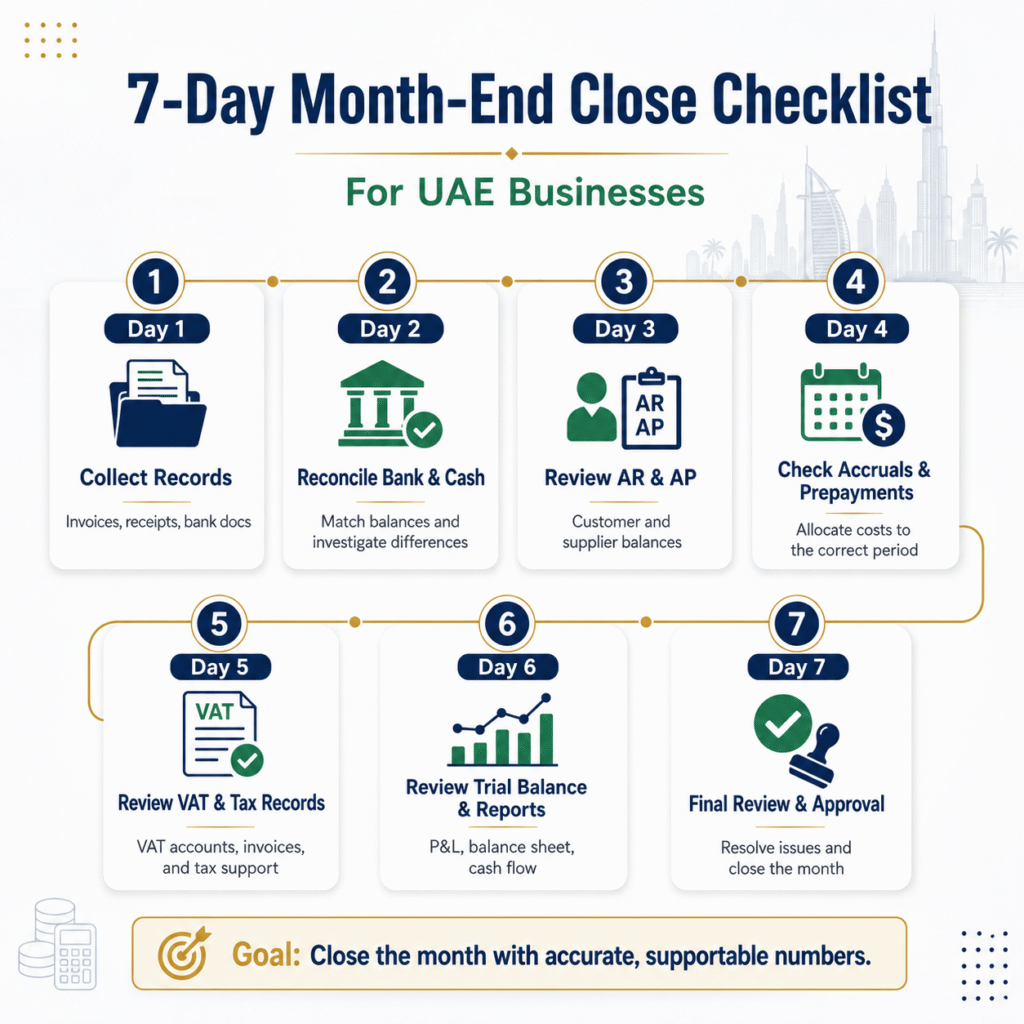
7-Day UAE Month-End Close Checklist
Day 1 – Collect and Organize Financial Records
The first day is about getting everything together. Collect sales invoices, purchase invoices, receipts, bank statements, expense records, payroll information, and other documents relating to the month. Then check whether transactions have been recorded in the correct accounting period.
For example, imagine your business received a supplier invoice for services provided in August, but the invoice was entered into September’s accounts. That can distort both months’ financial results. During Day 1, look for:
Missing sales invoices
Unrecorded purchases
Missing expense receipts
Duplicate transactions
Transactions entered in the wrong month
Unidentified bank transactions
Missing supporting documents
At the end of Day 1, you should have a clear list of anything still missing.
Goal: Make sure the financial records are complete before moving to reconciliation.
Day 2 – Reconcile Bank and Cash Accounts
Bank reconciliation may sound complicated, but the basic idea is simple. Bank reconciliation means comparing your accounting records with your bank statement to make sure they agree.
For example, your accounting system may show a payment that has not yet appeared on the bank statement. Alternatively, the bank may show a charge that has not yet been recorded in your books.
Review:
Bank balances
Deposits
Withdrawals
Bank charges
Transfers
Outstanding checks or payments
Unidentified transactions
Duplicate entries
Do not simply adjust a difference because the numbers do not match. First, investigate why the difference exists. This step is important because an incorrect bank balance can affect your understanding of the business’s available cash.
Goal: Reconcile every relevant bank and cash account and document unresolved differences.
Day 3 – Review Accounts Receivable and Accounts Payable
On Day 3, focus on money coming into and going out of the business.
Accounts Receivable
Accounts receivable means money customers owe your business.
Review:
Outstanding customer invoices
Overdue invoices
Customer balances
Credit notes
Payments received but not allocated
Old or doubtful balances
For example, if a customer was invoiced AED 20,000 but has only paid AED 15,000, the remaining AED 5,000 should appear as an outstanding receivable.
Accounts Payable
Accounts payable means money your business owes suppliers and other parties.
Check:
Unpaid supplier invoices
Supplier statements
Outstanding bills
Credit notes
Payments waiting to be recorded
You should also investigate old balances that have remained outstanding for several months.
Goal: Know exactly what customers owe you and what your business owes others.
Day 4 – Check Expenses, Accruals and Prepayments
Some expenses do not fit neatly into the month when money is actually paid. This is where accruals and prepayments become important.
What Is an Accrual?
An accrual is an expense that relates to the current month but has not yet been invoiced or paid. For example, your business may use electricity during August but receive the bill in September. If appropriate under the accounting framework being used, the August expense may need to be recognized in August.
What Is a Prepayment?
A prepayment occurs when you pay for something in advance that relates to future periods. Suppose your business pays an annual insurance premium upfront. The entire payment should not necessarily be treated as an expense of one month. The amount may need to be allocated across the periods to which the insurance relates. Review areas such as:
Rent
Insurance
Software subscriptions
Utilities
Professional services
Annual contracts
Other recurring expenses
The purpose is to make sure the month’s financial results reflect the appropriate income and expenses.
Goal: Identify expenses or payments that need to be allocated to the correct accounting period.
Day 5 – Review VAT and Tax-Related Records
This is one of the most important areas for a UAE business, but it does not need to be complicated for a non-tax professional. The purpose of the month-end review is not to prepare a tax return automatically. Instead, it is to make sure the accounting records that may feed into tax reporting are organized and supported.
VAT Review
If your business is VAT registered, review:
Sales transactions
Purchase transactions
VAT charged on relevant sales
Recoverable input VAT where applicable
Tax invoices
Credit notes
VAT-related adjustments
VAT control account balances
The FTA states that VAT-registered businesses must retain relevant records, including records of supplies and imports, tax invoices and credit notes, exports, and adjustments or corrections.
A monthly reconciliation can help identify discrepancies before they become more difficult to investigate.
Corporate Tax
Corporate Tax is another reason accurate accounting records matter. Businesses subject to UAE Corporate Tax need to maintain financial statements and records supporting the information used in their Corporate Tax filings. The FTA says these records can include transaction records, asset records and liability records, depending on the business.
However, do not assume that accounting profit automatically equals taxable income. Corporate Tax calculations can involve specific tax adjustments and rules.
Goal: Keep accounting and tax-related records organized so potential issues can be identified early.
Day 6 – Review the Trial Balance and Financial Statements
Now that the underlying records have been checked, review the overall accounting picture.
What Is a Trial Balance?
A trial balance is a report that lists the balances of accounts in the accounting system. It is used as part of the process of checking the accounting records before financial statements are finalized. For a non-accountant, think of it as a high-level checkpoint.
Look for:
Unexpected balances
Large changes from previous months
Unusual expenses
Negative balances that need investigation
Missing revenue
Duplicate entries
Significant fluctuations
Then review the main financial reports.
Profit and Loss Statement
This shows the business’s income and expenses over a period and helps you understand whether the business made a profit or loss.
Balance Sheet
This shows what the business owns and owes at a particular date, along with the owner’s or shareholders’ interest.
Cash Flow Statement
This helps explain how cash moved into and out of the business. You do not need to be an accountant to ask useful questions. For example:
Why did revenue fall by 20% this month?
Why did expenses suddenly increase?
Why is the customer balance much higher than last month?
These questions can reveal problems that a simple total might hide.
Goal: Make sure the financial reports tell a logical and supportable story.
Day 7 – Final Review, Approval, and Reporting
The final day is about bringing everything together. Before closing the month, check that:
Bank accounts are reconciled.
Customer balances have been reviewed.
Supplier balances have been reviewed.
Accruals and prepayments have been considered.
VAT-related accounts have been reviewed where applicable.
Tax-related records are organized.
Unusual transactions have been investigated.
Financial statements have been reviewed.
Supporting documents are available.
Outstanding issues have assigned owners.
Once the review is complete, management can approve the results and finalize the accounting period according to the business’s internal procedures and accounting system.
The final question should be: Can every important number be explained and supported?
If the answer is yes, your month-end close is in much better shape.
UAE-Specific Month-End Close Considerations
A UAE business may have additional considerations depending on its activities, legal structure, VAT registration, corporate tax position, free-zone status, transactions, and reporting requirements.
VAT Records and Reconciliation
Regular reconciliation helps compare accounting records with VAT-related information and identify missing or inconsistent transactions. Remember that the exact VAT treatment of a transaction depends on its circumstances. A month-end checklist should therefore identify potential issues rather than replace professional tax advice.
Corporate Tax Records
Accurate accounting records are important for determining and supporting information relevant to corporate tax. The FTA states that records and documents for UAE corporate tax purposes should generally be retained for at least seven years following the end of the relevant tax period.
Payroll and WPS-Related Records
Payroll should also be reflected correctly in the accounting records. Check salaries, payroll-related expenses, deductions and other relevant entries. Where WPS requirements apply, payroll administration should be handled according to the applicable requirements.
Foreign Currency Transactions
UAE businesses often deal with international customers and suppliers. If transactions are denominated in foreign currencies, review:
Foreign currency invoices
Payments
Exchange-rate differences
Foreign currency balances
Relevant revaluation or accounting adjustments
The appropriate accounting treatment should follow the accounting framework used by the business.
Common Month-End Close Mistakes UAE Businesses Should Avoid
Even businesses with accounting software can experience month-end problems.
1. Waiting Until the Last Day: Trying to complete everything at once creates unnecessary pressure and increases the chance of errors.
2. Recording Transactions Late: Missing transactions can make the monthly reports inaccurate.
3. Ignoring Bank Differences: A small unexplained difference can sometimes indicate a larger recording problem.
4. Forgetting Unpaid Expenses: Expenses should not be ignored simply because the invoice has not yet been paid.
5. Recording Expenses in the Wrong Month: Incorrect timing can make one month appear more profitable while another appears less profitable.
6. Ignoring Old Receivables: An outstanding customer balance does not automatically mean the money will be collected.
7. Treating VAT Reconciliation as an Afterthought: Finding VAT-related discrepancies early is easier than discovering them later.
8. Poor Document Management: The FTA requires businesses to maintain records that allow tax information and transactions to be supported and verified.
9. Making Unexplained Adjustments: Every significant adjustment should have a clear reason and supporting evidence.
10. Finalizing Without Review: A second-level review can catch mistakes that the person preparing the accounts may overlook.
How to Make the Month-End Close Faster
A fast close does not mean skipping important checks. It means making the process organized and repeatable.
Use a Standardized Checklist
Use the same month-end close checklist UAE businesses can follow every month. This reduces the chance of forgetting recurring tasks.
Set Internal Deadlines
Do not wait until the final day of the month to collect invoices and receipts.
For example, you could establish internal deadlines for submitting:
Sales invoices
Supplier invoices
Expense claims
Payroll information
Bank-related documents
Automate Repetitive Tasks
Accounting software can reduce manual work through features such as:
Bank feeds
Recurring transactions
Invoice processing
Automated reconciliation
Reporting dashboards
Automation should support review, not eliminate human oversight.
Assign Clear Responsibilities
Everyone should know who is responsible for each task.
For example:
Task
Responsible person
Sales invoices
Sales/Finance
Supplier bills
Accounts/Finance
Bank reconciliation
Accountant
Payroll entries
HR/Finance
VAT review
Finance/Tax
Final approval
Management
Track Unresolved Issues
Keep an open items list containing:
The issue
Responsible person
Required action
Due date
Status
Supporting evidence
This prevents unresolved problems from disappearing into the next month.
Month-End Close Checklist UAE: Quick Reference
Use this quick checklist at the end of every month:
Collect invoices and receipts
Record all sales and purchases
Reconcile bank accounts
Review cash balances
Check accounts receivable
Check accounts payable
Review payroll entries
Record appropriate accruals
Review prepayments
Check VAT-related records where applicable
Review corporate tax-related accounting records
Review the trial balance
Check financial statements
Investigate unusual balances
Resolve or assign outstanding issues
Complete management review
Finalize the accounting period according to internal procedures
Save supporting records securely
How Long Should a Month-End Close Take?
There is no single number of days that every UAE business must use for its month-end close. A small business with relatively few transactions may be able to complete its close quickly. A larger organization with multiple bank accounts, branches, entities, currencies, suppliers, and customers may need considerably more time.
The seven-day approach is a practical target and workflow—not a legal UAE tax deadline.
The real objective is to create a process that is:
Consistent + Accurate + Documented + Reviewable
A business that closes its accounts in three days but produces unreliable numbers has not achieved a better close than a business that takes seven days and produces accurate, well-supported information.
When Should a UAE Business Get Professional Accounting Help?
Professional accounting or tax support may be useful when:
Transaction volumes are increasing rapidly.
Bank reconciliations regularly contain unexplained differences.
Customer or supplier balances are difficult to understand.
VAT treatment is becoming complicated.
The business has significant foreign currency transactions.
Professional support is especially valuable when a business is unsure about the tax treatment of a particular transaction. A checklist can organize the work, but it cannot replace advice tailored to the business’s circumstances.
How Ripple Can Help UAE Businesses
Running a business in the UAE requires more than managing day-to-day operations. Companies also need to maintain accurate financial records, meet regulatory requirements, manage tax obligations, and build internal processes that support long-term growth.
Ripple Accountants supports UAE businesses with practical accounting, tax, compliance, and advisory services tailored to their operational needs. From bookkeeping and financial reporting to VAT, Corporate Tax, AML compliance support, and management advisory, Ripple helps businesses improve financial visibility and stay better prepared for regulatory requirements.
Contact us today to discuss your payment, reconciliation, and financial control requirements.
Email: info@uaetaxcompliance.ae
Phone: +971 52 356 5409
WhatsApp: +971 4 250 0833
Frequently Asked Questions
1. What is a month-end close checklist?
A month-end close checklist is a structured list of accounting tasks a business completes at the end of each month to ensure its financial records are complete, reconciled, reviewed and ready for reporting.
2. How does month-end close work in UAE businesses?
The process generally involves recording transactions, reconciling accounts, reviewing receivables and payables, checking expenses and adjustments, reviewing relevant VAT and tax-related records, and finalizing financial reports.
3. How many days should month-end close take?
There is no universal timeframe. The seven-day process in this guide is a practical framework that businesses can adapt to their size and complexity.
4. Is month-end close required by UAE tax authorities?
Month-end close itself is an internal accounting process rather than a specific tax filing requirement. However, maintaining accurate financial and supporting records is important for businesses with UAE tax obligations.
5. Does month-end close include VAT reconciliation?
It can. For VAT-registered businesses, reviewing VAT-related transactions and reconciling relevant accounts can be an important part of the monthly accounting process.
6. What is the difference between month-end close and year-end close?
Month-end close reviews and finalizes financial information for a single month. Year-end close is a more extensive process covering the entire financial year and may involve additional adjustments, financial reporting, and audit or tax preparation.
7. What documents are needed for month-end close?
Common documents include sales invoices, purchase invoices, receipts, bank statements, payroll records, expense documents, credit notes, and other supporting records relevant to the business.
Conclusion
A successful month-end close is not simply about finishing the bookkeeping before the month ends. It is about making sure the business’s financial information is complete, accurate, reconciled, and ready for review.
For UAE businesses, a structured month-end close checklist UAE approach can make this process easier to manage. By dividing the work across seven days, from collecting records and reconciling bank accounts to reviewing tax-related information and finalizing reports, you can reduce last-minute pressure and identify problems earlier.
Disclaimer: This article is intended for general educational and informational purposes only. It does not constitute legal, tax, accounting, audit, or regulatory advice. UAE requirements can vary depending on the business structure, activity, location, tax status, and applicable regulatory framework. Businesses should obtain professional advice based on their specific circumstances.
Share
Free Consultation
Have a tax or accounting question?
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
0 Comments
No comments yet. Be the first to start the conversation.
Non-profit organizations play a vital role in supporting communities, advancing education, promoting healthcare, protecting the environment, and delivering humanitarian aid across the…
Businesses have traditionally relied on financial reports such as revenue, profit, cash flow, and expenses to evaluate performance. While these metrics remain…
Auditing different types of businesses is essential because every industry operates with unique financial processes, regulations, and risks. A manufacturing company manages…



0 Comments