Internal Controls Review for UAE SMEs: A Practical Checklist
M Maria September 14, 2026 10 min read
Are your business controls strong enough to prevent errors, fraud and compliance problems before they reach your financial statements?
For UAE SMEs, an internal controls review UAE can help identify weaknesses in financial processes, approvals, record keeping and access controls before they become larger problems. A structured review allows business owners to understand how transactions are authorized, recorded, reconciled and monitored. This practical checklist explains the key areas SMEs should review and how stronger internal controls can support reliable accounting, audit readiness and compliance.
What Is an Internal Controls Review?
An internal controls review is a structured assessment of the processes and procedures a business uses to manage its financial and operational activities. The objective is not simply to find mistakes. It is to determine whether controls are properly designed and consistently followed.
For example, a business may have a rule requiring management approval before payments are made. The review should establish whether:
The approval requirement is documented.
The appropriate person approves the payment.
Supporting documents are available.
Payment authority is restricted.
The transaction is properly recorded.
Bank and accounting records are subsequently reconciled.
For SMEs, these controls are particularly important because a small finance team may mean that one employee handles several stages of a transaction.
Why Should UAE SMEs Review Internal Controls?
Weak controls can lead to inaccurate financial records, duplicate payments, unauthorised transactions, missing documentation and difficulties during an audit. A review can help management identify these weaknesses before they affect financial reporting or regulatory compliance.
The UAE Federal Tax Authority (FTA) also requires businesses to maintain appropriate accounting records and supporting information. FTA Decision No. 4 of 2026 specifically sets rules and requirements for information maintained in accounting records and commercial books.
An internal controls review can therefore help SMEs determine whether their accounting processes are sufficiently organised to support accurate and complete records.
Internal Control Checklist for UAE SMEs
A practical internal control checklist UAE businesses can use should cover the following areas.
1. Review Access to Financial Systems
Start by checking who can access the accounting system, online banking platform and other financial applications. Access should be based on job responsibilities rather than convenience.
Check whether:
Each employee has an individual login.
Former employees have been removed from systems.
Access rights are reviewed periodically.
Sensitive financial information is restricted.
Employees only have permissions necessary for their roles.
Administrative access is limited to authorised personnel.
The FTA’s technical requirements for tax accounting software also highlight access controls and permissions as important controls for protecting accounting data.
2. Check the Purchase and Payment Process
Purchasing is an important area for an internal controls review UAE because weaknesses can result in unauthorised or duplicate payments.
SMEs should review whether there is a clear process for:
Requesting purchases.
Obtaining approval.
Selecting or confirming suppliers.
Receiving goods or services.
Checking supplier invoices.
Authorising payments.
Recording the transaction.
Where practical, different employees should be responsible for approving purchases, processing payments and reconciling bank transactions.
This separation reduces the risk that one person can initiate and complete an unauthorised transaction without detection.
3. Review Sales and Receivables Controls
Sales transactions should be supported by appropriate documentation and recorded accurately. Businesses should check whether:
Sales invoices are issued sequentially.
Customer details are reviewed.
Credit terms are approved.
Outstanding receivables are monitored.
Credit notes and refunds require approval.
Customer balances are reconciled.
Long-overdue invoices are investigated.
Management should also review whether revenue recorded in the accounting system agrees with sales documentation and bank receipts.
4. Check Bank Reconciliation Procedures
Bank reconciliation is one of the most useful controls for identifying errors and unusual transactions. An SME should reconcile each business bank account regularly rather than waiting until year-end.
The review should check whether:
Bank statements are obtained directly from the bank.
Reconciliations are prepared regularly.
Outstanding items are investigated.
Unusual transactions are reviewed.
Old unreconciled balances are cleared.
A responsible person reviews the reconciliation.
Bank reconciliation should not simply be treated as a bookkeeping task. It can provide management with an important independent check over cash movements.
5. Review Payroll Controls
Payroll should also be included in an SME’s internal control review. Businesses should establish controls over employee onboarding, salary changes, attendance information, deductions and termination payments.
Check whether:
New employees require documented approval.
Salary changes are authorised.
Payroll is reviewed before payment.
Employee bank details are protected.
Departing employees are removed promptly.
Payroll records agree with accounting records.
Payroll-related payments are reconciled.
Where payroll is subject to specific UAE regulatory requirements, businesses should also ensure their processes are consistent with applicable rules.
6. Review Inventory Controls
Businesses that hold inventory should assess whether physical stock and accounting records agree. An internal control checklist UAE SMEs can use for inventory should include:
Regular physical stock counts.
Proper recording of purchases and sales.
Authorised inventory adjustments.
Investigation of damaged or obsolete stock.
Restricted warehouse access.
Reconciliation between physical quantities and accounting records.
Differences between physical inventory and accounting records should be investigated rather than simply adjusted without explanation.
7. Check Fixed Asset Controls
Fixed assets such as machinery, vehicles, computers and equipment should be properly recorded and monitored. Review whether the business maintains:
A fixed asset register.
Purchase documentation.
Asset identification details.
Acquisition dates and costs.
Depreciation records.
Disposal documentation.
Approval for asset purchases and disposals.
Periodic physical verification can help identify assets that are missing, incorrectly recorded or no longer in use.
8. Review Accounting Records and Supporting Documents
A strong control environment depends on complete supporting documentation. SMEs should check whether transactions can be traced from the accounting system back to their source documents.
For example, an expense should ideally have appropriate evidence such as an invoice, receipt, purchase approval or other relevant documentation.
The FTA has emphasised the importance of maintaining records and documents supporting information reported in Corporate Tax returns. Businesses should therefore review whether accounting records are complete, organised and supported by appropriate documentation.
9. Review Approval and Authorisation Controls
Every SME should clearly define who can approve different types of transactions. For example, management may establish different approval levels for:
Supplier payments.
Purchases.
Employee expenses.
Discounts.
Refunds.
Credit notes.
Asset purchases.
Bank transfers.
Approval limits should be documented and communicated to employees. A control is less effective if employees do not understand who has authority to approve a transaction.
10. Review Segregation of Duties
Segregation of duties means dividing important responsibilities between different people where practical. For example, the person who creates a supplier should ideally not have unrestricted authority to approve and pay that supplier’s invoices.
Similarly, the employee preparing a bank reconciliation should not necessarily be the only person responsible for initiating payments.
SMEs may have limited staff, making complete segregation difficult. In such cases, management review and secondary approval can provide additional oversight.
How to Identify Weaknesses During an Internal Controls Review
Finding a control weakness is only the first step. Businesses should determine its potential impact and decide how it should be addressed. A simple review can classify findings as:
Low risk: Minor documentation or process weaknesses that are unlikely to materially affect financial information.
Medium risk: A weakness that could result in recurring errors, delays or inaccurate records if not corrected.
High risk: A significant weakness involving financial authority, access, fraud exposure, regulatory compliance or material financial reporting.
Each significant finding should have a clear action, responsible person and target completion date.
Common Internal Control Weaknesses in SMEs
Some weaknesses occur repeatedly in growing businesses.
These may include:
Shared accounting system passwords.
Lack of documented approval limits.
One person controlling too many financial processes.
Infrequent bank reconciliations.
Missing supplier invoices or receipts.
Unauthorised journal entries.
Poor monitoring of receivables.
Outdated employee access.
Incomplete inventory records.
Lack of management review.
Unresolved reconciliation differences.
These weaknesses do not necessarily mean that fraud or financial misstatement has occurred. However, they can increase the risk of errors and make problems more difficult to detect.
Internal Controls and Audit Readiness
An internal controls review can be particularly useful before an external audit. Auditors may need to understand the company’s accounting processes, supporting documentation and relevant controls when performing their work. The UAE Ministry of Economy & Tourism maintains legislation governing the accounting and auditing profession, including Federal Decree Law No. 41 of 2023, which concerns the regulation of the accounting and auditing profession.
An internal review before an audit can help management identify documentation gaps, reconciliation issues and process weaknesses early. It should not, however, be treated as a replacement for an independent statutory audit where an audit is legally required.
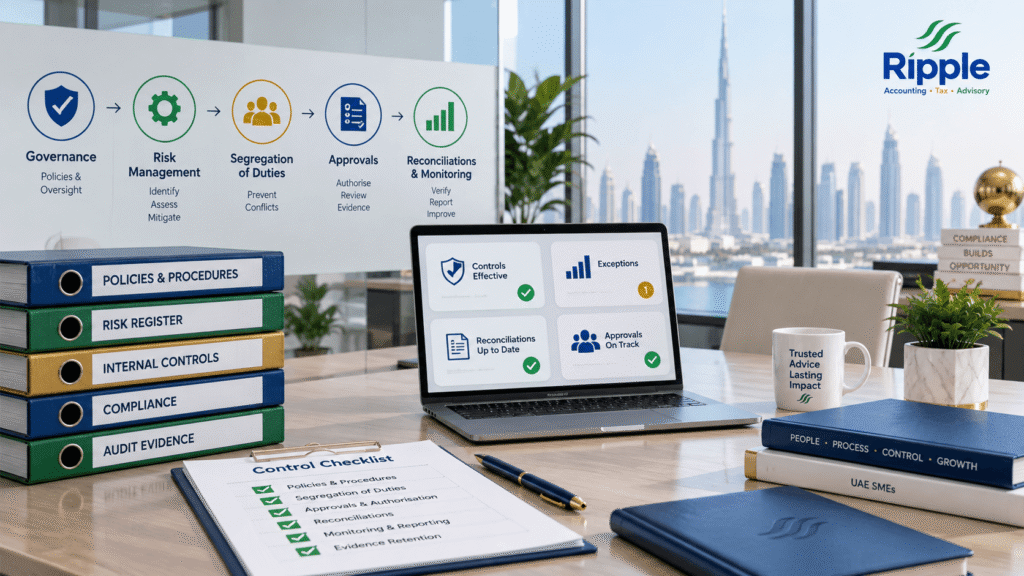
A Practical Internal Controls Review Checklist
Before completing the review, UAE SMEs can ask the following questions:
Control Area
Key Question
System access
Do employees have only the access they need?
Purchases
Are purchases properly approved?
Payments
Are payments reviewed before release?
Sales
Are invoices complete and properly recorded?
Receivables
Are overdue balances regularly reviewed?
Bank accounts
Are bank accounts reconciled regularly?
Payroll
Are salary changes and payroll payments authorised?
Inventory
Are physical stocks periodically checked?
Fixed assets
Is there an updated asset register?
Accounting records
Are transactions supported by appropriate documents?
Approvals
Are approval limits clearly defined?
Segregation
Are incompatible duties separated where practical?
Management review
Are financial reports and unusual transactions reviewed?
Access changes
Are former employees removed from financial systems?
This checklist can be adapted according to the size, industry and complexity of the business.
How Ripple Accountants Can Help
Ripple Accountants supports UAE businesses with practical accounting, audit, and compliance services. Its services include accounting and bookkeeping, financial reporting, budgeting and forecasting, account reconciliation, VAT registration and filing, Corporate Tax support, compliance reviews and audit support. Ripple can help businesses review their financial processes, identify potential control weaknesses and improve the organization of accounting records before an audit or compliance review.
If your business needs an internal controls review UAE, contact Ripple Accounting, Tax & Advisory to discuss your requirements and get tailored support for your business!
Email: info@uaetaxcompliance.ae
Phone: +971 52 356 5409
WhatsApp: +971 4 250 0833
FAQs
1. What is an internal controls review UAE?
An internal controls review UAE is an assessment of a company’s financial and operational processes to identify weaknesses, risks and opportunities to improve controls. It can cover areas such as payments, accounting records, system access, payroll, inventory and bank reconciliation.
2. Why should SMEs conduct an internal controls review?
An internal controls review can help SMEs identify errors, weak approval procedures, documentation gaps and access risks before they lead to larger financial or compliance issues. It can also help businesses prepare their processes and records for an audit.
3. What should be included in an internal control checklist UAE?
A practical checklist can include accounting system access, purchase approvals, payment controls, sales and receivables, bank reconciliation, payroll, inventory, fixed assets, accounting records, segregation of duties and management review.
4. Can a small business have effective internal controls with a small finance team?
Yes. Complete segregation of duties may not always be possible in a small business. However, management can introduce compensating controls such as secondary approval, regular management review, restricted system access and independent bank reconciliation reviews.
5. Is an internal controls review the same as an external audit?
No. An internal controls review focuses on assessing and improving a company’s processes and controls. An external audit is an independent examination performed in accordance with applicable professional and regulatory requirements. An internal review can help a business prepare for an audit but does not replace an audit where one is required.
Conclusion
A strong internal control system helps UAE SMEs protect financial information, reduce errors, improve accountability and maintain reliable accounting records. Regular reviews can also help management identify weaknesses before they create larger financial, audit or compliance problems. Rather than treating internal controls as a one-time exercise, businesses should review key processes periodically as their employees, systems, suppliers and operations change.
Disclaimer: This article provides general information for UAE businesses and should not be considered legal, tax, accounting or audit advice. Regulatory requirements may vary according to the company’s legal structure, activities, location and circumstances. Businesses should review current UAE legislation and obtain professional advice for their specific situation.
Environmental, Social, and Governance (ESG) reporting has become a critical part of modern corporate reporting. Investors, regulators, customers, and financial institutions increasingly…
Businesses are under constant pressure to process financial data faster, reduce manual work, and improve accuracy. Traditional accounting methods often rely on…
Businesses are expanding beyond domestic markets more than ever before. Companies buy products from overseas suppliers, sell to international customers, receive payments…
0 Comments