Related-Party Transactions and UAE Tax Review: What SMEs Should Check
Do your group companies share loans, employees, management services, office space or other resources? If so, these arrangements may create related party…
Read article
Could an entity qualify for UAE Corporate Tax exemption but still face an issue because it applied at the wrong time or followed the wrong procedure?
The UAE Federal Tax Authority has issued FTA Decision No. 15 of 2026, introducing updated procedural rules for Corporate Tax registration and exemption applications. The Decision was issued on 8 September 2026 and became effective on 15 September 2026. It also replaces the earlier FTA Decision No. 7 of 2023.
For entities that fall within the exemption categories referenced in Article 4 of the UAE Corporate Tax Law, the update is particularly important because it sets out registration requirements, exemption-application deadlines, special transitional dates and the circumstances in which the FTA may adjust the effective date of an exemption.
Here is what businesses and other potentially exempt persons should understand.
FTA Decision No. 15 of 2026 is titled “Provisions of Exemption from Corporate Tax for the Purposes of Federal Decree-Law No. 47 of 2022 on the Taxation of Corporations and Businesses and its amendments.”
The Decision should therefore be read together with the UAE Corporate Tax Law and the relevant Cabinet and Ministerial Decisions governing particular categories of exempt persons.
The document itself states that the English version provided is an unofficial translation, an important point where the precise legal wording of a provision needs to be considered.
The Decision also references several pieces of legislation concerning qualifying public benefit entities, investment funds, private pension and social security funds and other persons that may receive exemption treatment under the Corporate Tax framework.
One seemingly small but practically important change is the specific definition of a Business Day. For the purposes of the Decision, a Business Day means any day of the week other than weekends and official holidays of the Federal Government.
This matters because several exemption deadlines under the Decision are calculated using 90 Business Days, rather than 90 calendar days.
Entities managing exemption applications should therefore avoid calculating their deadline simply by adding three calendar months to the relevant date.
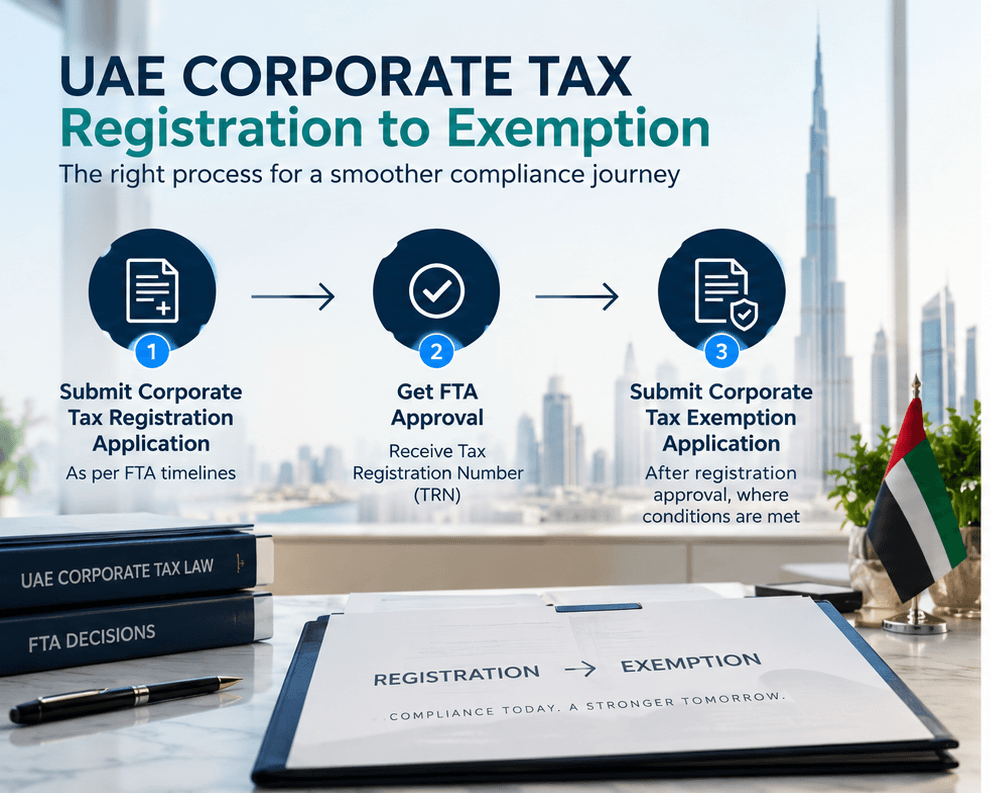
Article 2 establishes an important procedural sequence.
Persons falling within the categories referred to in paragraphs (e), (f), (g), (h) and (i) of Article 4(1) of the Corporate Tax Law must submit a Corporate Tax registration application in accordance with the applicable registration timelines under FTA Decision No. 3 of 2024 and its amendments.
For persons falling within paragraphs (f), (g), (h) and (i), an application for Corporate Tax exemption may be submitted after the FTA approves the Tax Registration application, provided the relevant exemption conditions under the Corporate Tax Law have been satisfied.
In practical terms, qualifying for exemption does not necessarily mean that an entity should ignore Corporate Tax registration.
The Decision creates a process in which the relevant person may first need to complete registration and then proceed with the exemption application.
That distinction can be particularly important for entities that assume exempt status automatically removes every registration-related obligation.
One of the most significant provisions appears in Article 3.
For persons covered by paragraphs (f), (g), (h) and (i) of Article 4(1) of the Corporate Tax Law, the exemption application must be made after the end of the Tax Period in which the exemption conditions were satisfied, and no later than 90 Business Days after the end of that Tax Period.
This creates a clear compliance window.
Entities should therefore identify:
The calculation becomes especially important where weekends or Federal Government holidays fall within the period.
The Decision also contains transitional rules for certain persons eligible for exemption with retrospective effect.
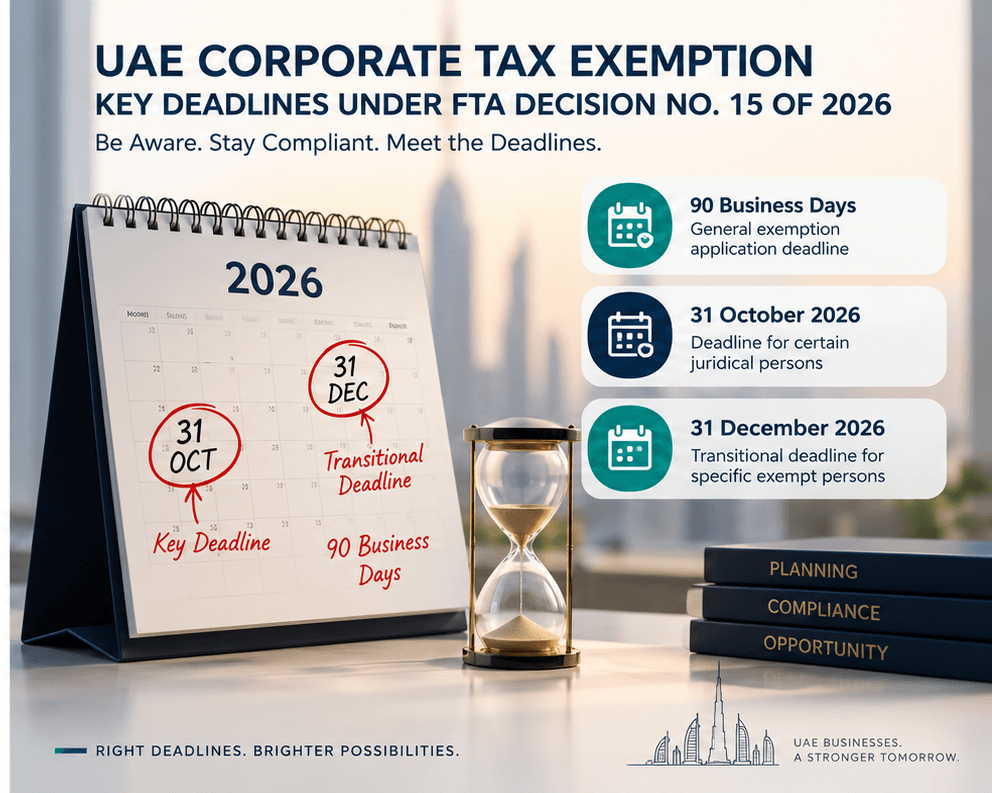
A person falling under paragraph (i) of Article 4(1) who is eligible for retrospective exemption and is included within Cabinet Decision No. 55 of 2025 must submit the exemption application no later than:
31 December 2026.
For relevant Cabinet Decisions issued on or after 1 January 2026, the applicable deadline is generally 90 Business Days from the end of the Tax Period in which the relevant Cabinet Decision was issued.
These special rules are significant because an entity relying only on the general 90-Business-Day provision could overlook a specific transitional deadline applying to its circumstances.
Another special deadline applies to juridical persons entitled to seek exemption under Article 5 of Cabinet Decision No. 34 of 2025.
Where the relevant Tax Period:
commenced during calendar year 2025, and ended on or before 31 August 2026, the exemption application must be submitted no later than 31 December 2026.
This provision gives affected juridical persons a specific transitional date rather than requiring them to rely only on the standard exemption timetable.
FTA Decision No. 15 of 2026 also addresses situations involving ownership and control by another exempt or potentially exempt person.
A juridical person covered by paragraphs (h) or (i) and wholly owned and controlled by a person falling within paragraphs (f), (g) or (h) may submit an exemption application where the owner or controlling person has itself applied for exemption.
However, the FTA will not make a decision on the juridical person’s application until the exemption application of the person that wholly owns and controls it has been approved.
This effectively creates a dependency between the two applications.
Groups with multiple entities should therefore consider the sequence of exemption applications rather than treating every application as an entirely independent process.
The Decision contains another specific transitional deadline that affected entities should not overlook.
A juridical person referred to in paragraph (h) of Article 4(1) that is wholly owned and controlled by a person falling within paragraphs (a) or (b) may apply for exemption for a Tax Period that ended before 1 January 2026.
The deadline for such an application is:
31 October 2026, provided the relevant exemption conditions were met for that Tax Period.
Because this deadline arrives considerably earlier than the 31 December transitional dates contained elsewhere in the Decision, affected entities should review their position promptly.
Where the FTA approves an exemption application under the relevant provisions of Article 3, the general rule is that the exemption becomes effective from the start of the Tax Period specified in the exemption application.
However, that is not necessarily the final date in every case.
Article 3 allows the FTA to determine an alternative effective date in certain circumstances.
For example, if the Tax Period entered during registration was incorrect, the exemption can instead take effect from the start of the correct Tax Period.
Where an applicant is acquired during a Tax Period by specified categories of persons, the FTA may determine an alternative date so that the exemption begins from a Tax Period starting after all relevant conditions have been fulfilled.
Similarly, if the exemption application refers to an incorrect Tax Period but sufficient information demonstrates that the exemption conditions were satisfied in the following Tax Period, the exemption may begin from the start of that following period.
Where the legislation granting the exemption operates retrospectively, the exemption may instead apply from the beginning of the Tax Period in which the relevant conditions were satisfied.
Article 4 of the new Decision formally repeals FTA Decision No. 7 of 2023 from the effective date of FTA Decision No. 15 of 2026.
Accordingly, exemption applications submitted under the new regime should be reviewed against Decision No. 15 of 2026 rather than relying solely on procedures developed under the previous FTA Decision.
The scope of the Decision is broader than its September 2026 publication date may initially suggest.
Article 5 states that it applies to Tax Periods commencing on or after 1 June 2023, where the exemption application is submitted to the Authority on or after the effective date of the new Decision.
The Decision itself came into effect on 15 September 2026.
This means entities considering an exemption application after that date may need to review earlier Tax Periods through the framework of the new Decision.
The update makes process and timing particularly important.
Entities considering Corporate Tax exemption should determine exactly which provision of Article 4 of the Corporate Tax Law applies to them, verify that the underlying exemption requirements have been satisfied, confirm their Corporate Tax registration status, establish the relevant Tax Period and then calculate the correct exemption deadline.
Particular attention should be given to the 31 October 2026, 31 December 2026, and 90-Business-Day deadlines contained in the Decision.
Entities forming part of a wider ownership structure should also review whether the exemption application depends on the approval of another entity’s exemption application.
Corporate Tax exemption can involve more than confirming whether an organization appears to fall within an exempt category. Registration status, the applicable Tax Period, ownership arrangements, supporting information, and the timing of the exemption application can all affect the process.
Ripple Accountants can assist businesses and organizations with reviewing their Corporate Tax position, assessing applicable exemption requirements, checking registration obligations, determining relevant application deadlines and preparing for the exemption process.
If your organization may qualify for a UAE Corporate Tax exemption or you are uncertain whether one of the new 2026 deadlines applies, contact Ripple Accountants before submitting the application so the position can be reviewed against the applicable legislation and your specific circumstances.
The Decision became effective on 15 September 2026. It was issued on 8 September 2026.
For the persons specifically referred to in Article 2 of the Decision, Corporate Tax registration is required in accordance with the applicable registration timeline. Certain categories may then apply for exemption after the FTA has approved their Tax Registration and where the exemption conditions are satisfied.
For the categories covered by Article 3(1), the application must be made after the relevant Tax Period ends and generally no later than 90 Business Days after the end of that Tax Period.
Yes. Although an approved exemption will generally apply from the beginning of the Tax Period specified in the application, the Decision allows the FTA to determine a different effective date in specified circumstances, including incorrect Tax Periods and cases where exemption conditions were satisfied at a different time.
Yes. FTA Decision No. 7 of 2023 is repealed from the effective date of FTA Decision No. 15 of 2026.
FTA Decision No. 15 of 2026 introduces an updated procedural framework for UAE Corporate Tax exemption applications. Its most important practical changes include the requirement for relevant persons to complete Corporate Tax registration before applying for exemption, the introduction of a general 90-Business-Day application period, specific transitional deadlines ending on 31 October 2026 and 31 December 2026, and clearer rules governing when an approved exemption takes effect. Because the Decision can apply to Tax Periods beginning as far back as 1 June 2023 for applications submitted after the new Decision took effect, potentially exempt entities should review both their historical and current Corporate Tax position rather than considering only future Tax Periods.
Disclaimer: This article is provided for general informational purposes only and should not be treated as legal, tax or professional advice. The uploaded version of FTA Decision No. 15 of 2026 expressly identifies itself as an unofficial translation. Individual Corporate Tax exemption eligibility and filing obligations depend on the relevant provisions of the UAE Corporate Tax Law, related Cabinet and Ministerial Decisions, FTA guidance and the particular facts of each entity. Professional advice should be obtained before taking or refraining from action based on this update.
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
 Compliance
Do your group companies share loans, employees, management services, office space or other resources? If so, these arrangements may create related party…
Read article Compliance
Is your UAE business profitable on paper but still struggling to maintain enough cash for salaries, suppliers, tax payments or expansion? This…
Read article Bookkeeping
Are your business transactions properly recorded every month, or do you only review your accounts when a tax filing or financial deadline…
Read articlePage 7 of 44
Book a free consultation and get clear answers for your business.
0 Comments