Fraud Prevention: Segregation of Duties and Internal Controls
Z Zobia August 1, 2026 13 min read
Introduction
Fraud can affect businesses of any size, leading to financial losses, damaged reputations, and compliance issues. A strong fraud prevention strategy helps reduce these risks by establishing clear processes, assigning responsibilities, and monitoring financial activities. Two of the most effective tools for preventing fraud are segregation of duties and internal controls.
What Is Fraud Prevention in Business?
Fraud prevention refers to the policies, procedures, and systems that businesses use to reduce the risk of financial fraud, operational misconduct, and unauthorized activities. It focuses on stopping fraud before it occurs by strengthening internal processes and increasing oversight.
An effective fraud prevention strategy combines strong internal controls, employee accountability, regular monitoring, and continuous risk assessments. Businesses that invest in fraud prevention are better prepared to protect their finances, maintain compliance, and build trust with stakeholders.
Common Types of Business Fraud
Businesses may face several forms of fraud, including:
Employee theft of cash or company assets
Financial statement fraud
Payroll fraud
Vendor or procurement fraud
Expense reimbursement fraud
Inventory theft
Accounts payable fraud
Cyber fraud targeting financial systems
Invoice manipulation
Unauthorized bank transactions
Each type of fraud can result in financial losses, legal penalties, and operational disruptions if proper controls are not in place.
Internal Fraud vs. External Fraud
Internal fraud is committed by employees, managers, or individuals within the organization. It often involves misuse of company resources, manipulation of accounting records, or unauthorized payments. External fraud is carried out by individuals or organizations outside the business. Examples include phishing attacks, fake vendors, identity theft, payment scams, and cyberattacks targeting financial information.
Both types of fraud require different preventive measures, but strong internal controls help reduce exposure to both.
What Are Internal Controls?
Internal controls are the policies, procedures, and processes that help businesses safeguard assets, ensure accurate financial reporting, maintain regulatory compliance, and improve operational efficiency.
An effective internal control system reduces the likelihood of fraud and accounting errors while providing management with reliable financial information for decision-making.
Internal controls should be integrated into daily business operations rather than treated as occasional compliance activities. They establish accountability, define approval processes, and create clear documentation for every financial transaction.
Main Objectives of Internal Controls
Strong internal controls help businesses achieve several important objectives:
Protect company assets from theft, misuse, or unauthorized access.
Prevent financial fraud and operational misconduct.
Detect accounting errors before they become significant problems.
Improve the accuracy and reliability of financial reporting.
Ensure compliance with accounting standards and legal regulations.
Strengthen accountability across departments.
Support better financial decision-making.
Reduce operational risks.
Maintain complete documentation for every transaction.
Improve business efficiency through standardized procedures.
What Is Segregation of Duties (SoD)?
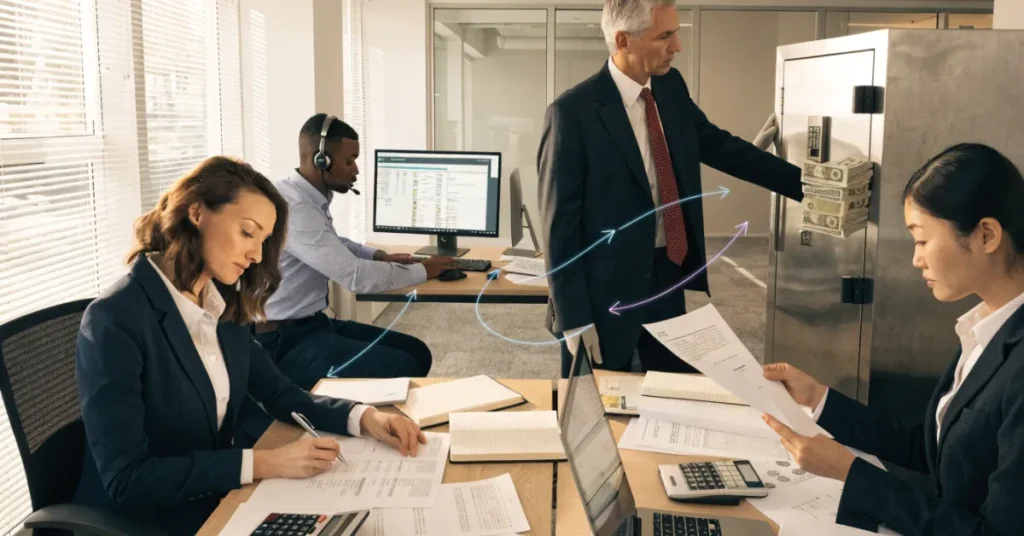
Segregation of duties (SoD) is one of the most important internal control principles in accounting and finance. It involves dividing financial responsibilities among multiple employees so that no single individual controls every stage of a transaction. Instead of allowing one person to authorize, process, record, and reconcile a payment, these responsibilities are assigned to different employees. This separation makes it much more difficult for fraud to occur without being detected.
Segregation of duties also reduces the risk of accidental errors because multiple people review financial transactions throughout the process. Businesses of all sizes can apply this principle by separating critical accounting functions according to available staffing resources.
A well-designed segregation of duties system strengthens fraud prevention, improves transparency, and increases confidence in financial reporting.
The Four Critical Responsibilities That Should Be Separated
Authorization
The employee responsible for authorization approves purchases, payments, refunds, or other financial transactions according to company policies.
Custody of Assets
This responsibility involves managing company assets such as cash, inventory, checks, bank accounts, or valuable equipment. Employees responsible for asset custody should not approve or record related transactions.
Record Keeping
Record keeping includes entering accounting transactions, maintaining financial records, processing invoices, and updating accounting software. Employees responsible for bookkeeping should not have authority to approve payments or handle company assets.
Reconciliation
Reconciliation involves reviewing financial records, comparing bank statements with accounting records, identifying discrepancies, and confirming that transactions are complete and accurate. Independent reconciliation provides an additional layer of fraud detection and strengthens the overall internal control system.
How Segregation of Duties Prevents Fraud
Segregation of duties strengthens fraud prevention by ensuring that no single employee controls an entire financial process. When responsibilities are divided, every transaction passes through multiple levels of review, making unauthorized activities easier to detect and harder to conceal.
This approach also reduces human errors because different employees verify financial information before transactions are finalized. Combined with strong internal controls, segregation of duties improves accountability, financial reporting accuracy, and regulatory compliance.
Example 1: Cash Receipts
One employee receives customer payments, another records the transactions in the accounting system, and a different employee performs the bank reconciliation. This separation reduces the risk of cash theft and inaccurate financial records.
Example 2: Vendor Payments
The purchasing department creates purchase orders, the finance team verifies invoices, management approves payments, and another employee processes bank transfers. Multiple approval stages help prevent duplicate payments, fake invoices, and unauthorized transactions.
Example 3: Payroll Processing
The HR department maintains employee records, payroll staff calculate salaries, management approves payroll, and finance releases payments. Separating these responsibilities helps prevent ghost employees, unauthorized salary increases, and payroll fraud.
Example 4: Inventory Management
Warehouse staff manage inventory, purchasing officers order stock, accounting records inventory transactions, and management reviews inventory reports. Regular stock counts and reconciliations reduce inventory theft and reporting errors.
Essential Internal Controls Every Business Should Implement
A strong internal control system protects business assets, improves financial accuracy, and reduces fraud risk. Every business should establish standardized procedures that apply across all financial operations.
Authorization Controls
Implement clear authorization policies for financial activities, including:
Define approval limits based on employee roles.
Require management approval for high-value transactions.
Restrict unauthorized purchasing.
Document every approval.
Review approval authority regularly.
Approval Hierarchy
Create a structured approval workflow to ensure accountability.
Assign approval levels according to transaction value.
Require multiple approvals for significant expenditures.
Separate approval authority across departments.
Maintain electronic approval records.
Update approval responsibilities when organizational changes occur.
Bank Reconciliation
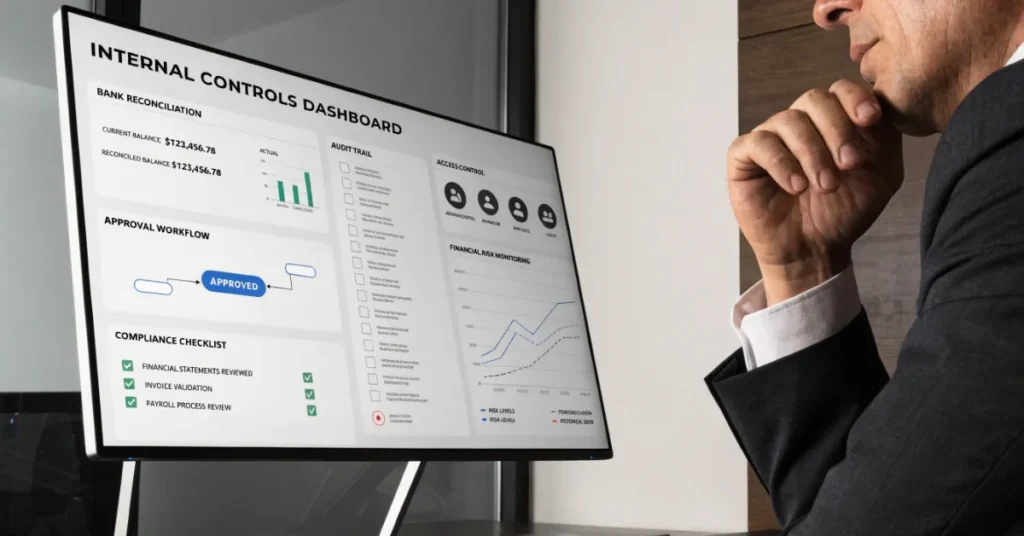
Perform monthly bank reconciliations to compare accounting records with bank statements. Investigate differences immediately and resolve discrepancies before preparing financial reports. Regular reconciliation helps identify unauthorized withdrawals, duplicate payments, and accounting errors.
Dual Authorization
Require two authorized individuals to approve high-risk transactions such as large bank transfers, vendor payments, refunds, and payroll releases. Dual authorization reduces the possibility of fraudulent payments.
Audit Trail
Maintain a complete audit trail for every financial transaction. Accounting systems should record who created, modified, approved, or deleted financial records. An audit trail supports fraud investigations and improves transparency.
Physical Asset Controls
Protect physical assets through appropriate security measures.
Restrict access to cash and inventory.
Lock storage areas.
Use surveillance where necessary.
Perform regular inventory counts.
Monitor valuable equipment.
Access Controls
Limit access to accounting systems based on employee responsibilities.
Use role-based permissions.
Require strong passwords.
Enable multi-factor authentication.
Remove access for former employees immediately.
Review user permissions periodically.
Documentation Controls
Maintain complete supporting documents for every transaction, including invoices, purchase orders, contracts, receipts, and payment approvals. Proper documentation improves financial reporting and simplifies audits.
Periodic Internal Audits
Conduct regular internal audits to evaluate compliance with company policies and identify weaknesses in internal controls. Independent reviews help detect fraud risks before they become significant issues.
Financial Reporting Reviews
Management should review financial statements regularly to identify unusual trends, unexpected expenses, duplicate payments, or inconsistencies. Timely reviews improve financial accuracy and support informed decision-making.
Preventive, Detective, and Corrective Controls Explained
An effective internal control framework combines preventive, detective, and corrective controls. Each serves a different purpose in fraud risk management.
Preventive Controls
Preventive controls stop fraud before it occurs by reducing opportunities for unauthorized activities.
Examples include:
Segregation of duties
Authorization controls
Approval workflows
Access restrictions
Employee background checks
Password policies
Vendor verification
Purchase approval procedures
Detective Controls
Detective controls identify fraud or errors after they occur so corrective action can be taken quickly.
Examples include:
Bank reconciliations
Internal audits
Inventory counts
Financial statement reviews
Exception reports
Audit trail monitoring
Variance analysis
Surprise cash counts
Corrective Controls
Corrective controls resolve issues identified through monitoring and strengthen future fraud prevention efforts.
Examples include:
Updating internal control procedures
Recovering financial losses
Employee retraining
Revising approval processes
Improving accounting software controls
Implementing disciplinary actions
Strengthening cybersecurity measures
Common Weaknesses That Increase Fraud Risk
Weak internal controls create opportunities for fraud and financial mismanagement. Businesses should regularly evaluate their processes to identify vulnerabilities.
Common weaknesses include:
One employee controls an entire financial process.
Transactions are processed without approvals.
Financial records lack supporting documentation.
Bank reconciliations are delayed or skipped.
Employees share passwords or system accounts.
User access permissions are not reviewed regularly.
Addressing these weaknesses significantly reduces fraud risk and improves financial control.
Internal Controls for Different Business Functions
Different departments require specific internal controls to reduce operational and financial risks.
Accounts Payable Controls
Accounts payable controls ensure that vendor payments are accurate, approved, and supported by valid documentation. Businesses should verify supplier details, match purchase orders with invoices, require management approval before payment, and review outstanding payables regularly to prevent duplicate or fraudulent payments.
Accounts Receivable Controls
Businesses should issue invoices promptly, monitor customer balances, reconcile incoming payments with accounting records, and investigate overdue accounts. Regular reviews improve cash flow and reduce the risk of payment errors or unauthorized adjustments.
Payroll Controls
Payroll controls include maintaining accurate employee records, restricting payroll system access, approving salary changes, reviewing overtime, and reconciling payroll reports before processing payments. These measures help prevent payroll fraud and unauthorized compensation.
Inventory Controls
Inventory should be protected through restricted warehouse access, barcode tracking, regular stock counts, inventory reconciliations, and management review of inventory adjustments. Strong inventory controls reduce theft and improve reporting accuracy.
Procurement Controls
Procurement controls require approved purchase requests, competitive vendor selection, purchase order approval, invoice verification, and segregation of purchasing and payment responsibilities. These controls reduce procurement fraud and improve spending transparency.
Cash Management Controls
Businesses should limit cash handling responsibilities, reconcile cash balances daily, require approval for cash disbursements, monitor bank accounts regularly, and investigate unusual transactions immediately. Effective cash management controls protect one of the organization’s most valuable assets.
How Technology Strengthens Fraud Prevention
Technology plays an important role in improving fraud prevention and strengthening internal controls. Modern accounting systems automate routine tasks, monitor financial activities, and provide greater visibility into business transactions. Automation reduces manual errors while making suspicious activities easier to identify.
Businesses can improve fraud risk management by implementing:
Cloud accounting software with secure user access
Role-based permissions for employees
Multi-factor authentication (MFA)
Automated approval workflows
Digital audit trails
AI-powered fraud detection tools
Real-time financial reporting dashboards
Automated bank reconciliation
Continuous transaction monitoring
Secure document management systems
Using technology alongside segregation of duties creates a stronger internal control system and improves financial accuracy.
Fraud Prevention Best Practices for SMEs
Small and medium-sized businesses often operate with limited staff, making segregation of duties more challenging. Even with smaller teams, businesses can implement practical controls to reduce fraud risk.
Best practices include:
Separate accounting and payment responsibilities whenever possible.
Perform monthly bank reconciliations.
Review financial reports regularly.
Verify new vendors before making payments.
Require approval for significant expenses.
Rotate employee responsibilities periodically.
Conduct surprise internal reviews.
Restrict access to financial systems.
Enable multi-factor authentication.
Maintain complete documentation for all transactions.
Monitor unusual financial activity.
Train employees to recognize fraud risks.
Review user access permissions regularly.
Encourage employees to report suspicious activities.
Update internal control procedures as the business grows.
COSO Internal Control Framework Explained
The COSO Internal Control Framework is one of the most widely used frameworks for designing and evaluating internal control systems. It helps businesses manage risk, improve governance, and strengthen fraud prevention.
Five Components of the COSO Framework
Control Environment: Establishes ethical standards, accountability, and management oversight.
Risk Assessment: Identifies and evaluates financial and operational risks.
Control Activities: Implements policies and procedures that reduce identified risks.
Information and Communication: Ensures accurate financial information is shared with the appropriate people.
Monitoring Activities: Continuously evaluates the effectiveness of internal controls and identifies areas for improvement.
Applying these components helps businesses maintain effective financial controls and support long-term compliance.
Signs That Your Business Needs Stronger Internal Controls
Weak internal controls often reveal themselves through recurring operational and financial issues. Addressing these warning signs early helps prevent larger problems.
Common indicators include:
Frequent accounting errors
Missing invoices or receipts
Cash shortages
Duplicate vendor payments
Unexplained inventory losses
Unauthorized transactions
Delayed bank reconciliations
Large manual journal entries
Unusual employee expense claims
Vendors with incomplete information
Late financial reporting
Employees refusing to take leave
Weak password management
Poor documentation of approvals
Increasing customer or supplier complaints
How Ripple Accountants Can Help
Ripple Accountants assists businesses in strengthening financial processes through professional accounting, bookkeeping, and compliance services. Our team helps organizations evaluate existing internal controls, identify control weaknesses, and implement practical solutions that improve financial accuracy and reduce fraud risk.
Our services include:
Internal control assessments
Accounting and bookkeeping services
Financial reporting support
Internal audit assistance
Risk assessment and compliance reviews
Corporate tax services
VAT compliance services
Accounting system improvements
Financial process optimization
Whether you are establishing internal controls for a new business or improving existing financial processes, Ripple Accountants can help build a more secure and efficient accounting system.
Segregation of duties is an internal control principle that divides financial responsibilities among different employees. One person should not authorize, process, record, and reconcile the same transaction. This reduces the risk of fraud and improves financial accuracy.
Why are internal controls important?
Internal controls protect business assets, improve financial reporting, reduce accounting errors, support regulatory compliance, and strengthen fraud prevention. They also improve operational efficiency and management oversight.
Can small businesses implement segregation of duties?
Yes. Small businesses can divide key financial responsibilities among available staff, require management approval for significant transactions, use accounting software with approval workflows, and perform independent reviews to strengthen internal controls.
What is the difference between preventive and detective controls?
Preventive controls reduce the chance of fraud occurring, while detective controls identify fraud or errors after they happen. Businesses should use both types of controls as part of a complete fraud prevention strategy.
How often should internal controls be reviewed?
Businesses should review internal controls at least annually. Reviews should also be conducted after significant organizational changes, new system implementations, business expansion, or when fraud risks increase.
What are examples of internal controls?
Examples include segregation of duties, approval hierarchies, bank reconciliations, dual authorization, audit trails, access controls, inventory counts, internal audits, vendor verification, and financial statement reviews.
Conclusion
Fraud prevention requires more than policies alone. Businesses need effective internal controls, clear segregation of duties, regular monitoring, and continuous improvement to reduce financial risk. Dividing responsibilities, implementing approval procedures, maintaining accurate documentation, and reviewing financial activities regularly help create a stronger control environment.
Disclaimer: This article is for general informational purposes only and should not be considered legal, tax, audit, or financial advice. Businesses should seek professional guidance based on their specific circumstances and applicable regulations.
Share
Free Consultation
Have a tax or accounting question?
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
0 Comments
No comments yet. Be the first to start the conversation.
Non-profit organizations play a vital role in supporting communities, advancing education, promoting healthcare, protecting the environment, and delivering humanitarian aid across the…
Businesses have traditionally relied on financial reports such as revenue, profit, cash flow, and expenses to evaluate performance. While these metrics remain…
Auditing different types of businesses is essential because every industry operates with unique financial processes, regulations, and risks. A manufacturing company manages…



0 Comments