Key Differences Between Bookkeepers and Accountants: Complete Business Guide
Managing business finances is one of the most important responsibilities for any business owner. Whether you run a startup, a small business,…
Read article
Are your Shopify or Amazon sales growing, but your books still do not show exactly where the money is going?
E-commerce businesses can generate hundreds or thousands of transactions every month. But sales reports from Shopify, Amazon, payment gateways, banks, and delivery providers do not automatically become accurate accounting records.
For UAE e-commerce businesses, good bookkeeping means more than recording sales. You need to track revenue, inventory, payment fees, refunds, shipping costs, VAT, expenses, and bank movements in a way that gives you a reliable picture of profitability and supports your tax and compliance obligations.
Lets learn what UAE e-commerce businesses should track and how regular bookkeeping can make financial management easier.
A traditional business may receive a limited number of invoices and payments each month. An online store can have hundreds of individual orders across several sales channels.
For example, an e-commerce business may sell through:
Each channel can produce different reports, fees, settlement dates, refunds, and transaction references.
This is why ecommerce bookkeeping UAE should be based on reconciliation rather than simply importing total sales into accounting software.
A business may have AED 100,000 in reported online sales but receive a lower amount in its bank account because payment gateway charges, marketplace commissions, refunds, delivery charges, or other adjustments have already been deducted.
Without proper reconciliation, these differences can make revenue and expenses difficult to understand.
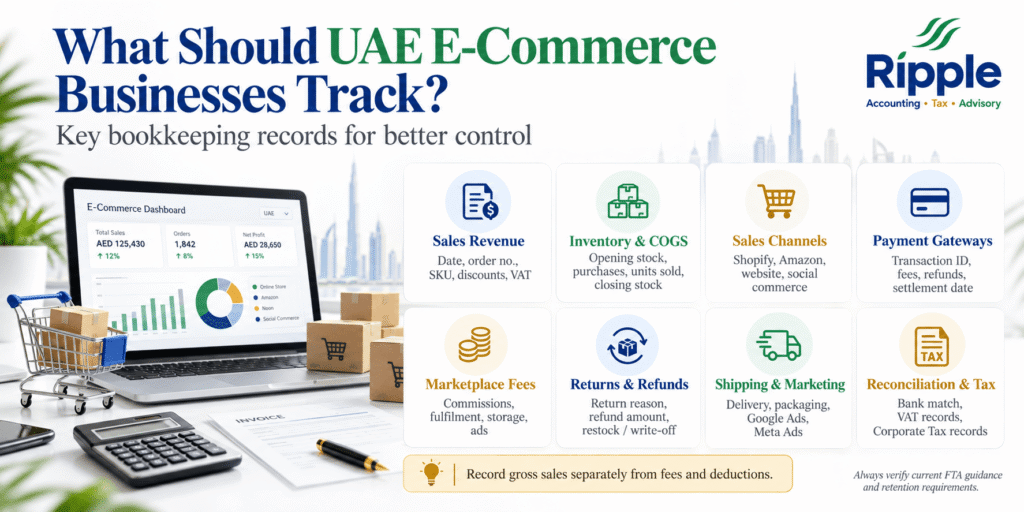
A practical bookkeeping system should capture the complete financial journey of each sale, from the customer order to the final settlement in the business bank account.
Start by recording your gross sales accurately.
Your records should ideally show:
Do not rely only on the amount deposited into your bank account. The bank settlement may represent net proceeds after deductions.
For example, if customers purchase AED 20,000 worth of products and a marketplace deducts AED 1,500 in commissions and other charges, the bank may receive AED 18,500. Your bookkeeping should distinguish the original sales from the expenses or fees deducted.
Inventory is one of the most important areas of ecommerce bookkeeping UAE.
You need to know not only how much you sold but also how much stock remains and what the sold inventory cost the business.
Track:
This information helps you calculate gross profit.
For example:
Sales revenue – Cost of goods sold = Gross profit
If your online store generates strong sales but inventory costs are increasing faster than revenue, your actual profitability may be much lower than expected. Regular stock counts can also help identify differences between accounting records and physical inventory.
The Federal Tax Authority’s guidance for VAT records includes inventory records and statements showing quantities and values, as well as stock-count records.
If your business uses multiple platforms, keep separate records for each sales channel. For example, your bookkeeping system could distinguish:
This makes it easier to compare channel performance. It can also reveal issues such as one marketplace generating significant revenue but producing lower margins because of higher commissions, advertising costs, fulfilment charges, or returns.
Payment gateways should be reconciled regularly with your sales records and bank statements.
Track:
A common bookkeeping mistake is recording only the net amount received in the bank.
Suppose a customer pays AED 1,000 and the payment provider deducts AED 25 as a processing fee. If you record only AED 975 as sales, your revenue will be understated and the payment fee may disappear from your expense records.
Instead, the accounting records should distinguish the gross transaction from the related payment processing cost.
Amazon and other marketplaces may deduct several charges before transferring funds to your business. Depending on the platform and arrangement, these can include:
These charges should not simply be ignored because they were deducted before settlement. Recording them separately gives you a clearer view of the true cost of selling through each platform.
E-commerce businesses should maintain a clear record of returns and refunds. Track:
Returns can affect both revenue and inventory.
For example, a refunded product may come back into sellable stock, while another returned item may be damaged and need to be written off. Treating both situations identically can distort inventory and profitability figures.
Shipping expenses can have a significant impact on e-commerce margins. Your bookkeeping should capture costs such as:
If customers are charged separately for shipping, record the relevant income and costs consistently so you can determine whether delivery operations are profitable.
Online businesses often spend heavily on digital marketing. Keep records of expenses from platforms and marketing providers such as:
Separating advertising expenses from general operating costs helps owners measure customer acquisition costs and evaluate whether marketing spending is generating sufficient returns.
Bank reconciliation is one of the most important monthly bookkeeping controls for an e-commerce company. Your accountant or finance team should compare the accounting records with the actual bank statement and investigate differences.
The reconciliation should identify:
This is particularly important when a business uses several payment methods.
A bank balance alone does not tell you whether all online sales have been properly recorded.
VAT-registered e-commerce businesses should maintain records that support their VAT reporting.
The Federal Tax Authority provides specific guidance on e-commerce supplies. Under the relevant criteria, goods or services may qualify as supplies through an electronic commerce medium where they are advertised and ordered through an electronic commerce medium and meet the applicable delivery or service conditions.
For qualifying e-commerce supplies, UAE VAT reporting can involve reporting standard-rated e-commerce supplies according to the Emirate in which the goods are received. The FTA also states that supporting documents and information should be maintained to prove the relevant Emirate for such supplies.
This makes accurate transaction-level records especially important for businesses operating across different Emirates.
Businesses should also retain VAT invoices and other required records for the applicable retention period. The FTA states that taxable persons must retain VAT invoices issued and received for at least five years.
For detailed requirements, businesses should refer to the latest FTA guidance and applicable UAE tax legislation.
E-commerce businesses subject to UAE Corporate Tax should also maintain accounting records and supporting documents needed to substantiate their tax position.
The FTA states that Corporate Tax records and documents should generally be kept for at least seven years following the end of the relevant Tax Period.
This means e-commerce businesses should have an organised recordkeeping process for items such as:
The FTA’s legislation page also lists FTA Decision No. 4 of 2026, which sets rules and requirements for maintaining information contained in accounting records and commercial books.
Because requirements can change, businesses should verify the latest applicable FTA guidance when setting up or reviewing their recordkeeping process.
A UAE e-commerce business can use the following checklist each month:
| Area | What to Check |
| Sales | Shopify, Amazon and other platform sales |
| Orders | Completed, cancelled and refunded orders |
| Inventory | Purchases, stock movements and closing inventory |
| COGS | Cost of products sold |
| Payment gateways | Gross payments, fees and settlements |
| Marketplaces | Commissions, fulfilment and other deductions |
| Refunds | Customer refunds and returned goods |
| Shipping | Courier, delivery and packaging costs |
| Advertising | Google, Meta and other marketing expenses |
| Bank | Deposits, withdrawals and bank charges |
| VAT | Output VAT, input VAT and supporting records |
| Corporate Tax | Accounting records and supporting documents |
| Reconciliation | Platform-to-accounting and bank-to-accounting differences |
The ideal frequency depends on the size and transaction volume of the business. For a small store with relatively few transactions, monthly bookkeeping may be sufficient.
A growing e-commerce business with hundreds of orders across multiple platforms may benefit from weekly or more frequent reconciliation.
Waiting until the end of the financial year can make it much harder to identify missing transactions, incorrect inventory values, unexplained bank deposits, or unrecorded platform fees.
Regular bookkeeping gives business owners a more current view of:
Managing an online store already involves products, customers, suppliers, fulfilment, marketing and multiple sales platforms. Bookkeeping should give you clarity rather than become another operational burden.
At Ripple Accounting, Tax & Advisory, businesses can get support with accounting and bookkeeping processes designed around their financial operations.
Support can include:
If your business sells through Shopify, Amazon, a direct website or multiple e-commerce channels, a structured bookkeeping process can help you understand where revenue is coming from and where margins are being lost.
Need help organizing your e-commerce accounts? Contact Ripple Accounting, Tax & Advisory for tailored accounting and bookkeeping support.
Explore Ripple’s Accounting & Bookkeeping Services
E-commerce businesses should track sales, inventory, cost of goods sold, payment gateway fees, marketplace commissions, refunds, shipping, advertising, operating expenses, bank transactions and relevant VAT and Corporate Tax records.
The accounting principles are similar, but Shopify businesses often have a higher volume of transactions and multiple payment and settlement flows. Shopify sales, payment processing fees, refunds and bank settlements should therefore be reconciled properly.
Amazon sales should generally be reconciled using detailed marketplace reports rather than recording only the net amount deposited into the bank. Sales, commissions, fulfilment charges, refunds and other relevant deductions should be appropriately reflected in the accounting records.
The FTA states that records and documents should generally be kept for at least seven years following the end of the relevant Tax Period.
Yes. Ripple Accounting, Tax & Advisory provides accounting and bookkeeping support for UAE businesses, including transaction recording, reconciliation and financial reporting. Businesses can discuss their specific e-commerce bookkeeping requirements with the Ripple team.
E-commerce bookkeeping is not simply about recording how much money entered your bank account. A reliable system should connect sales platforms, payment gateways, inventory, expenses, refunds and bank transactions into one accurate financial picture. For UAE e-commerce businesses, keeping these records organised can make it easier to monitor profitability, prepare financial reports and support VAT and Corporate Tax compliance. The earlier your business establishes a consistent reconciliation process, the easier it becomes to identify financial issues before they turn into bigger problems.
Need help organising your e-commerce accounts? Contact Ripple Accounting, Tax & Advisory for tailored accounting and bookkeeping support.
Disclaimer: This article provides general information for UAE e-commerce businesses and should not be treated as legal, tax or accounting advice. UAE tax and regulatory requirements may vary according to the business structure, activities and circumstances. Always verify current requirements with the Federal Tax Authority or a qualified UAE tax professional.
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
 Bookkeeping
Managing business finances is one of the most important responsibilities for any business owner. Whether you run a startup, a small business,…
Read article Bookkeeping
Businesses no longer have the luxury of waiting until the end of the month to understand their financial performance. Markets change quickly,…
Read article Bookkeeping
The education sector in the UAE has experienced remarkable growth over the past decade. From private schools and universities to vocational training…
Read articlePage 56 of 58
Book a free consultation and get clear answers for your business.
0 Comments