Backlog Accounting UAE: Cleanup Process & Tax Filing Timeline
M Maria August 28, 2026 12 min read
What happens when your UAE Corporate Tax filing deadline is approaching, but your accounting records are months behind?
For many UAE SMEs, delayed bookkeeping can turn Corporate Tax preparation into a stressful process. Missing invoices, unreconciled bank accounts, incorrect entries and incomplete financial records can make it difficult to determine the business’s actual profit and taxable income.
Backlog accounting UAE helps bring these records up to date before the tax return is prepared. The Federal Tax Authority (FTA) expects taxpayers to maintain financial statements and supporting records that substantiate the information reported in their Corporate Tax returns.
What Is Backlog Accounting in the UAE?
Backlog accounting UAE refers to the process of bringing incomplete, delayed or outdated accounting records up to date.
A business may have a backlog because its previous accountant stopped working, bookkeeping was neglected during a busy period, invoices were not recorded, bank accounts were not reconciled, or financial information was maintained across different spreadsheets and systems.
Backlog accounting is also commonly described as:
Catch-up bookkeeping
Historical bookkeeping
Accounting cleanup
Bookkeeping cleanup
Catch-up accounting
The objective is not simply to enter old transactions into accounting software. A proper cleanup should produce reliable and organized financial records that management can use and that can support applicable tax compliance.
This becomes particularly important before Corporate Tax filing in the UAE, because the accounting records form an important basis for determining taxable income.
Why Should You Clean Up Your Books Before Corporate Tax Filing?
Corporate Tax calculations should be based on reliable financial information. The FTA explains that taxable income is generally based on accounting net profit or loss after the adjustments required under the Corporate Tax Law.
If the underlying accounting records are incomplete, several problems can arise.
Incorrect profit figures: If sales or expenses are missing, the reported profit may not reflect the actual financial performance of the business.
Missing deductible expenses: Poor records may result in legitimate business expenses being omitted from the accounts because supporting documents cannot be located or transactions were never recorded.
Incorrect account balances: Unreconciled bank accounts, customer balances, supplier accounts and loans can result in inaccurate financial statements.
Corporate Tax calculation errors: Because taxable income starts from accounting results and is then adjusted according to the applicable tax rules, inaccurate accounting records can complicate the Corporate Tax calculation.
Difficulty supporting the tax return: The FTA states that taxpayers should maintain financial statements and documents supporting the information included in their Corporate Tax returns.
The FTA also reminded taxpayers in 2025 that relevant records and supporting documents must be retained for at least seven years following the end of the relevant Tax Period.
Therefore, accounting cleanup should ideally be completed well before the Corporate Tax filing deadline rather than treated as a last-minute task.
Signs Your Business Has an Accounting Backlog
Not every business realizes that its books are behind. You may have an accounting backlog if:
Bank accounts have not been reconciled for several months.
Sales invoices are missing from the accounting system.
Supplier bills have not been recorded.
Customer balances do not match your records.
Expenses are sitting in uncategorized accounts.
Your accounting software contains duplicate transactions.
Previous accounting records were maintained in spreadsheets.
Opening balances are incorrect.
Loan or credit-card balances do not match statements.
VAT accounts have not been reconciled.
Payroll entries are incomplete.
You cannot generate a reliable trial balance.
Your accountant cannot prepare accurate financial statements.
Management does not know the company’s actual profit or cash position.
If several of these conditions apply, the business may need bookkeeping cleanup UAE services before proceeding with tax preparation.
Backlog Accounting Cleanup Process
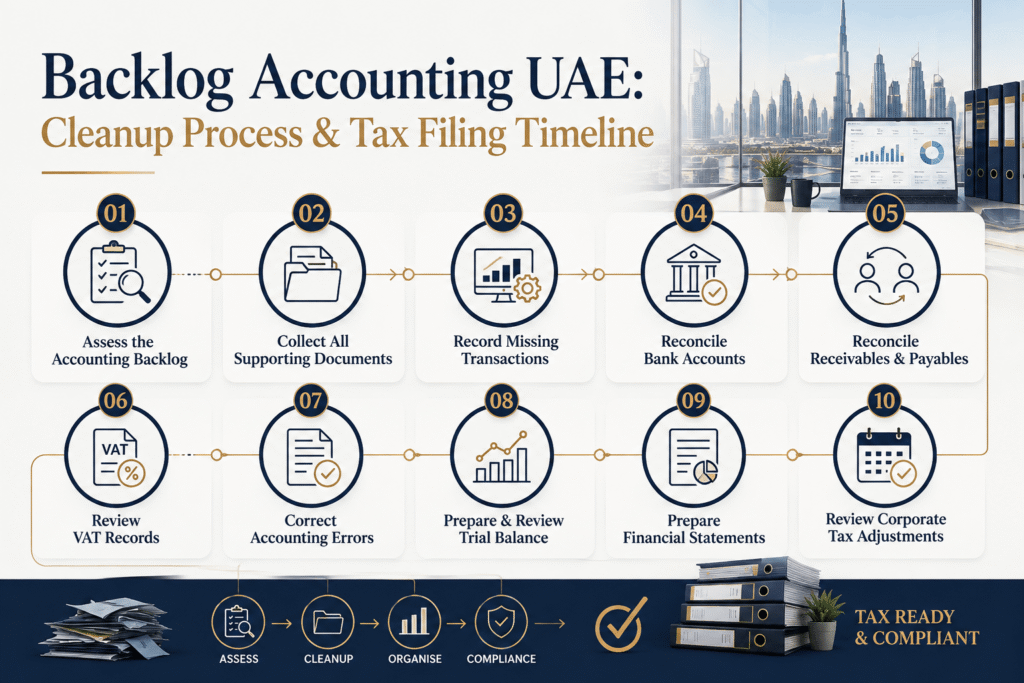
A structured approach makes accounting cleanup more manageable. Instead of entering transactions randomly, businesses should work through the backlog systematically.
1. Assess the Accounting Backlog
The first step is to determine exactly what is incomplete.
Review:
The last completed accounting period
Number of months outstanding
Number of bank accounts
Number of transactions
Existing accounting software
Available financial documents
Previous financial statements
VAT records and returns
Payroll records
Loans and financing
Fixed assets
Accounts receivable and payable
For example, if bookkeeping was last completed in December 2025 and the current accounting period is August 2026, the business may have approximately eight months of records to review.
The cleanup timeline will depend heavily on the number and complexity of transactions during those months.
2. Collect All Supporting Documents
The next stage is document collection. Depending on the business, the accounting team may need:
Bank statements
Sales invoices
Purchase invoices
Receipts
Credit notes
Debit notes
Expense records
Payroll information
WPS-related records
Loan statements
Credit-card statements
Fixed-asset invoices
Inventory records
Previous VAT returns
Previous financial statements
Lease agreements
Relevant contracts
The FTA specifically emphasizes the importance of maintaining records and documentation that support information reported in Corporate Tax returns. If documents are missing, the accounting team should identify those gaps rather than simply guessing the accounting treatment.
3. Record Missing Transactions
Once the documents have been organized, missing transactions can be entered into the accounting system.
This may include:
Sales
Purchases
Operating expenses
Bank charges
Payroll
Asset purchases
Loan transactions
Owner/shareholder transactions
Foreign-currency transactions
Other relevant adjustments
Transactions should be classified into the appropriate accounts rather than placed into miscellaneous categories simply to complete the books.
For example, if a company purchased office equipment for AED 15,000, the transaction may need to be considered as a fixed asset rather than an ordinary office expense, depending on the applicable accounting treatment.
4. Reconcile Bank Accounts
Bank reconciliation is one of the most important stages of an accounting cleanup UAE project.
The accounting records should be compared against actual bank statements to identify:
Missing transactions
Duplicate entries
Incorrect amounts
Unpresented payments
Unrecorded receipts
Bank charges
Transfers between accounts
Incorrect opening balances
Every bank account should be reviewed for the relevant period.
Businesses with multiple accounts may need additional time because each account requires separate reconciliation.
5. Reconcile Receivables and Payables
The cleanup should also examine money owed by customers and money owed to suppliers.
Accounts receivable review
Check:
Outstanding customer invoices
Customer payments
Credit notes
Duplicate invoices
Old balances
Unallocated receipts
Accounts payable review
Check:
Supplier invoices
Supplier payments
Credit notes
Duplicate bills
Outstanding balances
Unrecorded purchases
This process helps management understand whether reported receivables and payables represent genuine outstanding balances.
6. Review VAT Records
If the company is VAT registered, the accounting cleanup should include a review of VAT-related balances and transactions.
The review may cover:
Output VAT
Input VAT
VAT control accounts
VAT return figures
Tax invoices
Credit notes
VAT payment records
If historical accounting errors affect previously submitted VAT returns, the appropriate corrective process should be assessed separately rather than simply changing historical records without documentation.
This is particularly important when a business is simultaneously preparing its accounting records for Corporate Tax.
7. Correct Accounting Errors
Backlog bookkeeping often reveals errors in previous records.
Common examples include:
Duplicate transactions
Personal expenses posted as business expenses
Business expenses posted to incorrect accounts
Missing bank transactions
Incorrect opening balances
Incorrect treatment of loans
Incorrect fixed-asset classification
Unreconciled intercompany transactions
Corrections should be properly documented so that the final accounts provide a clear audit trail.
The purpose of cleanup is not to make the numbers “look right.” It is to establish accurate records supported by available evidence.
8. Prepare and Review the Trial Balance
Once transactions and reconciliations are substantially complete, the accounting team can review the trial balance. The trial balance provides an overall view of the ledger balances and helps identify unusual or potentially incorrect balances.
Areas that may require additional review include:
Negative asset balances
Unusually high expenses
Suspense accounts
Large unexplained receivables
Large unexplained payables
Unreconciled VAT balances
Shareholder/current accounts
Loan balances
Retained earnings
Fixed assets
Only after significant accounting issues have been addressed should the financial statements be finalized.
9. Prepare Financial Statements
The cleaned accounting records can then be used to prepare appropriate financial statements. Depending on the business and applicable requirements, these may include:
Statement of profit or loss
Statement of financial position
Cash-flow information
Supporting schedules
The FTA states that taxpayers are expected to prepare and maintain financial statements for the purpose of calculating taxable income.
This is why accurate bookkeeping is closely connected with Corporate Tax compliance.
10. Review Corporate Tax Adjustments
The final accounting profit is not necessarily the same as taxable income. The FTA explains that taxable income is generally determined from accounting net profit or loss after applying the relevant adjustments required by the Corporate Tax Law. These can include items such as exempt income, non-deductible expenses, and certain related-party transactions, depending on the circumstances.
Therefore, businesses should avoid assuming that simply multiplying accounting profit by a tax rate is sufficient.
The Corporate Tax calculation should be reviewed according to the applicable UAE rules and the company’s specific circumstances.
How Long Does Backlog Accounting Take?
There is no universal timeline for backlog accounting UAE projects. The duration depends on transaction volume, number of accounts, quality of documentation and how many months are outstanding.
An indicative planning framework could look like this:
Accounting Backlog
Indicative Cleanup Time
1–3 months
1–2 weeks
3–6 months
2–4 weeks
6–12 months
3–6 weeks
More than 12 months
4–8+ weeks
These are only planning estimates. A business with six months of very high-volume transactions may take longer than a business with twelve months of low-volume bookkeeping.
The availability of documents also makes a major difference.
If bank statements, invoices and expense records are readily available, cleanup can move quickly. If documents need to be collected from multiple employees, suppliers, banks and previous accountants, the timeline may increase.
Can You File Corporate Tax Before Cleaning Up Your Books?
Businesses should be cautious about filing a Corporate Tax return using incomplete or unreliable accounting information. The FTA has emphasized the importance of completing tax records and preparing the documents needed for Corporate Tax filing in advance. It identifies financial records and business information among the materials businesses should have available before beginning the filing process.
The FTA also states that Corporate Tax returns are generally due within nine months from the end of the relevant Tax Period.
For example, a business with a 31 December 2025 year-end would generally have a filing deadline of 30 September 2026, subject to the applicable rules.
Therefore, if your accounting is six or twelve months behind, waiting until the final weeks before the deadline can create unnecessary pressure.
What If You Discover Errors During the Cleanup?
Finding errors during cleanup does not necessarily mean the business has failed to maintain its records. Historical errors can occur for many reasons, especially when bookkeeping has changed between employees, accountants or accounting systems.
The important step is to identify, document and correct relevant errors appropriately. Depending on the issue, the business may need to review:
Accounting entries
VAT returns
Previous financial statements
Corporate Tax records
Supporting documents
Related-party transactions
Tax adjustments
If an error may affect a previously submitted tax return, businesses should obtain appropriate professional tax advice before making corrections.
How to Prevent Another Accounting Backlog
Once the historical backlog has been cleared, the business should establish a regular accounting routine.
Reviewing accounts receivable and payable regularly
Setting a monthly bookkeeping deadline
Keeping tax records organized
Reviewing financial reports every month
Assigning responsibility for document collection
The goal is to make accounting a continuous process rather than something that happens only before tax deadlines.
How Ripple Accountant Can Help With Backlog Accounting in the UAE
Clearing an accounting backlog can be time-consuming when business owners have to reconstruct transactions while also managing daily operations. Ripple Accountant can help UAE businesses bring outdated accounting records up to date by reviewing historical transactions, organizing supporting documents, and recording missing entries. We can also reconcile bank and ledger balances, review receivables and payables, and prepare reliable financial reports.
Contact Ripple Accountant to discuss your accounting cleanup requirements and get professional support for bringing your records up to date.
Email: info@uaetaxcompliance.ae
Phone: +971 52 356 5409
WhatsApp: +971 4 250 0833
Frequently Asked Questions
1. What is backlog accounting?
Backlog accounting is the process of bringing incomplete or outdated financial records up to date. It may involve recording missing transactions, reconciling accounts, correcting errors and preparing financial statements.
2. Why is accounting cleanup important before Corporate Tax filing?
Corporate Tax calculations depend on reliable financial information. Accurate accounting records help businesses determine their accounting profit and make the appropriate tax adjustments.
3 How long does bookkeeping cleanup take?
It depends on the number of months outstanding, transaction volume, number of bank accounts, quality of documentation and complexity of the business. Small backlogs may take a few weeks, while larger historical backlogs can take several weeks or longer.
4. Can an accountant fix several years of bookkeeping?
Yes, historical bookkeeping can generally be reconstructed if sufficient supporting documentation is available. However, larger backlogs require more detailed review and may take considerably longer.
5. What documents are needed for accounting cleanup?
Common documents include bank statements, invoices, receipts, expense records, payroll information, loan statements, VAT returns, financial statements and other records supporting business transactions.
6. Does backlog accounting automatically include Corporate Tax filing?
No. Accounting cleanup and Corporate Tax return preparation are separate scopes of work unless the provider specifically includes both services in its engagement.
Conclusion
A bookkeeping backlog should not be left until the last few weeks before a UAE Corporate Tax deadline. Incomplete records can make it difficult to determine the company’s actual financial position, prepare reliable financial statements and calculate taxable income accurately.
Disclaimer: This article is provided for general informational and educational purposes only. Businesses should review their specific circumstances and consult a qualified UAE accounting or tax professional and, where appropriate, the Federal Tax Authority before making compliance or tax-related decisions.
Environmental, Social, and Governance (ESG) reporting has become a critical part of modern corporate reporting. Investors, regulators, customers, and financial institutions increasingly…
Businesses are under constant pressure to process financial data faster, reduce manual work, and improve accuracy. Traditional accounting methods often rely on…
Businesses are expanding beyond domestic markets more than ever before. Companies buy products from overseas suppliers, sell to international customers, receive payments…
0 Comments