How to Handle Errors in Bookkeeping: Correction Methods
Bookkeeping errors can happen in businesses of every size. Whether you manage your accounts manually or use accounting software, even a small…
Read article
Could your UAE business need to prove its tax residency to a foreign tax authority before receiving cross-border tax benefits?
A UAE Tax Residency Certificate (TRC) is an official certificate issued by the Federal Tax Authority (FTA) to confirm that a person is a tax resident in the UAE. For businesses involved in international transactions, a TRC may be relevant when dealing with foreign tax authorities, withholding taxes, or benefits available under a Double Taxation Agreement (DTA).
However, not every UAE company automatically needs a TRC. The need depends on the company’s circumstances, the country involved, the applicable tax treaty and the purpose for which the certificate is required. If your business has international income, overseas customers, foreign suppliers or investments outside the UAE, understanding when a TRC may be useful can help you prepare the right documentation before a cross-border tax issue arises.
A UAE Tax Residency Certificate is a certificate issued by the FTA to prove that a person is a tax resident in the UAE for the relevant period.
The certificate can be requested for:
A TRC is particularly relevant in international tax matters because a business may have economic activities or income connected with more than one country. Different jurisdictions can apply their own tax rules to cross-border income, which can potentially result in taxation in more than one country.
Where a DTA applies, the treaty may provide mechanisms such as reduced withholding tax rates, exemptions or other relief, subject to the conditions of the relevant agreement.
A TRC can therefore serve as evidence of UAE tax residency when a foreign authority or counterparty requires proof.
A business does not generally obtain a TRC simply because it is incorporated in the UAE. The certificate becomes relevant when there is a practical or tax-related reason to demonstrate UAE tax residency.
A UAE company may provide services to overseas customers, receive foreign-source income, hold investments abroad or conduct other cross-border activities. In such cases, the foreign country may have its own rules for taxing payments made to a UAE business.
For example, an overseas customer may be required under local law to consider withholding tax when making certain payments to a foreign company. If the relevant DTA provides a reduced rate or other relief, the UAE business may be asked to provide evidence of its UAE tax residency.
A TRC may be part of the documentation required to support the relevant treaty position. The exact treatment depends on the nature of the income, the applicable foreign tax rules and the wording of the relevant DTA.
One of the main reasons businesses apply for a TRC is to support a claim under a Double Taxation Agreement. The UAE has an extensive network of DTAs with other jurisdictions. These agreements are designed to allocate taxing rights and reduce the risk of the same income being taxed twice.
However, having a DTA between the UAE and another country does not automatically mean that every UAE business receives treaty benefits. The business must satisfy the relevant conditions under the applicable agreement. The foreign jurisdiction may also request specific documentation before granting a treaty benefit.
The FTA’s process allows applicants to request a TRC for DTA purposes, with the relevant contracting country identified as part of the application.
Sometimes the need for a TRC comes directly from the foreign jurisdiction. A tax authority, bank, customer, withholding agent or other relevant institution may request evidence that the company is a UAE tax resident before accepting a particular tax treatment.
This can happen where a UAE company is receiving income from another country or seeking to establish that the UAE is its residence jurisdiction under an applicable tax treaty.
Businesses should therefore avoid assuming that a trade licence alone will always satisfy a foreign authority’s requirements. The requesting authority may have its own forms, certification or documentation requirements in addition to the UAE TRC.
UAE companies with overseas investments may also encounter situations where proof of tax residency becomes relevant.
For example, a company may hold shares, financial investments or other assets in another jurisdiction and receive income from those investments.
Depending on the local tax rules and applicable DTA, the foreign jurisdiction may impose tax on certain income. A TRC may then be requested when the business seeks treaty-based relief. The company should assess the tax treatment before assuming that a TRC will automatically eliminate or reduce foreign tax.
Companies belonging to international groups may have transactions involving related entities outside the UAE. Examples can include:
The tax treatment of these transactions can depend on the laws of both countries and the applicable DTA.
A TRC may form part of the documentation required to demonstrate the UAE tax residency of the UAE entity. However, it does not replace other transfer pricing, corporate tax or transaction-level compliance requirements.
No.
A UAE business may have a Corporate Tax registration and receive a Corporate Tax TRN, but that does not mean the company has automatically obtained a Tax Residency Certificate.
These serve different purposes.
Corporate Tax registration establishes the company’s registration with the FTA for Corporate Tax purposes and forms part of its UAE tax compliance obligations.
Tax residency concerns whether the company qualifies as a tax resident under the applicable UAE rules and, where relevant, under an applicable DTA.
A Tax Residency Certificate is the formal certificate issued by the FTA as evidence of tax residency for the relevant period.
This distinction is particularly important for businesses dealing with foreign tax authorities. A foreign party may specifically request a TRC rather than simply asking for a Corporate Tax registration certificate.
Not necessarily.
The FTA does not issue a TRC merely because an applicant has a UAE trade licence. It must be satisfied that the applicant meets the applicable tax residency requirements.
For UAE juridical persons, tax residency can involve factors such as incorporation or establishment in the UAE and, in certain circumstances, effective management and control.
The purpose of the certificate also matters. A TRC requested for DTA purposes is assessed with reference to the relevant international agreement.
This is why businesses should consider the specific country, income type, period and purpose before submitting an application.
Businesses should pay particular attention to the period covered by the certificate.
FTA guidance states that a TRC for a current period can generally be considered for a juridical person after three months into the period. It also states that newly incorporated companies that have not yet filed a Corporate Tax Return must generally have been established for 12 months before they are eligible to apply for a TRC.
The applicable position can depend on the circumstances and the type of certificate requested.
For this reason, a newly established UAE company should not assume that it can immediately obtain a TRC simply because it has been incorporated and received its trade licence.
Businesses should check the current FTA requirements before submitting an application, particularly where the certificate is required urgently for an overseas transaction.
The exact documentation can vary depending on the type of application and the applicant’s circumstances.
For a UAE juridical person, FTA guidance identifies documents that may include:
For treaty-purpose applications, additional supporting evidence may be relevant. FTA application guidance also identifies documents such as audited financial statements, office lease documentation and local bank statements in the relevant application process.
The FTA may request additional evidence where necessary to determine whether the applicant satisfies the relevant tax residency criteria.
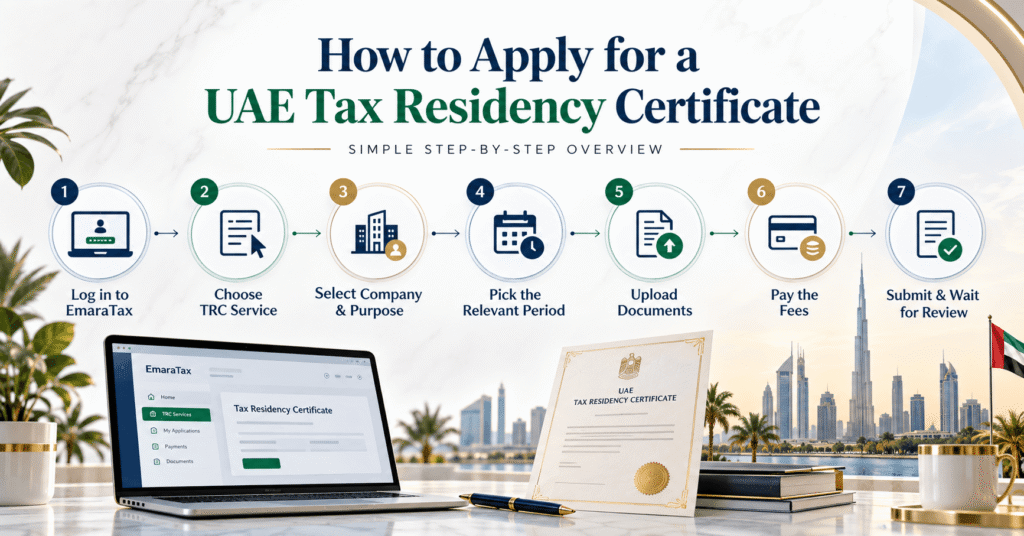
Businesses can apply through the FTA’s online system. The general process involves:
The applicant uses its EmaraTax account to access the relevant tax residency service.
The applicant selects the Tax Residency Certificate service under the available services.
For a company, the applicant will need to provide the relevant information for the juridical person and identify whether the certificate is required for DTA purposes or another purpose. Where a DTA application is being made, the relevant foreign contracting country must be identified.
The company must specify the relevant financial or tax period covered by the certificate. A TRC cannot generally be requested for a future period that has not yet started, because the FTA cannot certify future tax residency.
The company provides the required documentation and any additional evidence requested as part of the application.
The applicant pays the relevant submission and processing fees applicable to its circumstances.
The FTA reviews the application and supporting information. If the FTA is satisfied that the applicant meets the relevant tax residency criteria, the certificate can be issued. The digital certificate can then be downloaded through the relevant platform.
Applying for a TRC should ideally be part of a wider cross-border tax review rather than a last-minute administrative task.
Before submitting an application, businesses can check:
Before applying, a business can use this simple checklist:
Cross-border tax matters often involve more than obtaining a certificate. Businesses may need to determine why the TRC is required, which treaty provisions may apply, what supporting records are available and whether the transaction has other UAE or foreign tax implications.
Ripple Accounting, Tax & Advisory can support UAE businesses with tax advisory and compliance requirements related to cross-border activities. If your business is considering a UAE Tax Residency Certificate, Ripple can help you review the purpose of the certificate, relevant business records and documentation requirements before you proceed with the application.
For businesses with international income or cross-border transactions, contact Ripple Accounting, Tax & Advisory for a tailored tax compliance review and practical guidance based on your business circumstances.
A UAE Tax Residency Certificate is issued by the FTA to confirm that a business is a tax resident in the UAE for the relevant period. It may be required when a company needs to demonstrate UAE tax residency to a foreign tax authority or support a claim under an applicable Double Taxation Agreement.
No. A TRC is not a routine requirement for every UAE company. It is generally relevant when a business needs formal evidence of UAE tax residency, particularly in connection with cross-border transactions, foreign tax requirements or DTA benefits.
Eligibility depends on the company’s circumstances and the period covered. FTA guidance states that newly incorporated companies that have not yet filed a Corporate Tax Return generally need to have been established for 12 months before becoming eligible to apply for a TRC. Businesses should verify the current FTA requirements before applying.
No. A Corporate Tax TRN identifies a business for UAE Corporate Tax registration purposes. A TRC is a separate certificate issued by the FTA to prove tax residency for the relevant period.
No. A TRC does not automatically remove foreign tax. Whether withholding tax can be reduced, eliminated or refunded depends on the laws of the foreign jurisdiction, the applicable DTA and the specific income or transaction involved. The foreign authority may also require additional documentation.
A UAE Tax Residency Certificate can become important when a business has international income or needs to demonstrate its UAE tax residency to a foreign authority. However, the certificate is not automatically required for every UAE company, and eligibility depends on the relevant tax residency rules, certificate period and purpose of the application. Businesses involved in cross-border transactions should identify their documentation requirements early and review the applicable DTA where treaty benefits are being considered. Keeping corporate, financial and operational records organised can also make the application process more straightforward.
Disclaimer: This article is provided for general informational purposes only and does not constitute legal, tax or financial advice. Tax residency and treaty treatment depend on the specific facts of each business, the relevant UAE legislation, the applicable Double Taxation Agreement and the requirements of the foreign jurisdiction. FTA guidance and service requirements may change. Businesses should verify the current requirements with the Federal Tax Authority and obtain professional advice where appropriate.
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
 Bookkeeping
 errors can happen in businesses of every size. Whether you manage your accounts manually or use accounting software, even a small…
Read article Bookkeeping
Managing payroll is one of the most important responsibilities for any business. Employees expect to receive accurate salaries on time, while businesses…
Read article Audit
Investing in a company involves more than reviewing its profits or growth projections. Investors need reliable financial information to understand whether a…
Read articlePage 42 of 45
Book a free consultation and get clear answers for your business.
0 Comments