How to Handle Errors in Bookkeeping: Correction Methods
Bookkeeping errors can happen in businesses of every size. Whether you manage your accounts manually or use accounting software, even a small…
Read article
Could your tobacco or e-smoking products be affected by the UAE’s latest excise tax update?
UAE excise tax update 2026, under Cabinet Decision No. 137 of 2026 introduces minimum Excise Prices for cigarettes, water pipe tobacco, electrically heated cigarettes, and liquids used in electronic smoking devices. Issued on 24 July 2026, the Decision took effect on 1 September 2026. It also clarifies that e-smoking liquids may be covered whether or not they contain nicotine. Affected businesses should review the applicable minimum prices and ensure compliance with the wider UAE excise tax framework.
Cabinet Decision No. 137 of 2026 concerns the Excise Price for Tobacco Products and Liquids used in Electronic Smoking Devices and Tools. The Decision forms part of the UAE’s wider excise tax framework and refers to several existing pieces of legislation, including Federal Decree-Law No. 7 of 2017 on Excise Tax, Federal Decree-Law No. 28 of 2022 on Tax Procedures and Cabinet Decision No. 197 of 2025.
An important point for businesses is the distinction between an Excise Price and an excise tax rate.
Under Article 1 of Cabinet Decision No. 137 of 2026, the term Excise Price means the price calculated in accordance with Article 11 of Cabinet Decision No. 197 of 2025.
Cabinet Decision No. 137 then establishes minimum amounts below which the Excise Price for the specified products cannot fall.
Therefore, the figures contained in the new Decision should be understood as minimum Excise Prices, rather than being described simply as new excise tax rates.
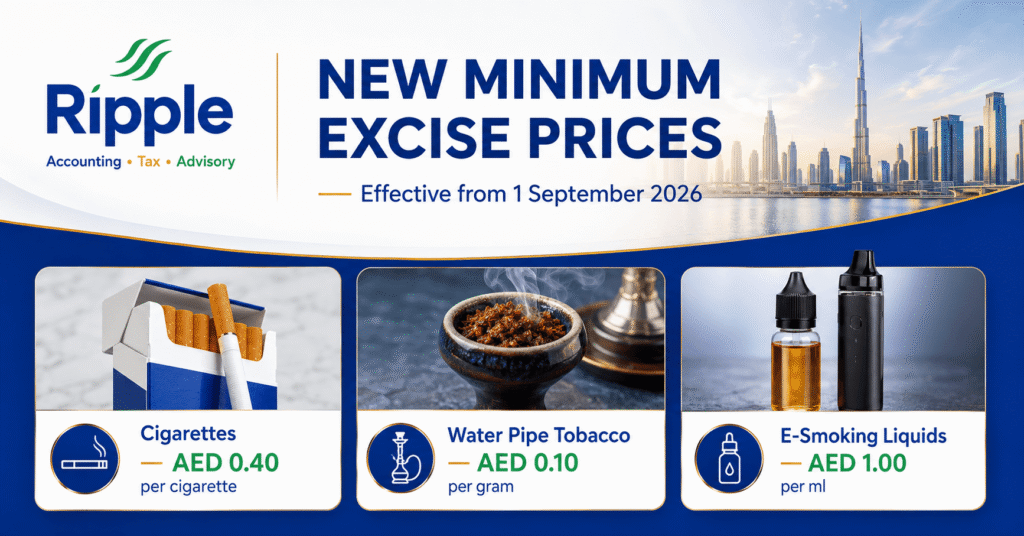
Article 2 of Cabinet Decision No. 137 of 2026 establishes minimum Excise Prices for three main categories of products.
| Product Category | Minimum Excise Price |
| Cigarettes | AED 0.40 per cigarette |
| Water pipe tobacco, ready-to-use tobacco and similar products | AED 0.10 per gram |
| Liquids used in electronic smoking devices and tools | AED 1 per ml |
The Decision states that the Excise Price for these goods is to be determined pursuant to Article 11 of Cabinet Decision No. 197 of 2025, provided that it is not lower than these prescribed amounts.
This means businesses should not look at the minimum amounts in isolation. The applicable Excise Price must still be determined in accordance with the relevant pricing rules, while respecting the minimum thresholds introduced by Cabinet Decision No. 137 of 2026.
Understanding product definitions is essential because the minimum pricing rules differ depending on the type of excise good.
The Decision defines Cigarettes broadly as:
All cigarettes, whether normal or electrically heated. This means the definition is not limited to conventional combustible cigarettes. Electrically heated cigarettes are expressly included.
Businesses dealing with heated tobacco products should therefore pay particular attention to how their products are classified and whether the minimum Excise Price for cigarettes applies.
The Decision also defines Water Pipe Tobacco. It covers tobacco intended for smoking in a water pipe and consisting of a mixture of tobacco and glycerol. The definition applies whether or not the product also contains aromatic oils or extracts, molasses, sugar or fruit flavouring.
For the products covered by Article 2, the minimum Excise Price is:
AED 0.10 per gram.
This minimum is stated for water pipe tobacco, ready-to-use tobacco and other similar products.
Businesses dealing with shisha or water pipe tobacco should therefore ensure that quantities and product classifications used in excise calculations are accurately recorded.
The third major category covers liquids used in electronic smoking devices and tools. The Decision defines this category as including all liquids used in such devices and similar tools whether or not they contain nicotine. This is a particularly important point for businesses dealing with e-liquids.
A product should not automatically be assumed to fall outside the definition merely because it does not contain nicotine.
For liquids within the scope of the Decision, the minimum Excise Price is:
AED 1 per 1 ml of liquid.
Cabinet Decision No. 137 of 2026 became effective from 1 September 2026. Article 4 provides that the Decision is to be published in the Official Gazette and is effective from 1 September 2026. Because the effective date has now passed, affected businesses should consider whether their current product data, Excise Price calculations, and related compliance processes reflect the new requirements.
Businesses that continued to rely on older minimum pricing rules after the effective date may need to review their treatment against the new Decision.
Another important part of the update is the repeal of the previous Cabinet Decision dealing with the Excise Price for tobacco products. Article 3 of Cabinet Decision No. 137 of 2026 states that Cabinet Decision No. 55 of 2019 on Excise Price for Tobacco Products is repealed, together with provisions that violate or conflict with the new Decision.
This is particularly relevant for businesses, finance teams, and advisers that may still have internal policies, tax manuals, calculation templates, or system configurations referring to the 2019 Decision.
Those references should be reviewed against the rules now in effect.
The minimum Excise Price can be easier to understand through simple quantity-based illustrations. These examples demonstrate only the minimum amounts specified in Cabinet Decision No. 137 of 2026. They should not be treated as a complete calculation of the final tax liability, which depends on the applicable UAE excise tax rules.
Suppose a pack contains 20 cigarettes. The minimum Excise Price under the new Decision would be:
20 cigarettes × AED 0.40 = AED 8
Therefore, AED 8 represents the minimum Excise Price derived from the per-cigarette threshold for that quantity.
Suppose a package contains 250 grams of qualifying water pipe tobacco. The minimum amount would be:
250 grams × AED 0.10 = AED 25
Again, this illustrates the minimum prescribed amount rather than a standalone calculation of the business’s complete excise tax obligation.
Suppose an e-smoking product contains 30 ml of liquid. The minimum Excise Price based on the Decision would be:
30 ml × AED 1 = AED 30
Businesses must still determine the Excise Price in accordance with the applicable rules referred to in Article 11 of Cabinet Decision No. 197 of 2025, subject to the minimum thresholds.
The practical impact will depend on the products a business manufactures, imports, stores, distributes or otherwise deals with and the business’s obligations under the UAE excise tax framework.
However, affected businesses may need to review several areas.
Businesses should verify that relevant goods are correctly classified. This is particularly important where products may include:
Incorrect classification could affect how the applicable rules are applied.
The Decision uses three different measurement bases:
Businesses should therefore ensure that reliable quantity information is available within their product, inventory and tax records.
Where excise calculations are supported by ERP, accounting, inventory or tax systems, businesses may wish to review whether the relevant product information and pricing parameters remain aligned with the rules effective from 1 September 2026.
Internal tax manuals, compliance procedures and calculation templates that still refer to Cabinet Decision No. 55 of 2019 should also be reviewed because that Decision has been repealed.
Several points in Cabinet Decision No. 137 of 2026 deserve particular attention.
The AED 0.40, AED 0.10 and AED 1 amounts are presented by the Decision as minimum Excise Prices for the respective product categories. Businesses should therefore avoid treating these amounts as though they are themselves the applicable excise tax rates.
The definition of cigarettes expressly includes both normal and electrically heated cigarettes. Businesses dealing with heated products should not assume that the provision is limited to conventional cigarettes.
The Decision expressly states that the liquids covered may contain nicotine or may not contain nicotine. Product composition should therefore not be assessed solely on the presence or absence of nicotine when considering this definition.
Cabinet Decision No. 55 of 2019 has been repealed. Businesses relying on historical references should update their compliance documentation accordingly.
Businesses dealing with products potentially affected by Cabinet Decision No. 137 of 2026 may consider taking the following practical steps:
The appropriate compliance action will depend on the specific facts and tax position of each business.
Changes to UAE tax legislation can require more than simply updating a number in a calculation sheet. Businesses may need to assess product classification, tax treatment, underlying data and the systems used to support their excise tax compliance.
Ripple Accountants can assist UAE businesses with reviewing excise tax treatment, relevant product data, Excise Price calculations, supporting records, and broader excise tax compliance requirements.
Contact Ripple Accountants to discuss your excise tax position and the impact of the latest UAE regulatory changes on your business!
Cabinet Decision No. 137 of 2026 deals with the Excise Price for tobacco products and liquids used in electronic smoking devices and tools. It establishes minimum Excise Prices for specified products.
The Decision became effective from 1 September 2026.
The minimum Excise Price is AED 0.40 per cigarette.
The Decision specifies a minimum of AED 0.10 per gram for water pipe tobacco, ready-to-use tobacco and other similar products.
The minimum Excise Price is AED 1 per 1 ml of liquid used in electronic smoking devices and tools.
The definition in the Decision includes liquids used in electronic smoking devices and similar tools whether or not containing nicotine.
Yes. The Decision defines cigarettes as including normal and electrically heated cigarettes.
Yes. Cabinet Decision No. 137 of 2026 repeals Cabinet Decision No. 55 of 2019 on Excise Price for Tobacco Products and provisions that conflict with the new Decision.
Cabinet Decision No. 137 of 2026 represents an important update for businesses dealing with tobacco products and liquids used in electronic smoking devices in the UAE. Effective from 1 September 2026, the Decision establishes minimum Excise Prices of AED 0.40 per cigarette, AED 0.10 per gram for specified water pipe and similar tobacco products, and AED 1 per ml for liquids used in electronic smoking devices and tools. It also makes clear that electrically heated cigarettes are included within the definition of cigarettes and that electronic-smoking liquids may be covered whether or not they contain nicotine.
Disclaimer: This article is provided for general informational and educational purposes only and does not constitute accounting, audit, tax, financial or legal advice. UAE Corporate Tax rules and official guidance may also be updated. Businesses should review the applicable IFRS requirements and UAE legislation and consult a qualified accountant, auditor, or tax professional before making accounting or tax decisions.
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
 Bookkeeping
 errors can happen in businesses of every size. Whether you manage your accounts manually or use accounting software, even a small…
Read article Bookkeeping
Managing payroll is one of the most important responsibilities for any business. Employees expect to receive accurate salaries on time, while businesses…
Read article Audit
Investing in a company involves more than reviewing its profits or growth projections. Investors need reliable financial information to understand whether a…
Read articlePage 42 of 45
Book a free consultation and get clear answers for your business.
0 Comments