UAE VAT Executive Regulation 2026: Key Changes Under Cabinet Decision No. 149
The UAE has introduced important amendments to its VAT framework through Cabinet Decision No. 149 of 2026, changing several provisions of the…
Read article
Have you missed a UAE Corporate Tax deadline and are unsure which penalty may apply to your business?
UAE Corporate Tax compliance involves several deadlines, including registration, Tax Return filing and payment of Corporate Tax due. Missing these requirements can result in administrative penalties, although specific relief may be available in certain circumstances.
For businesses that are late or uncertain about their Corporate Tax obligations, understanding the applicable penalties and available waiver mechanisms can help them take corrective action. Before assuming a penalty is unavoidable, businesses should identify which obligation was missed, when it became due and whether any current relief or waiver conditions apply.
UAE Corporate Tax penalties are administrative penalties that may apply when a person fails to comply with obligations under the Corporate Tax legislation and related decisions.
The penalties can relate to different compliance failures, including:
The amount and calculation of a penalty depend on the specific violation.
The Federal Tax Authority (FTA) publishes the applicable Corporate Tax legislation and administrative penalty provisions. Businesses should therefore distinguish between the penalty for late registration, penalties connected with late filing and penalties relating to unpaid Corporate Tax.
One of the most important penalties for businesses that have not completed Corporate Tax registration is the late registration penalty. The FTA currently states that an administrative penalty of AED 10,000 applies when a person fails to submit a Corporate Tax registration application within the prescribed timeframe. The registration deadline depends on the type of taxable person and the applicable FTA requirements.
Therefore, a business should not assume that incorporation or obtaining a trade license automatically gives it unlimited time to register for Corporate Tax.
Taxable persons subject to UAE Corporate Tax are generally required to register with the FTA and obtain a Corporate Tax Registration Number, subject to the applicable rules and exemptions.
For example, the FTA states that a natural person carrying on a business or business activity is required to register when the relevant revenue threshold is exceeded.
Different registration timelines can apply to resident juridical persons, non-resident persons and natural persons. Businesses should therefore determine their taxpayer category before assessing whether their registration was late.
The current administrative penalty for failure to submit the Corporate Tax registration application within the prescribed timeframe is: AED 10,000 This penalty applies to the specified registration violation under the Corporate Tax administrative penalty framework.
However, businesses that have incurred this penalty should also check whether they qualify for the FTA’s late-registration penalty waiver initiative.
This is the official FTA page explaining the late Corporate Tax registration penalty waiver, including the seven-month condition and eligible scenarios: FTA Corporate Tax Penalty Waiver
Yes, an FTA waiver initiative is currently available for eligible taxpayers. Under the initiative, the AED 10,000 late-registration penalty can be waived where the taxpayer meets the applicable conditions, including submitting the first Tax Return within 7 months from the end of the first Tax Period.
For an exempt person required to register, the relevant requirement concerns submission of the Annual Declaration within seven months from the end of the first financial year.
The FTA explains that the initiative can apply in several situations, including where:
Where a penalty has already been paid and the taxpayer subsequently meets the waiver conditions, the FTA states that the amount can be credited back to the taxpayer’s account.
The critical condition is the timing of the first Tax Return. The taxpayer must submit the first Tax Return within 7 months from the end of the first Tax Period to benefit from the late-registration penalty exemption.
This is different from the general Corporate Tax filing deadline of up to nine months from the end of the Tax Period. The seven-month period is specifically relevant to the late-registration penalty waiver initiative. Businesses should therefore avoid confusing the normal filing deadline with the special waiver condition.
Taxable persons generally need to submit their Corporate Tax Return within 9 months from the end of the relevant Tax Period. The FTA reiterated this requirement in September 2026, noting that taxable persons must file their Tax Returns and pay Corporate Tax due within a period not exceeding nine months from the end of each Tax Period.
For example, if a company’s Tax Period ends on 31 December 2025, its Tax Return and Corporate Tax payment are generally due by 30 September 2026.
The exact deadline should always be checked against the taxpayer’s own Tax Period and applicable requirements.
Failure to submit a Corporate Tax Return within the prescribed timeframe can result in a monthly administrative penalty.
Under the Corporate Tax administrative penalty framework, the penalty for failure to submit a Tax Return is:
This means that even a short delay can trigger a penalty because the rule applies to each month or part of a month.
Businesses should therefore avoid assuming that a filing that is only a few days late will necessarily avoid the monthly penalty.
If a business misses its Corporate Tax filing deadline, it should act promptly rather than waiting for the penalty to increase.
The business should:
The FTA continues to remind taxpayers to submit returns and settle Corporate Tax within the statutory timeframe to avoid late-payment penalties.
Late payment is separate from late filing. A business may submit its Tax Return but still face a penalty if the Corporate Tax payable is not settled by the required payment deadline.
Under the Corporate Tax administrative penalty framework, failure to settle payable tax attracts a monthly penalty calculated at 14% per annum for each month or part thereof on the unsettled amount, starting from the day following the payment due date and continuing monthly.
This distinction is important.
A business can therefore have:
Each should be reviewed separately.
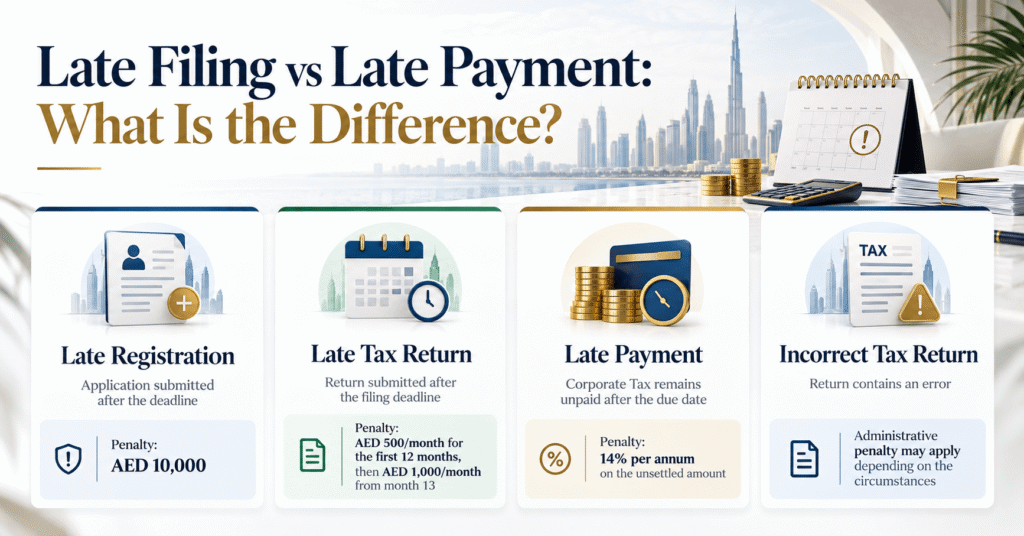
| Compliance issue | What happened? | Potential consequence |
| Late registration | Registration application submitted after the prescribed deadline | AED 10,000 administrative penalty |
| Late Tax Return | Return submitted after the filing deadline | AED 500/month or part thereof for first 12 months; AED 1,000/month or part thereof from month 13 |
| Late payment | Corporate Tax due remains unpaid after the payment deadline | Monthly penalty based on 14% per annum on the unsettled amount |
| Incorrect Tax Return | Return contains an error | Applicable administrative penalty may arise depending on the circumstances |
The applicable rules should be reviewed based on the date of the violation and the taxpayer’s circumstances.
No. The FTA’s current waiver initiative specifically concerns the administrative penalty for late Corporate Tax registration.
The taxpayer must meet the seven-month first-return condition to benefit from that exemption. The waiver should not be treated as a general cancellation of all Corporate Tax penalties.
Businesses should therefore distinguish between:
Each has its own rules and consequences.
Receiving a penalty does not mean the business should stop reviewing its compliance position.
The first step is to identify exactly what the penalty relates to.
Review the business’s EmaraTax account and identify the relevant penalty, Tax Return or registration obligation.
Determine when the relevant registration, filing or payment was due.
Review the taxpayer’s status, Tax Period, registration date, filing history and payment records.
If the penalty relates to late registration, check whether the business meets the conditions of the current FTA waiver initiative.
If a registration application or Tax Return is still outstanding, complete the relevant filing as soon as possible.
Where Corporate Tax or penalties remain payable, review the amount shown in the FTA account and take the appropriate payment or procedural action.
The term “penalty waiver” can create confusion because not every Corporate Tax penalty is automatically waived. The current FTA initiative is specifically designed to exempt eligible taxpayers from the administrative penalty for late Corporate Tax registration.
The FTA explains that the initiative can cover taxpayers who have already been charged the AED 10,000 penalty and those who have not yet submitted their registration application, provided the relevant conditions are satisfied.
If a taxpayer has already paid the late-registration penalty, the FTA states that the amount may be credited back to the taxpayer’s account after the waiver conditions are met. Businesses should therefore assess eligibility rather than assuming that a penalty is either permanently payable or automatically cancelled.
A practical compliance process can reduce the risk of missed deadlines.
Record:
The Tax Period determines when the Corporate Tax Return and payment become due.
The Tax Return should be supported by reliable financial records.
Businesses should review the trial balance, income statement, balance sheet, adjustments and relevant tax calculations before submitting the return.
Businesses should regularly review their EmaraTax account and official FTA communications.
The FTA states that relevant records must generally be retained for at least seven years following the end of the relevant Tax Period.
Maintaining organised records can make it easier to identify compliance issues and respond to FTA requests.
Businesses can use this checklist when reviewing their Corporate Tax position:
Corporate Tax penalties can become more complicated when a business has missed more than one deadline or is unsure whether a waiver applies.
Ripple Accounting, Tax & Advisory can support businesses with Corporate Tax compliance, registration, return preparation and related tax advisory requirements. If your business has a late Corporate Tax registration, overdue Tax Return or outstanding Corporate Tax payment, Ripple can help review the relevant deadlines, records and FTA account information and identify the compliance steps that need attention.
Contact Ripple Accounting, Tax & Advisory for a tailored Corporate Tax compliance review and practical support in addressing outstanding obligations.
The FTA currently states that the administrative penalty for failing to submit a Corporate Tax registration application within the prescribed timeframe is AED 10,000. Eligible taxpayers may qualify for the current late-registration penalty waiver if they meet the applicable conditions.
Late filing can result in an administrative penalty of AED 500 for each month or part thereof for the first 12 months and AED 1,000 for each month or part thereof from the 13th month onwards. The business should submit the outstanding return and address any resulting liabilities promptly.
Certain relief is available for eligible late Corporate Tax registration cases. Under the FTA’s current initiative, the first Tax Return must generally be submitted within seven months from the end of the first Tax Period to qualify for the late-registration penalty exemption. This does not represent a general waiver of all Corporate Tax penalties.
Failure to settle Corporate Tax payable on time can result in a monthly penalty calculated at 14% per annum for each month or part thereof on the unsettled tax amount, beginning after the payment due date.
A Corporate Tax Return and Corporate Tax payment are generally due within nine months from the end of the relevant Tax Period. The exact deadline depends on the taxpayer’s Tax Period.
UAE Corporate Tax penalties can arise from different compliance failures, so businesses should first identify whether the issue concerns registration, filing or payment. The current late-registration penalty is AED 10,000, while late filing and late payment have separate penalty mechanisms. Eligible taxpayers may also be able to benefit from the FTA’s late-registration penalty waiver initiative if they satisfy the specified conditions. Businesses that have missed a deadline should review their EmaraTax account, complete outstanding requirements and check whether any applicable relief is available rather than allowing the issue to remain unresolved.
Disclaimer: This article is provided for general informational purposes only and does not constitute tax, legal or financial advice. Corporate Tax penalties, deadlines, waiver conditions and administrative procedures depend on the applicable UAE legislation and the taxpayer’s individual circumstances. FTA rules and guidance may be amended. Businesses should verify the latest requirements with the Federal Tax Authority or obtain professional tax advice before taking action.
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
 VAT
The UAE has introduced important amendments to its VAT framework through Cabinet Decision No. 149 of 2026, changing several provisions of the…
Read article Audit
Are your business controls strong enough to prevent errors, fraud and compliance problems before they reach your financial statements? For UAE SMEs,…
Read article Audit
Would your business be ready if the Federal Tax Authority asked for your tax records tomorrow? UAE FTA audit readiness is not…
Read articlePage 7 of 45
Book a free consultation and get clear answers for your business.
0 Comments