UAE Corporate Tax Filing Calendar: How to Track Every Entity Deadline
M Maria September 1, 2026 11 min read
When is your UAE Corporate Tax return due?
The deadline is not the same for every business. It generally depends on the end of the relevant Tax Period, making a reliable UAE corporate tax filing calendar essential for companies, Free Zone businesses and other taxable persons.
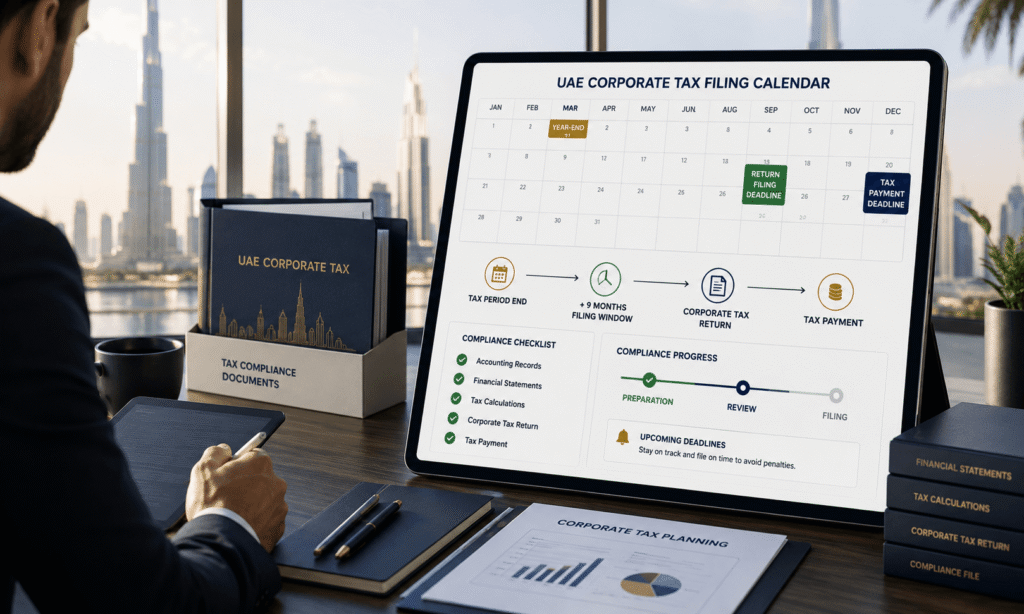
Under the UAE Corporate Tax Law, a Taxable Person generally must file its Corporate Tax Return and pay the tax due within nine months from the end of the relevant Tax Period, unless the FTA specifies otherwise.
Therefore, businesses should identify their Tax Period, registration requirements and applicable filing and payment deadlines rather than relying on one fixed annual date.
Let us break down how to build and maintain a Corporate Tax calendar that works for your UAE business.
What Is a UAE Corporate Tax Filing Calendar?
A UAE Corporate Tax filing calendar is a structured schedule used to track the important Corporate Tax obligations of a business throughout its Tax Period.
It can include:
Corporate Tax registration deadlines
Tax Period start and end dates
Corporate Tax Return filing deadlines
Corporate Tax payment deadlines
Tax group-related obligations
Record-keeping requirements
Supporting document preparation
Other elections, applications or disclosures relevant to the taxpayer
The Ministry of Finance recommends that businesses understand their Tax Period, registration requirements, filing deadline and record-keeping obligations as part of preparing for Corporate Tax.
A good calendar therefore does more than show one final filing date. It creates a compliance timeline from registration through return preparation, submission and payment.
How Is the UAE Corporate Tax Filing Deadline Calculated?
The most important rule to remember is the nine-month rule.
Article 53 of Federal Decree-Law No. 47 of 2022 provides that a Taxable Person must file its Tax Return no later than nine months from the end of the relevant Tax Period, unless another date is directed by the FTA. Article 48 similarly provides that Corporate Tax payable must generally be settled within nine months from the end of the relevant Tax Period.
Example: 31 December year-end
Suppose a company has a Tax Period ending on 31 December. Its general filing and payment deadline would be:
31 December → nine months → 30 September
Therefore, a company whose relevant Tax Period ends on 31 December would generally need to submit its Corporate Tax Return and settle the Corporate Tax payable by 30 September of the following year.
The FTA has specifically reminded taxpayers that Corporate Tax Returns and Corporate Tax payable must generally be submitted and settled within nine months from the end of each Tax Period.
Example: 31 March year-end
If the Tax Period ends on 31 March, the nine-month deadline would generally fall on 31 December.
This illustrates why there is no single Corporate Tax filing date applicable to every UAE business.
Corporate Tax Deadlines Depend on the Entity’s Tax Period
The first step in preparing a UAE corporate tax filing calendar is therefore to identify the entity’s Tax Period.
Tax Period end
General return and payment deadline
31 January
31 October
28/29 February
30 November
31 March
31 December
30 April
31 January
31 May
28/29 February
30 June
31 March
31 July
30 April
31 August
31 May
30 September
30 June
31 October
31 July
30 November
31 August
31 December
30 September
These examples illustrate the general nine-month rule. Businesses should confirm the applicable Tax Period and deadline for their own circumstances rather than relying solely on a generic calendar. The Ministry of Finance also provides examples of registration, filing and payment deadlines based on different financial year-ends.
Corporate Tax Registration Is a Separate Deadline
One of the biggest mistakes businesses make is treating Corporate Tax registration and Corporate Tax Return filing as the same obligation. They are not.
A business may have a Corporate Tax registration deadline that occurs before its first Corporate Tax Return deadline.
The FTA has issued specific registration timelines for different categories of Taxable Persons. For example, resident juridical persons incorporated or established in the UAE on or after 1 March 2024 generally have a registration application deadline of three months from incorporation, establishment or recognition. Different rules apply to certain non-resident persons, natural persons and other categories.
The FTA’s official registration service also explains the Corporate Tax registration process through EmaraTax.
Why registration should appear in your calendar
Your compliance calendar should therefore contain at least two separate entries:
1. Corporate Tax registration deadline
and
2. Corporate Tax Return filing/payment deadline
This distinction is particularly important for newly established UAE businesses.
What Should Businesses Prepare Before the Filing Deadline?
Waiting until the final month to prepare the Corporate Tax Return can create unnecessary pressure. A better approach is to work backwards from the filing deadline.
1. Confirm the Tax Period
Start by confirming the company’s financial year and the corresponding Tax Period. Do not assume that every UAE company uses a calendar-year Tax Period.
2. Close the accounting records
Before preparing the Corporate Tax Return, the accounting records should be brought up to date. This includes:
Bank reconciliations
Accounts receivable
Accounts payable
Fixed assets
Accruals and provisions
Revenue records
Expense records
Related-party balances
Inventory records, where applicable
Reliable accounting records make the tax calculation significantly easier to review.
3. Prepare the financial statements
The Corporate Tax calculation starts with reliable financial information. Businesses should therefore ensure that their financial statements and underlying accounting records are complete and properly supported.
4. Review tax adjustments
Accounting profit is not automatically the same as taxable income. The Corporate Tax Return may require adjustments based on the UAE Corporate Tax rules.
The FTA’s Corporate Tax – Tax Returns Guide provides detailed guidance on completing the Corporate Tax Return and explains the information that may need to be provided in the return.
5. Review supporting documents
Businesses should organize the documents supporting their calculations before submission. Depending on the business, these may include:
Financial statements
General ledger
Trial balance
Invoices
Bank statements
Fixed-asset schedules
Related-party information
Tax calculations
Supporting agreements
Other records relevant to the Corporate Tax position
Free Zone Businesses Should Not Ignore the Filing Calendar
A common misconception is that a Free Zone business can ignore Corporate Tax compliance because it may qualify for the Qualifying Free Zone Person regime.
That is not a safe assumption. Eligibility for a particular Corporate Tax treatment does not mean the business can simply ignore its Corporate Tax obligations.
Free Zone businesses should determine their status under the applicable Corporate Tax rules and maintain appropriate records to support their position.
The FTA’s Corporate Tax Return User Manual specifically includes a Free Zone Details section within the Corporate Tax Return process, demonstrating that Free Zone-related information can form part of the filing process.
Therefore, Free Zone companies should have their own Corporate Tax compliance calendar rather than assuming that normal filing obligations do not apply.
How to Build a Corporate Tax Deadline Tracker
A practical Corporate Tax tracker can be maintained in Excel, accounting software or a compliance management system. A simple tracker could contain these columns:
Item
Information to Track
Entity name
Legal entity
TRN
Corporate Tax Registration Number
Tax Period
Start and end date
Registration deadline
Applicable registration date
Return deadline
Nine-month deadline, where applicable
Payment deadline
Corporate Tax payment date
Accounting close
Internal deadline
Tax computation
Preparation status
Return review
Reviewer/sign-off
EmaraTax submission
Submitted/not submitted
Payment
Paid/not paid
Evidence
Acknowledgement/payment record
For businesses managing multiple companies, this becomes particularly useful.
Instead of maintaining one reminder such as “Corporate Tax due”, finance teams can create a separate compliance record for every taxable entity.
Use Internal Deadlines Before the FTA Deadline
The legal deadline should not be your internal deadline.
For example, if your Corporate Tax Return is due on 30 September, your internal calendar could look like this:
This gives the business a buffer for unexpected issues such as missing invoices, accounting errors, related-party information or questions arising during the tax review.
How to File a Corporate Tax Return Through EmaraTax
Corporate Tax Returns are filed electronically through the FTA’s systems. The FTA has published a dedicated Corporate Tax Return Taxpayer User Manual covering the filing process in EmaraTax. The manual walks taxpayers through areas including taxpayer details, Free Zone details, accounting schedules, adjustments, reliefs, tax liability, review and declaration, submission and payment.
For businesses preparing their first return, this is one of the most useful government documents to keep alongside the compliance calendar. The FTA also provides an official Corporate Tax Returns Guide, which explains the information and fields involved in completing a Corporate Tax Return.
What Happens If a Business Misses a Deadline?
Missing a Corporate Tax deadline can create financial and compliance consequences. The FTA has emphasized the importance of submitting Tax Returns and settling Corporate Tax payable within the prescribed deadlines to avoid late-payment penalties and other non-compliance consequences. This is why businesses should treat the filing date as the final legal deadline, not the date when preparation begins.
A strong process includes:
Identify the deadline.
Set an internal deadline earlier.
Assign responsibility to a specific person.
Prepare the accounting records.
Complete the tax computation.
Review the return.
Submit through EmaraTax.
Complete the required payment.
Save the submission acknowledgement and payment evidence.
Where to Find the Official UAE Corporate Tax Information
Businesses should rely primarily on the UAE Ministry of Finance and Federal Tax Authority for statutory information rather than generic online deadline lists.
UAE Ministry of Finance – Corporate Tax
The Ministry of Finance Corporate Tax page provides information about the UAE Corporate Tax regime, including the general nine-month filing and payment rule and guidance on determining a business’s Tax Period and obligations.
Federal Tax Authority – Corporate Tax Guides and References
The FTA maintains an official library of Corporate Tax guides, references and public clarifications. This is particularly useful when a business needs guidance on a specific Corporate Tax issue rather than a general deadline.
These official resources give businesses a direct route to the exact government information relevant to their obligation.
How Ripple Accountant Helps UAE Businesses Manage Corporate Tax Deadlines
Keeping track of Corporate Tax deadlines becomes more complicated when a business has multiple entities, different financial year-ends, Free Zone considerations, or incomplete accounting records.
Ripple Accountantcan support UAE businesses with Corporate Tax compliance by helping maintain accurate accounting records, preparing financial information, reviewing tax-related calculations, organizing supporting documentation, and assisting with Corporate Tax filing readiness.
Instead of waiting until the statutory deadline approaches, businesses can establish an ongoing process that connects bookkeeping, financial reporting, and Corporate Tax compliance.
Need help managing your UAE Corporate Tax compliance calendar? Contact Ripple Accountant to discuss your accounting and Corporate Tax support requirements!
Email: info@uaetaxcompliance.ae
Phone: +971 52 356 5409
WhatsApp: +971 4 250 0833
Frequently Asked Questions
1. Is the UAE Corporate Tax filing deadline the same for every company?
No. The general deadline is linked to the end of the relevant Tax Period. A Taxable Person generally has nine months from the end of its Tax Period to file its Corporate Tax Return and settle Corporate Tax payable.
2. Is Corporate Tax registration deadline the same as the filing deadline?
No. Registration deadlines are governed by specific rules for different categories of Taxable Persons. They should be tracked separately from the Corporate Tax Return deadline.
3. Does a Free Zone company need to consider Corporate Tax filing deadlines?
Free Zone businesses should determine their Corporate Tax status and applicable obligations rather than assuming that Free Zone status removes filing requirements. The FTA’s Corporate Tax Return process includes specific Free Zone information.
4. Where can I find the official Corporate Tax Return instructions?
The FTA publishes both a Corporate Tax Returns Guide and a Corporate Tax Return Taxpayer User Manual. These are the most useful official documents for understanding the return and its EmaraTax submission process.
5. Should businesses wait until the statutory deadline to prepare their return?
No. It is better to set internal deadlines several weeks or months before the statutory due date. This gives the finance team time to close the accounts, resolve errors, complete the tax computation, and review the return.
Conclusion
A reliable UAE corporate tax filing calendar should do more than record one annual deadline. It should track the complete compliance process from Corporate Tax registration and Tax Period identification to accounting close, tax computation, return submission, and payment. The key rule is that a Taxable Person generally has nine months from the end of its relevant Tax Period to file its Corporate Tax Return and settle the Corporate Tax payable.
Disclaimer: This article is provided for general informational purposes only and does not constitute tax, accounting or legal advice. UAE Corporate Tax rules, implementing decisions, FTA guidance and administrative requirements may change. The applicable treatment and deadline can also depend on the taxpayer’s specific circumstances, Tax Period, entity type, and other factors. Businesses should verify their obligations against the latest information published by the UAE Ministry of Finance and Federal Tax Authority and obtain professional advice where appropriate.
Environmental, Social, and Governance (ESG) reporting has become a critical part of modern corporate reporting. Investors, regulators, customers, and financial institutions increasingly…
Businesses are under constant pressure to process financial data faster, reduce manual work, and improve accuracy. Traditional accounting methods often rely on…
Businesses are expanding beyond domestic markets more than ever before. Companies buy products from overseas suppliers, sell to international customers, receive payments…
0 Comments