UAE VAT Registration Threshold: Mandatory or Voluntary?
When does VAT registration become mandatory for a UAE business, and when is it simply an option? For UAE businesses, the answer…
Read article
Have you recently added a new activity to your UAE trade licence?
Before you start generating revenue from it, it is worth checking whether the change affects your tax treatment, accounting records, invoicing or regulatory requirements. A licence update may look like a simple administrative step, but the way the new activity is operated and recorded can create additional compliance considerations. A UAE business activity compliance review helps businesses assess these changes early, identify potential gaps and update their accounting and compliance processes before problems arise.
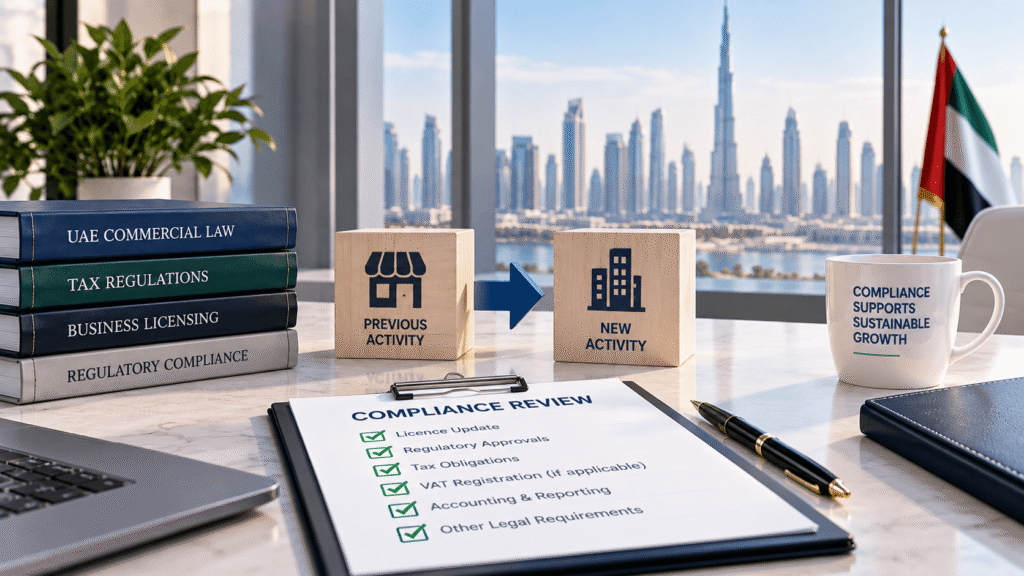
A UAE business activity compliance review is a structured assessment performed after a company adds, removes or changes a business activity. The purpose is to determine whether the company’s:
The review is not simply a check of whether the activity appears on the licence. It considers how the change affects the business operationally, financially and from a compliance perspective.
For UAE Corporate Tax purposes, the Federal Tax Authority defines a business activity broadly and notes that, for juridical persons, activities conducted and assets used or held will generally be considered for the purposes of a business.
A compliance review is particularly useful when a company makes a significant change to what it does or how it earns revenue.
A company may add consulting, e-commerce, trading, marketing, technology, or another activity to its license. Before generating substantial transactions from that activity, the business should review its accounting, tax, and regulatory implications.
The UAE Government explains that identifying the business activity is a key step in determining the appropriate licence and that businesses may conduct more than one business activity.
Removing an activity can also require a review. Existing contracts, recurring invoices, accounting codes and customer arrangements may still refer to the discontinued activity.
The commercial activity on the licence may remain unchanged while the actual products or services offered by the company change. This can create new VAT, accounting or regulatory considerations.
Moving from traditional trading to e-commerce, adding subscription services or introducing consultancy revenue can change how transactions should be recorded and reported.
Some sectors require additional approvals or specific regulatory requirements. A licence amendment alone should not be assumed to satisfy every applicable requirement.
Businesses changing their operating structure should review the interaction between their licence, activities, accounting records and applicable tax requirements.
Changing an activity does not automatically mean that every part of the company’s compliance position must change. Instead, the business should assess the areas affected by the actual activity and transactions.
First, confirm that the amended trade licensed accurately reflects the activity being conducted.
Check:
The relevant licensing authority should be consulted where activity-specific requirements apply.
A new activity should trigger a review of the VAT treatment of the goods or services being supplied. Businesses may need to check:
Adding an activity does not automatically create a new VAT registration requirement. The business should assess its actual taxable supplies and the VAT rules applicable to its transactions.
Corporate Tax should also be considered when a business expands into a different activity.
The review may include:
A change in activity does not automatically mean that an existing company needs a separate Corporate Tax registration. The company’s legal and tax position should be assessed based on the applicable rules and actual circumstances.
VAT registration and Corporate Tax registration are separate requirements, so businesses should assess each obligation independently.
The accounting system should be reviewed when the new activity creates different types of income, expenses or transactions.
Where appropriate, businesses may need to:
This can make it easier to measure the profitability of each activity and produce clearer financial and tax reports.
Invoices should accurately describe the goods or services supplied under the new activity.
Businesses should review:
The accounting records should also be supported by documentation that allows transactions to be traced from the underlying commercial activity to the financial statements and tax records.
Some activities may have requirements beyond a standard trade licence. Depending on the sector, businesses may need additional approvals, registrations or operating permissions.
This may be particularly relevant to businesses involved in:
Businesses should confirm the requirements applicable to their specific activity with the relevant UAE authority rather than assuming that a licence amendment covers every regulatory requirement.
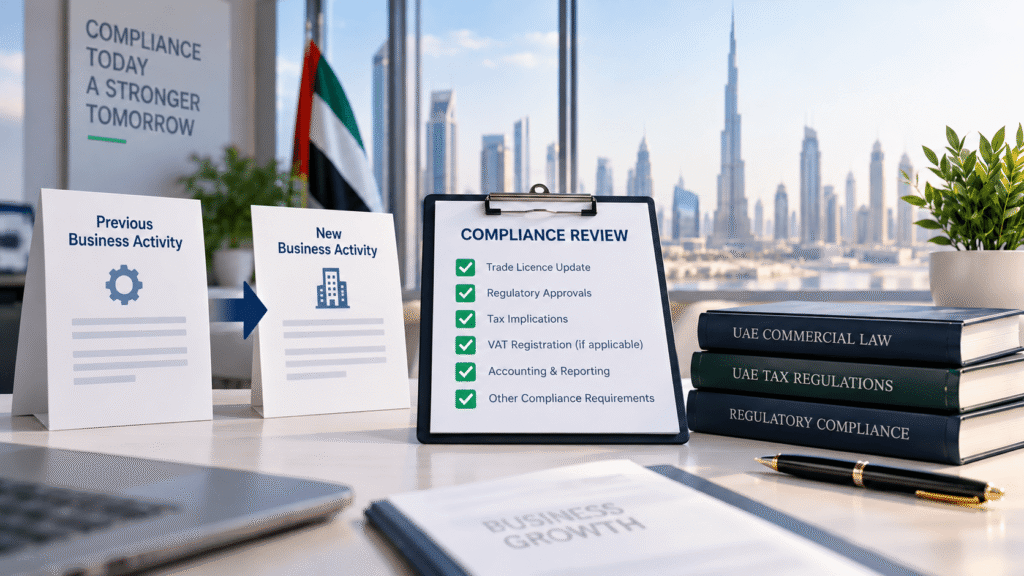
A trade activity tax review UAE should focus on whether the new activity changes how the business handles its existing tax and accounting processes.
| Area | Key Question |
| VAT | Does the new supply have a different VAT treatment? |
| Corporate Tax | Does the activity affect revenue, expenses or taxable income? |
| Registration | Do existing tax registration obligations remain appropriate? |
| Invoicing | Do invoice descriptions and VAT details need updating? |
| Accounting | Can revenue and related costs be classified correctly? |
| Records | Are sufficient supporting documents being maintained? |
| Returns | Are transactions being reflected correctly in tax filings? |
The important point is to assess the actual goods, services, income and expenses generated by the new activity rather than assuming that the licence amendment alone determines the tax treatment.
One of the most practical effects of adding a business activity is that the existing accounting structure may no longer provide enough detail.
Where practical, businesses can track different revenue streams separately. For example:
Separate categories can help management understand which activities are generating revenue and which are producing stronger margins.
Businesses should identify costs directly connected with the new activity and distinguish them from shared overheads. For example, a consultancy activity may generate professional fees, software costs and employee expenses, while a trading activity may involve inventory and purchasing costs. Recording these costs appropriately can make activity-level profitability easier to assess.
New activities may require additional accounting codes or categories so that transactions can be classified consistently.
The objective is not to create unnecessary complexity but to make the financial records useful for reporting, tax compliance and management decisions.
If the new activity involves inventory, projects or service delivery costs, the accounting system should capture these costs using an appropriate method.
Management accounts and profitability reports may also need new categories so that decision-makers can monitor the performance of the new activity separately.
A commercial business activity and tax registration are related but separate considerations. Adding an activity to a trade licence does not automatically mean that a business must obtain a completely new tax registration. Similarly, changing a licence does not by itself determine whether a particular transaction is subject to VAT or how income should be treated for Corporate Tax.
Businesses should instead consider:
This approach helps businesses avoid treating a commercial licence amendment as if it automatically determines their tax position.
Before starting a review, businesses can gather the documents that help establish what changed and how the new activity is being operated. These may include:
The exact documents required will depend on the nature of the activity and the company’s circumstances.
A structured review can be completed in six steps.
Document the old activity, new activity and date of the change.
Check whether the activity is correctly licensed and whether additional approvals are required.
Review the tax treatment of the new transactions and determine whether existing registration and reporting arrangements remain appropriate.
Update revenue accounts, expense categories, tax codes and other accounting settings where required.
Ensure invoices, contracts, accounting records and supporting documents reflect the new activity.
Record the review findings, identify outstanding issues and assign actions for correcting them.
Consider a UAE trading company that previously sold physical products but adds a consulting activity. The company should not simply start issuing consulting invoices under its existing trading accounts. Instead, it should review:
The company could then create a separate consulting revenue account and relevant expense categories. This would allow management to monitor the profitability of the new activity separately from its product sales.
The example illustrates why a licence amendment should trigger a broader review of the business’s accounting and compliance framework.
A professional review can be particularly useful when:
Professional support can help identify gaps without assuming that every business activity change requires the same treatment.
Changing a business activity can affect accounting, tax records and internal processes. Ripple Accountant provides compliance review and accounting support to help UAE businesses assess these changes and identify potential gaps. Support may include:
If your business has recently added or changed a trade activity, a tailored review can help determine whether your accounting, tax and documentation processes still align with the way your business operates. You can contact Ripple Accountant to avail these services!
Businesses should review their trade licence, regulatory approvals, VAT treatment, Corporate Tax implications, accounting records, invoices, contracts and supporting documentation. The exact checks depend on the activity being added or changed.
It can, depending on the goods or services associated with the new activity. Businesses should review the applicable VAT treatment and ensure their accounting and invoicing systems reflect it correctly. Adding an activity does not automatically mean a new VAT registration is required.
It may affect how new revenue and expenses are classified and reported, depending on the nature of the activity and the applicable Corporate Tax rules. Businesses should assess the actual transactions rather than assuming that a licence change automatically changes their Corporate Tax registration.
If the new activity creates different revenue streams, expenses or transaction types, the accounting system should generally be reviewed and updated where necessary. Separate revenue and expense categories can also make financial reporting more useful.
No. Requirements depend on the specific activity and licensing authority. Certain regulated sectors may require additional approvals or registrations, so businesses should verify the requirements applicable to their particular activity.
Changing a UAE business activity involves more than updating a trade licence. Businesses should consider the effect on accounting, invoicing, VAT, Corporate Tax, regulatory approvals and supporting documentation. A structured UAE business activity compliance review can help identify gaps early, particularly after adding a new trade activity or expanding into a different product or service. By reviewing the change systematically and updating accounting and compliance processes where necessary, businesses can maintain more accurate records and reduce the risk of avoidable compliance issues.
Disclaimer: This article is provided for general informational purposes only and does not constitute tax, accounting, legal or regulatory advice. UAE licensing, VAT, Corporate Tax and other compliance requirements may vary depending on the business activity, legal structure, licensing authority, transaction type and individual circumstances. Requirements and official guidance may also change. Businesses should verify the latest requirements with the relevant UAE authorities and obtain professional advice where necessary.
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
 VAT
When does VAT registration become mandatory for a UAE business, and when is it simply an option? For UAE businesses, the answer…
Read article Compliance
Are your employees being paid on time, and does your payroll data match what is being submitted through the Wage Protection System…
Read article Compliance
Have you recently added a new activity to your UAE trade licence? Before you start generating revenue from it, it is worth…
Read articlePage 9 of 45
Book a free consultation and get clear answers for your business.
0 Comments