IFRS vs GAAP: Which Standards Apply to UAE Businesses?
Introduction Choosing the right accounting standards is essential for every business operating in the UAE. Financial statements prepared under the correct framework…
Read article
Have you ever made a UAE tax payment only to find the liability still showing as unpaid in EmaraTax?
A bank transfer alone does not guarantee correct allocation. Tax payment reconciliation UAE procedures match the EmaraTax liability, bank payment, and accounting records, helping businesses prevent misallocated payments and maintain accurate tax records.
Tax payment reconciliation is the process of comparing a business’s tax liability and payment records with the corresponding bank transaction and accounting records.
In practical terms, the reconciliation connects:
EmaraTax liability → Payment reference → GIBAN/payment → Bank statement → Accounting records
The objective is to confirm that:
This process is especially important for businesses making regular VAT or Excise Tax payments, because multiple liabilities can exist at the same time.
An EmaraTax payment reference number is a unique reference generated when a taxpayer selects liabilities in EmaraTax for payment through GIBAN.
The FTA states that taxpayers making a GIBAN payment should first log into EmaraTax, select the liabilities they wish to pay and generate a unique payment reference number. The GIBAN, payment reference and exact amount linked to that reference should then be provided when making the payment.
The reference is important because it helps the FTA identify which selected liabilities the payment relates to.
For example, imagine that a UAE company has a VAT liability of AED 30,000. The accountant selects that liability in EmaraTax and generates a payment reference. The company then transfers AED 30,000 using the specified GIBAN and reference.
The accountant should not stop at the bank transfer. The final step is to confirm that the payment has been properly reflected and allocated in EmaraTax and that the company’s accounting records have also been updated.
GIBAN is the payment mechanism used by the FTA for certain bank transfers to settle tax liabilities. The FTA’s current payment guide explains that each taxable person has a GIBAN and that GIBAN payments can be used to settle outstanding VAT and Excise Tax amounts, including tax and penalties.
Businesses should understand that GIBAN payments are not simply ordinary bank transfers where the company sends money to an FTA beneficiary and assumes the system will determine the intended liability.
Before making a GIBAN payment, taxpayers need to use EmaraTax to select the relevant liabilities and create the payment reference.
The FTA states that for UAE-based banking channels, failure to provide the required GIBAN, payment reference and exact amount can result in the payment not being accepted. For overseas payments, incorrect or missing information could result in incorrect allocation.
The payment reference provides an important link between the bank payment and the selected liability.
Without proper reference information, the business may face uncertainty over whether the payment has been allocated to the correct tax obligation.
For example, a company may have:
If the accountant transfers money without following the appropriate payment process, the business may not get the allocation it expected.
This is why a tax payment reference UAE businesses use should be treated as a control document. It should be retained with the payment instruction, bank confirmation and accounting records.
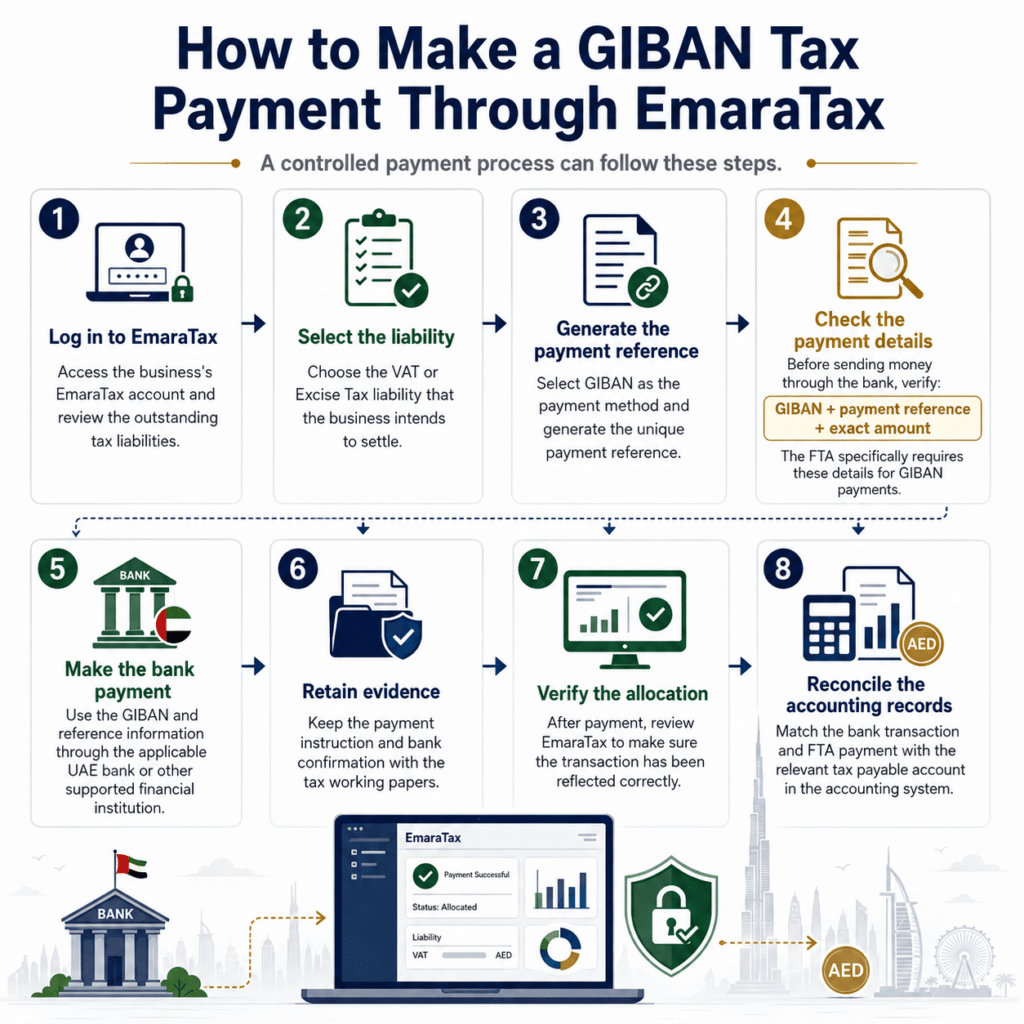
A controlled payment process can follow these steps.
Access the business’s EmaraTax account and review the outstanding tax liabilities.
Choose the VAT or Excise Tax liability that the business intends to settle.
Select GIBAN as the payment method and generate the unique payment reference.
Before sending money through the bank, verify:
The FTA specifically requires these details for GIBAN payments.
Use the GIBAN and reference information through the applicable UAE bank or other supported financial institution.
Keep the payment instruction and bank confirmation with the tax working papers.
After payment, review EmaraTax to make sure the transaction has been reflected correctly.
Match the bank transaction and FTA payment with the relevant tax payable account in the accounting system.
This is a small detail that can prevent avoidable errors. The FTA explains that the location of the payment reference field depends on the bank’s online banking portal. Where there is no separate payment-reference field, the taxpayer should enter the six digits of the payment reference number in the transaction remarks, comments or description field.
The FTA specifically advises that additional words should not be added around the reference. For example, the appropriate entry would be the six-digit reference itself rather than text such as “FTA reference 123456.”
Businesses should always follow the latest instructions of the FTA and their banking institution.
A good VAT payment reconciliation UAE process should be completed after the payment rather than treating the bank transfer as the final step.
Start with the liability selected in EmaraTax.
Confirm the:
Locate the outgoing transaction and compare the amount and transaction date with the payment instruction.
The FTA states that payment transactions can be viewed through the Transaction History section of the My Payments dashboard. Payment receipts can also be accessed through EmaraTax’s correspondence area.
The company’s accounting records should show the tax liability being reduced by the amount paid.
For example:
Before payment:
VAT payable = AED 50,000
Bank payment:
AED 50,000
After reconciliation:
VAT payable = AED 0
If the accounting system still shows AED 50,000 payable, the accountant should investigate rather than simply changing the ledger balance.
Consider a UAE trading company with the following records:
VAT liability in EmaraTax: AED 42,500
Payment reference: 654321
Bank payment: AED 42,500
Accounting VAT payable: AED 42,500
The accountant checks all four records and confirms that they agree.
The reconciliation can therefore be recorded as:
EmaraTax liability = AED 42,500
Bank payment = AED 42,500
Accounting liability = AED 42,500
After the payment is posted:
Outstanding VAT liability = AED 0
Now consider a different scenario. EmaraTax shows AED 42,500, but the bank statement shows a payment of AED 40,500. The accountant should not mark the liability as fully reconciled. The AED 2,000 difference needs to be investigated.
Possible causes could include an incorrect payment amount, an incomplete payment or another transaction being confused with the intended tax payment.
Misallocation can arise when businesses do not properly connect the payment with the liability selected in EmaraTax. Common control weaknesses include:
The FTA allows taxpayers to generate separate payment references for individual liabilities or a payment reference covering a combination of liabilities of the same tax type. Multiple payment references can also be generated simultaneously, subject to the FTA’s rules. This creates an important internal-control opportunity.
Instead of making several unexplained bank transfers, the finance team can maintain a payment schedule containing:
| Tax Type | Liability | Amount | Reference | Bank Payment | FTA Status |
| VAT | VAT return | AED 25,000 | 123456 | AED 25,000 | Settled |
| VAT | Penalty | AED 2,000 | 234567 | AED 2,000 | Settled |
| Excise Tax | Monthly return | AED 18,000 | 345678 | AED 18,000 | Settled |
This gives management and the accounting team a clear audit trail.
Advance payments need additional attention because they are not necessarily applied to the liability a business has just filed.
The FTA provides an example where a taxpayer makes an advance payment toward a subsequent tax period. That payment can be held on account until the relevant subsequent return is filed rather than being automatically allocated to the immediately preceding return.
Therefore, businesses should distinguish between:
The accounting team should retain documentation showing the purpose of each payment.
A strong bank reconciliation UAE process should include tax-specific controls rather than treating FTA payments like ordinary supplier payments.
Businesses can establish the following monthly procedure:
A second-person review can also be useful for companies with larger payment volumes. One employee prepares the payment while another verifies the liability, amount, and payment information before authorisation.
Tax payment reconciliation works best when supporting documents are stored together.
A business should maintain an organised record of relevant:
This creates an audit trail connecting the tax return to the payment and ultimately to the accounting ledger.
Managing tax payments involves more than transferring money from a bank account. Businesses need to make sure their liabilities, payments, and accounting records remain consistent.
Ripple Accountant can support UAE businesses with bookkeeping, bank reconciliation, VAT-related accounting support, tax payment reconciliation, and maintenance of organized financial records.
By integrating tax-payment checks into regular accounting procedures, businesses can identify unmatched transactions and outstanding tax balances earlier.
Contact Ripple Accountant to discuss your UAE accounting requirements.
Tax payment reconciliation is the process of matching an FTA tax liability and payment with the related bank transaction and accounting records to ensure the payment has been correctly recorded and allocated.
It is a unique reference generated in EmaraTax when a taxpayer selects liabilities for payment through GIBAN. The FTA requires the relevant reference, GIBAN and exact amount to be used when making the payment.
For GIBAN payments, the FTA states that taxpayers must first select the relevant liabilities in EmaraTax and generate a unique payment reference.
The FTA says previous payment transactions can be viewed through Transaction History under My Payments in EmaraTax. Payment receipts can also be downloaded through My Correspondence.
Yes. The FTA allows taxpayers to create a reference for an individual liability or a combination of liabilities of the same tax type, subject to the applicable system rules.
First compare the EmaraTax liability, payment reference, amount and bank transaction. Review the payment status and supporting documents in EmaraTax. Where the issue remains unresolved, the business should contact the FTA and retain evidence of the payment and attempted resolution.
Accurate tax payment reconciliation UAE businesses perform should go beyond checking whether money has left the bank account. The complete process connects the EmaraTax liability, payment reference, GIBAN transaction, bank statement and accounting records.
Disclaimer: This article provides general information about UAE tax payments, EmaraTax and accounting reconciliation. Tax procedures and requirements may vary according to the taxpayer’s circumstances and applicable UAE legislation. Businesses should verify current requirements with the Federal Tax Authority or obtain advice from a qualified UAE tax professional before making tax-related decisions.
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
 Compliance
Introduction Choosing the right accounting standards is essential for every business operating in the UAE. Financial statements prepared under the correct framework…
Read article Corporate Tax
Every individual and business wants to reduce its tax burden legally. Effective tax planning helps minimize taxes while remaining fully compliant with…
Read article Corporate Tax
A Tax Residency Certificate (TRC) is an important document for businesses and individuals operating in the UAE. It proves that the certificate…
Read articlePage 36 of 45
Book a free consultation and get clear answers for your business.
0 Comments