Ethical Considerations in Tax Avoidance vs Tax Planning
Every individual and business wants to reduce its tax burden legally. Effective tax planning helps minimize taxes while remaining fully compliant with…
Read article
Do your group companies share loans, employees, management services, office space or other resources?
If so, these arrangements may create related party transactions UAE tax considerations that should be reviewed as part of Corporate Tax compliance. This is especially important for owner-managed groups with common shareholders, directors or control. UAE transfer pricing rules require relevant transactions involving Related Parties and Connected Persons to follow the arm’s-length principle and can apply to both domestic and cross-border transactions. For SMEs, the key challenge is understanding which transactions need review, how pricing should be supported and what documentation should be maintained.
A related-party transaction is broadly a transaction or arrangement between parties that have a prescribed relationship through ownership, control or, in certain cases, family relationships. Common examples include transactions between:
The transaction itself can take many forms. It does not have to be a traditional sale or purchase.
For example, a UAE holding company might provide accounting, HR and management services to three subsidiaries. The subsidiaries may then pay management or service fees to the holding company.
That arrangement should be reviewed from both an accounting and UAE Corporate Tax perspective.
UAE Corporate Tax legislation distinguishes between Related Parties and Connected Persons. The concepts can overlap, but they are not identical.
Related-party rules generally focus on relationships involving ownership, control and certain relationships between individuals. Connected-person provisions can apply to transactions involving owners, directors, officers and other specified persons depending on the circumstances.
The distinction matters because different Corporate Tax provisions and compliance considerations may apply.
Therefore, an SME should not simply create a list of companies with common shareholders and assume that the review is complete. It should identify the relevant Related Parties and Connected Persons under the applicable UAE rules.
The UAE Corporate Tax regime includes transfer pricing rules designed to ensure that relevant transactions between Related Parties and Connected Persons are conducted on an arm’s-length basis.
The Federal Tax Authority explains that transfer pricing rules seek to ensure that transactions between Related Parties are carried out as if the parties were independent of one another.
This helps prevent relationships between parties from influencing the price or conditions of a transaction in a way that artificially shifts taxable profits. Importantly, UAE transfer pricing rules can apply to both domestic and cross-border transactions.
That means an SME should not assume that transfer pricing is relevant only when it has transactions with an overseas parent or subsidiary.
The arm’s-length principle means that the conditions of a transaction between related parties should generally be consistent with what independent parties would have agreed under comparable circumstances.
For example, imagine that Company A owns Company B.
Company A provides IT support to Company B and charges AED 500,000 per year.
A tax review should consider whether:
The objective is not simply to find a market price from the internet.
A proper analysis considers the specific characteristics of the transaction and the functions, assets and risks of the parties involved. The FTA’s transfer pricing guidance describes comparability analysis as a central part of applying the arm’s-length principle.
Not every business has the same transactions. However, the following areas deserve particular attention.
Management fees are common in owner-managed groups. A parent or holding company may provide:
The SME should maintain evidence showing what services were provided and why the amount charged is appropriate.
An invoice labelled simply “management services – AED 200,000” may not provide enough commercial context by itself.
The business should ideally be able to explain the nature of the services, how the charge was calculated and which entity benefited from them.
Intercompany financing is another important area.
A UAE company may lend money to:
The terms should be reviewed carefully. Relevant factors may include:
The FTA specifically confirms that transfer pricing rules apply to intra-group loans and that factors such as the interest rate and duration need to be considered when determining whether the arrangement is at arm’s length.
Trading groups may buy and sell products between companies under common ownership.
For example, a UAE distributor might purchase products from a related company and then sell them to independent customers.
The review should consider:
The pricing should be supported by an appropriate transfer pricing analysis where required.
A group may have employees who work for multiple companies.
For example, a finance manager could spend 60% of their working time supporting Company A and 40% supporting Company B.
If Company A employs the person and Company B reimburses part of the cost, the arrangement should be documented and the allocation methodology should be reasonable.
The business should be able to explain:
Related companies may share:
If one company pays the full cost and charges another company, the allocation should have a reasonable commercial basis.
A simple percentage allocation without supporting reasoning can create questions later.
A practical review can be divided into several stages.
Start by identifying:
This helps determine which relationships may fall within the Related Party or Connected Person rules.
Once the relationships are identified, review the accounting records.
Search for:
The general ledger can often reveal transactions that management may not have considered from a transfer pricing perspective.
Do not review only the accounting entry.
Ask:
What actually happened?
For example, if a company records AED 300,000 as a management fee, determine:
Understanding the commercial substance is essential to a meaningful review.
The next question is whether the price or conditions are consistent with the arm’s-length principle.
The UAE transfer pricing framework recognises internationally accepted transfer pricing methods, including approaches based on comparable prices, resale prices, cost plus and transactional net margins, among others.
The appropriate method depends on the transaction and available information.
Supporting documents can include:
The FTA states that taxpayers may need to provide information supporting the arm’s-length nature of their related-party transactions and arrangements.
One common misconception is that every UAE SME automatically needs a full master file and local file.
That is not the case. Ministerial Decision No. 97 of 2023 sets specific conditions for taxpayers that must maintain both a master file and local file. These include, among other conditions, a taxpayer with revenue of at least AED 200 million in the relevant Tax Period, or a constituent company of an MNE group meeting the specified consolidated revenue threshold.
However, the absence of a master-file/local-file requirement does not mean that a business can ignore transfer pricing.
The FTA may require taxpayers to provide information supporting their related-party transactions, and businesses should maintain appropriate records relevant to their tax position.
Therefore, smaller businesses should distinguish between: Transfer pricing compliance and specific formal documentation requirements. They are not necessarily the same thing.
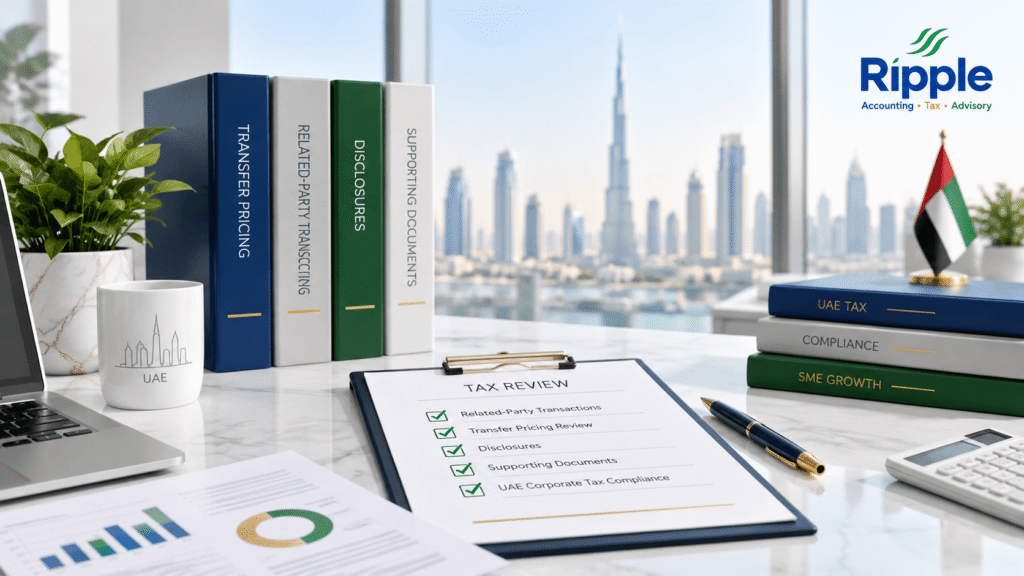
A business can use the following checklist as a starting point:
A related-party review is particularly useful when a business:
A review can also be useful when the business has grown significantly and informal arrangements created during its early years are no longer appropriate for its current structure.
Transfer pricing should be considered as part of the wider Corporate Tax compliance process.
The FTA can require certain information about transactions and arrangements with Related Parties and Connected Persons. The FTA’s Corporate Tax guidance explains that taxpayers may need to provide information supporting how transfer prices were determined and why they are comparable with independent-party transactions.
Businesses should therefore avoid treating transfer pricing as a separate issue that only matters when preparing special documentation. It should be incorporated into the broader tax review process.
Another important point for UAE SMEs is that transfer pricing is not limited to international transactions.
The FTA confirms that transfer pricing rules apply to transactions with Related Parties and Connected Persons whether those parties are located in the UAE mainland, a Free Zone or a foreign jurisdiction.
For example, a UAE group with three companies operating in Dubai, Abu Dhabi and Sharjah should not assume that domestic transactions automatically fall outside transfer pricing considerations.
The same principle applies when a UAE company transacts with a related company overseas.
A practical first step is to create a related-party transaction register. The register can include:
| Related party | Transaction | Amount | Terms | Supporting document |
| Parent company | Management fee | AED 250,000 | Annual | Service agreement |
| Sister company | Loan | AED 1 million | Interest-bearing | Loan agreement |
| Subsidiary | IT services | AED 120,000 | Monthly | Service invoices |
| Shareholder | Loan | AED 300,000 | As agreed | Loan documentation |
Once the transactions are listed, management can assess which arrangements require further transfer pricing analysis or documentation.
This is usually much more effective than waiting until the Corporate Tax return is being prepared and trying to identify all related-party transactions at once.
Related-party arrangements can become difficult to assess when a business has multiple entities, shareholder transactions, intercompany loans or shared services.
Ripple Accountants can help businesses review their tax position, identify potential compliance gaps and assess related-party arrangements as part of broader UAE tax advisory support. A structured UAE tax review can help business owners understand which transactions require further attention and what supporting records should be maintained. You can Contact Ripple Accountants to discuss your requirements.
They are transactions or arrangements between parties that meet the relevant Related Party criteria under UAE Corporate Tax rules. Examples include intercompany loans, management fees, sales, purchases and shared services.
Yes. Being an SME does not automatically exclude a business from UAE transfer pricing rules. The specific compliance and documentation requirements depend on the business and its transactions.
Yes. UAE transfer pricing rules can apply to both domestic and cross-border transactions involving Related Parties and Connected Persons.
No. Ministerial Decision No. 97 of 2023 establishes specific conditions for maintaining both files. For example, one condition is revenue of AED 200 million or more in the relevant Tax Period, while another applies to qualifying constituent companies of large multinational groups.
Yes. The FTA states that transfer pricing rules apply to loans between Related Parties and Connected Persons, including consideration of terms such as interest rate and duration.
UAE SMEs should regularly review related-party transactions to ensure pricing, documentation and reporting are aligned with UAE Corporate Tax and transfer pricing requirements. Identifying related parties, applying the arm’s-length principle and maintaining proper records can help businesses reduce compliance risks and strengthen their tax position.
Disclaimer: This article provides general information about related party transactions UAE tax requirements and is not a substitute for professional tax, accounting or legal advice. The applicable treatment can depend on the nature of the parties, transaction, ownership structure, accounting records and other facts. UAE Corporate Tax and transfer pricing legislation and guidance may be updated, so businesses should verify the current requirements with the Federal Tax Authority and obtain professional advice where appropriate.
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
 Corporate Tax
Every individual and business wants to reduce its tax burden legally. Effective tax planning helps minimize taxes while remaining fully compliant with…
Read article Corporate Tax
A Tax Residency Certificate (TRC) is an important document for businesses and individuals operating in the UAE. It proves that the certificate…
Read article Bookkeeping
Businesses today are expanding faster than ever, thanks to digital technology, online sales, and global markets. As operations grow, managing finances with…
Read articlePage 36 of 45
Book a free consultation and get clear answers for your business.
0 Comments