Key Differences Between Bookkeepers and Accountants: Complete Business Guide
Managing business finances is one of the most important responsibilities for any business owner. Whether you run a startup, a small business,…
Read article
Are your business transactions properly recorded every month, or do you only review your accounts when a tax filing or financial deadline is approaching?
For UAE SMEs, regular bookkeeping is more than recording income and expenses. A consistent monthly bookkeeping checklist UAE businesses can follow helps identify errors, reconcile accounts, monitor cash flow and keep financial records ready for tax and reporting requirements. A structured monthly review also gives business owners a clearer picture of profitability and outstanding payments. Instead of allowing accounting issues to accumulate, SMEs can identify and correct them while the information is still recent and easier to verify.
Bookkeeping provides the financial records that businesses use to understand their performance and prepare financial information for tax purposes.
The UAE Corporate Tax framework generally starts with accounting income when determining taxable income, followed by the required tax adjustments. This makes accurate accounting records an important part of the wider Corporate Tax compliance process. For SMEs, monthly bookkeeping can help with:
The objective is not simply to “close the books” each month. It is to make sure the financial information reflects what actually happened in the business.
A monthly bookkeeping process should be consistent. While the exact tasks depend on the nature and size of the business, most UAE SMEs can use the following checklist as a starting point.
Start by making sure all sales and other business income for the month have been recorded. Compare your accounting system with sales invoices, receipts, online payment platforms and other relevant records. If the business receives payments through multiple channels, each channel should be accounted for.
Check for:
This review is particularly important for businesses with high transaction volumes, online sales or multiple payment channels.
The next step in bookkeeping UAE SMEs should be reviewing expenses recorded during the month. Make sure business expenses are supported by appropriate invoices, receipts or other documentation. Expenses should also be recorded under the correct accounting category.
Review areas such as:
Avoid waiting until year-end to discover that several months of expenses have been incorrectly classified.
Bank reconciliation is one of the most important monthly accounting tasks UAE businesses should complete. Compare the bank statement with the transactions recorded in your accounting system. The ending balance in the books should be reconciled with the bank balance after considering legitimate timing differences.
Look for:
If your business operates multiple bank accounts, each account should be reconciled separately.
Regular reconciliation makes unusual transactions easier to identify and prevents small errors from becoming larger accounting problems.
Bank accounts are not the only financial accounts that require reconciliation. If your business uses corporate credit cards, payment gateways or platforms such as online payment processors, review these accounts every month as well.
Match:
Transaction → Customer payment → Platform record → Bank receipt → Accounting entry
Check whether transaction fees, refunds and chargebacks have been correctly recorded.
This is particularly important for e-commerce businesses and companies that receive customer payments through multiple platforms.
Accounts receivable shows how much customers still owe the business. At the end of each month, review outstanding customer invoices and identify overdue balances.
A useful review can separate receivables into:
This helps management decide which customers require follow-up and whether any balances may require further assessment.
A growing sales figure does not necessarily mean a healthy cash position if customers are taking too long to pay.
The same principle applies to supplier balances. Review unpaid supplier invoices and confirm that the amounts recorded in the accounting system agree with supplier statements where available.
Check for:
Keeping accounts payable updated gives business owners a clearer view of upcoming cash requirements.
Payroll should also form part of the monthly bookkeeping checklist UAE SMEs use. Compare payroll records with accounting entries and payment records. Depending on the business, this may include salaries, allowances, deductions, employee advances, benefits and other payroll-related costs.
For businesses subject to UAE payroll and WPS requirements, accounting records should also be consistent with the relevant payroll documentation.
Any difference between payroll records, salary payments and accounting entries should be investigated rather than carried forward without explanation.
If the business is VAT registered, VAT-related transactions should be reviewed regularly rather than only before submitting the VAT return.
Check whether:
Monthly VAT reviews can make the eventual VAT return preparation more efficient and help identify errors earlier.
Businesses should always assess their transactions against the applicable UAE VAT legislation and FTA guidance rather than relying only on accounting software classifications.
If the business purchases equipment, vehicles, computers, furniture or other significant assets, check whether these transactions have been correctly recorded.
A monthly review should consider:
Maintaining an updated fixed asset register helps ensure that financial statements accurately reflect the company’s assets.
For businesses that hold inventory, bookkeeping should be connected with stock records. Compare accounting records with inventory movements where appropriate and investigate significant differences.
Review:
Poor inventory records can affect both the balance sheet and reported profit because inventory and cost of sales are closely connected.
If the business has bank loans, shareholder loans or other financing arrangements, update the relevant accounting records each month.
Check:
For related-party arrangements, businesses should maintain appropriate supporting documentation and consider the applicable UAE Corporate Tax and transfer pricing requirements.
Not every expense belongs entirely to the month in which it is paid.
For example, a business may pay an annual insurance premium in January even though the expense relates to the entire year.
Similarly, an expense may have been incurred during the month but the supplier invoice may not arrive until later.
Monthly bookkeeping should therefore consider:
Correct treatment helps ensure that monthly financial reports provide a more realistic picture of business performance.
Accounting systems sometimes contain transactions that have not yet been assigned to the correct account.
Do not allow these balances to accumulate.
Review:
Each transaction should eventually be supported and classified appropriately.
A large suspense balance at year-end can make financial reporting and tax preparation much more difficult.
Once the bookkeeping entries are complete, compare the current month’s results with previous periods.
Look at:
Large or unexpected movements should be investigated. For example, if marketing expenses suddenly increase by 80%, management should determine whether this reflects a genuine campaign, an annual payment or an accounting error.
This simple comparison can turn bookkeeping into a useful management tool rather than a purely administrative task.
A good bookkeeping process UAE SMEs can adopt should finish with basic financial reporting.
Depending on the business, monthly reports may include:
These reports help business owners make decisions based on current financial information rather than outdated records.
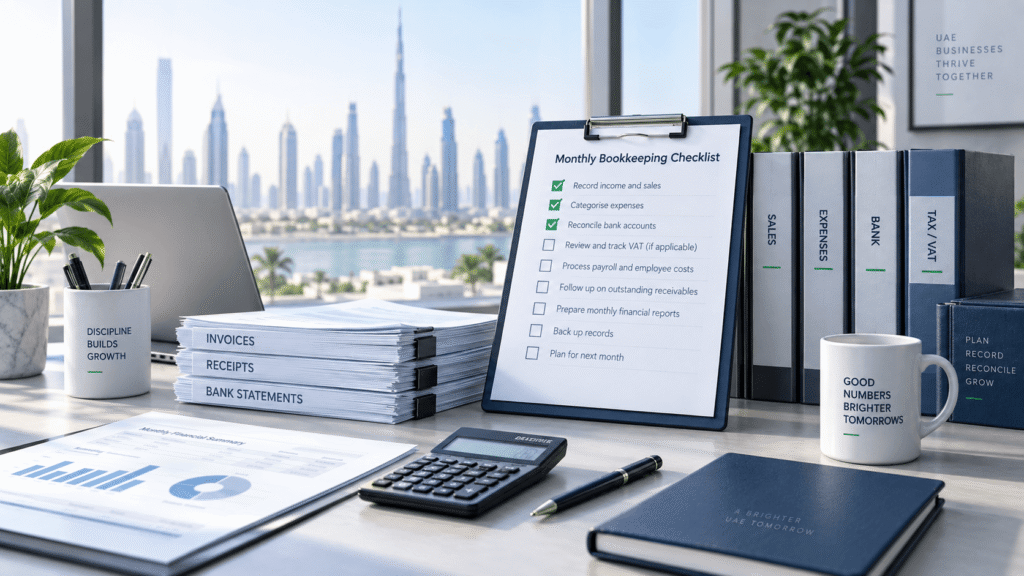
SMEs can use the following simplified checklist at the end of every month:
| Area | Monthly Check |
| Sales | Record and verify all sales invoices |
| Expenses | Check invoices, receipts and classifications |
| Bank | Reconcile every business bank account |
| Credit cards | Match transactions and payments |
| Receivables | Review outstanding customer balances |
| Payables | Review unpaid supplier invoices |
| Payroll | Match payroll with accounting and payment records |
| VAT | Review VAT-related transactions |
| Inventory | Reconcile stock records where applicable |
| Fixed assets | Update purchases, disposals and depreciation |
| Loans | Update principal, interest and balances |
| Accruals | Record expenses relating to the current period |
| Prepayments | Allocate prepaid expenses correctly |
| Suspense | Clear unidentified or unclassified transactions |
| Reporting | Review monthly financial statements |
This checklist can be adjusted depending on the size, industry and transaction volume of the business.
Monthly bookkeeping should generally be treated as a minimum routine for businesses that have regular sales, purchases, payroll or other financial transactions. However, the frequency can depend on transaction volume. A business with hundreds of daily transactions may benefit from weekly or even daily recording and reconciliation. A smaller business with fewer transactions may be able to complete detailed bookkeeping monthly. The important point is consistency.
Leaving accounting records untouched for several months makes it harder to identify missing invoices, forgotten expenses and unexplained bank transactions.
Bookkeeping also supports the business’s wider UAE Corporate Tax compliance obligations. The Federal Tax Authority states that taxpayers should maintain financial statements and documents supporting information reported in Corporate Tax returns and other filings. The FTA also states that relevant records and documents generally need to be retained for at least seven years following the end of the relevant Tax Period.
Businesses should therefore maintain an organised recordkeeping system rather than treating bookkeeping as a temporary administrative task.
The FTA’s current legislation resources also include FTA Decision No. 4 of 2026, which sets out rules and requirements for maintaining information contained in accounting records and commercial books.
Even businesses with accounting software can experience bookkeeping problems.
Common mistakes include:
A business should consider reviewing its bookkeeping process if:
Growth often increases accounting complexity. A bookkeeping process that worked for a small business may need to be updated as transaction volumes increase.
Keeping bookkeeping records accurate and up to date can be challenging for UAE SMEs, especially when business owners are managing daily operations alongside financial responsibilities. Ripple Accountant can provide practical accounting and bookkeeping support to help businesses maintain organized records and identify potential gaps. Support may include:
If your business needs help keeping its books accurate and up to date, Contact Ripple Accountant to discuss your requirements.
A UAE SME should review sales, expenses, bank accounts, receivables, payables, payroll, VAT-related transactions, inventory, fixed assets and other relevant financial records. Monthly financial reports should also be reviewed for unusual changes.
Monthly bookkeeping helps businesses keep financial records accurate and up to date. It can also make VAT and Corporate Tax preparation easier by ensuring transactions and supporting documentation are reviewed throughout the year.
For UAE Corporate Tax purposes, relevant records and documents generally need to be retained for at least seven years following the end of the relevant Tax Period.
Yes. Monthly bank reconciliation helps identify missing transactions, duplicate entries, bank charges and other differences between accounting records and bank statements.
Yes. A checklist can provide a simple structure for completing recurring accounting tasks and help ensure important areas are not overlooked. The checklist should be adapted to the business’s transaction volume, industry and tax obligations.
A consistent monthly bookkeeping checklist UAE SMEs can follow helps keep financial records accurate, identify errors early and provide better visibility into business performance. By regularly reviewing transactions, reconciling accounts and maintaining supporting records, SMEs can build a stronger foundation for financial reporting and UAE tax compliance.
Disclaimer: This article provides general information for UAE businesses and should not be considered tax, accounting, or legal advice. Businesses should assess their specific circumstances and refer to the latest UAE legislation and Federal Tax Authority guidance or seek professional advice where required.
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
 Bookkeeping
Managing business finances is one of the most important responsibilities for any business owner. Whether you run a startup, a small business,…
Read article Bookkeeping
Businesses no longer have the luxury of waiting until the end of the month to understand their financial performance. Markets change quickly,…
Read article Bookkeeping
The education sector in the UAE has experienced remarkable growth over the past decade. From private schools and universities to vocational training…
Read articlePage 43 of 45
Book a free consultation and get clear answers for your business.
0 Comments