UAE Tax Planning for Mainland and Free Zone Groups
M Maria September 15, 2026 11 min read
Is your UAE business group making the most of its mainland and Free Zone structure?
When a group operates through both mainland and Free Zone companies, its Corporate Tax position can depend on how each entity is structured, what it does and how the companies work with each other. Free Zone businesses may qualify for a 0% rate on certain income, but specific conditions apply.
Understanding these rules is essential for effective mainland free zone tax planning UAE. Let’s look at the key tax considerations UAE groups should know before making structural decisions.
What Is Tax Planning for a Mainland and Free Zone Group?
UAE group tax planning means reviewing how different companies, branches, activities, transactions and sources of income fit within the UAE Corporate Tax framework.
A group may, for example, have:
A mainland operating company serving UAE customers
A Free Zone company carrying out qualifying activities
A holding company
Shared employees or management
Intercompany loans or financing
Management or support services between entities
Intellectual property or other assets held by one group company
Each entity should not automatically be treated as having the same tax position.
The Ministry of Finance confirms that Free Zone juridical persons are within the scope of UAE Corporate Tax. However, a Free Zone Person that satisfies the requirements to become a Qualifying Free Zone Person can benefit from a 0% Corporate Tax rate on Qualifying Income.
This makes UAE group tax planning a matter of understanding the activities and transactions of each entity rather than simply assuming that a Free Zone licence creates a tax advantage.
Mainland and Free Zone Tax Treatment: What Should Groups Understand?
Mainland companies
Mainland companies generally fall within the UAE Corporate Tax regime and calculate taxable income under the applicable Corporate Tax rules.
For a business operating through several entities, the tax analysis should consider:
The nature of each entity’s business
Sources of income
Deductible expenditure
Related-party transactions
Tax losses and available reliefs
Ownership relationships
Whether a Tax Group is possible
Transfer pricing requirements
Financial reporting and record-keeping
The objective should be to establish a structure that is commercially practical while remaining consistent with the Corporate Tax legislation.
Free Zone companies
A Free Zone company is not automatically outside UAE Corporate Tax. The FTA explains that a Free Zone Person must meet specific conditions to qualify for the Free Zone Corporate Tax regime. These include requirements relating to Qualifying Income, adequate substance, the de minimis requirement, transfer pricing compliance and other prescribed conditions.
The rules also distinguish between Qualifying Income and income that is subject to the standard Corporate Tax treatment.
The FTA’s dedicated Free Zone Persons guide provides detailed examples of how income attributable to a Domestic Permanent Establishment and other activities may be treated.
Why the distinction matters
A group should therefore avoid a planning approach based simply on:
“Put the profitable activity in a Free Zone and the rest in the mainland.”
The tax treatment depends on what the entity actually does, who it transacts with, where activities are performed, how income is generated and whether the relevant conditions are maintained.
Can a Mainland and Free Zone Company Form One UAE Tax Group?
This is one of the most important considerations for UAE group tax planning. The UAE Tax Group regime allows qualifying UAE resident companies to apply to be treated as a single taxable person. However, the rules contain specific conditions.
According to the FTA, the UAE-resident parent must generally hold at least 95% of the share capital and voting rights in each subsidiary, directly or indirectly. The companies must also meet other requirements, including having the same financial year and using the same accounting standards.
Importantly, an entity that is a Qualifying Free Zone Person benefiting from the 0% Free Zone Corporate Tax rate cannot be a member of a Tax Group.
This means a group with mainland and Free Zone companies should assess Tax Group eligibility before assuming that all entities can be consolidated for UAE Corporate Tax purposes.
Practical planning question
Consider a group with:
Mainland Company A
Mainland Company B
Free Zone Company C
If Company C qualifies for the Free Zone 0% regime, the group cannot simply include it in a Tax Group alongside the mainland companies.
The group may therefore need to assess the tax treatment of each entity separately and determine whether its commercial arrangements and intercompany transactions are appropriately structured.
How Should Groups Review Free Zone Qualifying Income?
One of the central areas of mainland free zone tax planning UAE is identifying which income may qualify for the Free Zone 0% rate.
The UAE framework distinguishes between Qualifying Income and non-Qualifying Income. The Ministry of Finance has issued decisions defining the relevant categories, while the FTA provides detailed guidance and examples.
For example, qualifying treatment can depend on:
The nature of the activity
Whether the customer is another Free Zone Person
Whether the transaction relates to a Qualifying Activity
Whether an activity falls within an Excluded Activity
Whether income is attributable to a Domestic or Foreign Permanent Establishment
Whether the Free Zone entity continues to satisfy the applicable conditions
Businesses should therefore maintain a clear connection between their commercial activities, contracts, accounting records and tax treatment.
2025 update to Free Zone activities
Businesses should also avoid relying indefinitely on older Free Zone guidance.
The Ministry of Finance announced in September 2025 that Ministerial Decision No. 229 of 2025 replaced Ministerial Decision No. 265 of 2023 concerning Qualifying Activities and Excluded Activities. The updated decision also clarified areas including qualifying commodity trading and treasury and financing services for Related Parties.
This is particularly relevant for groups whose structures involve trading, financing, treasury or related-party services.
Related-Party Transactions Between Mainland and Free Zone Entities
A mainland company and a Free Zone company under common ownership may have numerous transactions between them.
Examples include:
Management fees
Shared administrative services
Intercompany loans
Interest payments
Cost allocations
Sale of goods
IT and technical services
Marketing support
Licensing arrangements
Employee or resource sharing
These transactions should not be priced arbitrarily simply because the companies belong to the same group.
The FTA confirms that UAE transfer pricing rules apply to transactions involving Related Parties and Connected Persons, including transactions where the parties are located in the UAE mainland, a Free Zone or another jurisdiction.
The arm’s-length principle is therefore an important part of UAE group tax planning.
Why transfer pricing matters
Suppose a Free Zone company provides services to a mainland group company.
The group should consider:
What services are actually provided?
Which entity performs the relevant functions?
What assets and resources are used?
Which entity assumes the relevant risks?
What would independent parties reasonably charge?
What supporting agreements and records exist?
The answer should be reflected consistently in the accounting and tax records.
The FTA explains that transfer pricing rules are intended to ensure Related Party transactions are carried out on arm’s-length terms, as though the transactions were between independent parties.
Substance Should Be Part of the Planning Process
Tax planning should not focus only on licences, ownership and tax rates. For a Free Zone entity seeking Qualifying Free Zone Person status, adequate substance in the UAE is one of the relevant requirements.
A group should therefore consider whether its Free Zone entity has an appropriate operational presence for the activities it claims to conduct.
Depending on the business, this may involve reviewing:
Employees and responsibilities
Office or operating arrangements
Assets
Management functions
Business activity
Decision-making
Contracts
Accounting records
Actual operational activity
The purpose is not to create artificial arrangements. Instead, the legal structure, commercial activity and tax position should be aligned.
A Practical Tax Planning Checklist for UAE Groups
Before changing or implementing a mainland and Free Zone structure, management can review the following areas.
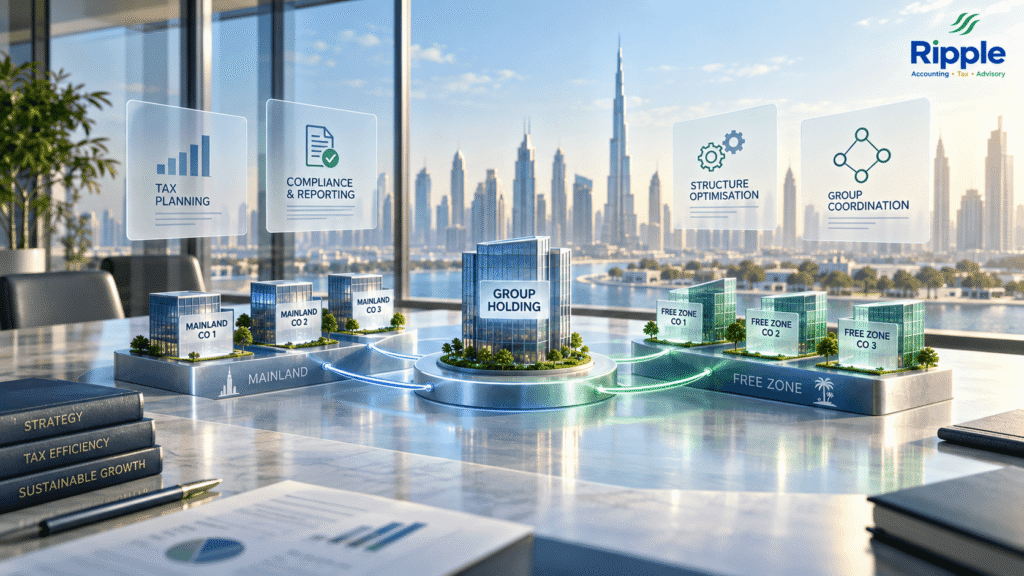
1. Map every group entity
Prepare a simple structure chart showing:
Ownership
Jurisdiction
Free Zone or mainland status
Business activity
Branches
Related entities
Key revenue streams
2. Categorise revenue
For each entity, identify:
UAE mainland customers
Free Zone customers
Overseas customers
Related-party customers
Revenue from different business activities
This can help identify where further Free Zone and Corporate Tax analysis is required.
3. Review intercompany arrangements
List all significant transactions between group companies and check whether they have:
Written agreements
Clear commercial purposes
Appropriate pricing
Supporting invoices
Accounting records
Transfer pricing support where applicable
4. Test Free Zone eligibility
A Free Zone entity should be assessed against the current conditions rather than assuming that its licence alone provides access to the 0% regime.
The FTA’s official Free Zone Persons guide is particularly useful because it explains Qualifying Income, Excluded Activities, substance, Permanent Establishments and compliance requirements.
5. Assess Tax Group eligibility
If the group wants to consolidate mainland entities for Corporate Tax purposes, check ownership, voting rights, financial years, accounting standards and the other Tax Group conditions.
Do not include a Qualifying Free Zone Person benefiting from the 0% regime in the Tax Group structure.
6. Review the structure annually
Tax planning should not be treated as a one-time exercise.
Changes in:
Ownership
Activities
Customers
Free Zone regulations
Related-party arrangements
Business locations
Revenue streams
Corporate Tax decisions
may affect the group’s tax position.
Common Mistakes in Mainland Free Zone Tax Planning
Assuming every Free Zone income stream is taxed at 0%
The 0% rate applies to Qualifying Income for a Qualifying Free Zone Person, subject to the applicable rules. It is not a blanket exemption for all income earned by every Free Zone company.
Treating mainland and Free Zone companies as completely separate
Even where companies have separate licences and legal identities, transactions between them may create transfer pricing and documentation considerations.
Moving activities without reviewing the tax consequences
Changing contracts, customers, employees or functions between entities can affect the tax analysis.
Using outdated Free Zone rules
The Free Zone rules have developed since Corporate Tax was introduced. The 2025 replacement of the earlier Ministerial Decision on Qualifying Activities and Excluded Activities demonstrates why businesses should verify the current rules before making structural decisions.
Ignoring the accounting impact
Tax planning should connect with accounting records. Different entities may need separate financial information, reconciliations and supporting documentation to demonstrate how taxable income was determined.
How Ripple Can Help With UAE Group Tax Planning
Managing a group with mainland and Free Zone entities can become complicated when Corporate Tax, Free Zone eligibility, related-party transactions and financial records need to be considered together.
Ripple Accountants can help businesses review their group structure and identify the key tax and compliance considerations before making significant changes. Ripple’s tax advisory support can be used to assess areas such as:
Considering a mainland and Free Zone structure? Contact Ripple Accounting, Tax & Advisory to discuss your group structure, transactions and UAE Corporate Tax position and determine where a detailed tax review may be appropriate.
Email: info@uaetaxcompliance.ae
Phone: +971 52 356 5409
WhatsApp: +971 4 250 0833
FAQs
1. Can a UAE group have both mainland and Free Zone companies?
Yes. A group can operate through both mainland and Free Zone entities. However, each entity’s Corporate Tax position and the transactions between group companies should be assessed separately where required.
2. Does a Free Zone company automatically get 0% Corporate Tax?
No. A Free Zone Person must satisfy the conditions to be a Qualifying Free Zone Person, and the 0% rate applies to its Qualifying Income under the applicable rules.
3. Can a Qualifying Free Zone Person join a UAE Corporate Tax Group?
No. The FTA states that a Qualifying Free Zone Person benefiting from the 0% Free Zone Corporate Tax regime cannot be a member of a Tax Group.
4. Do transfer pricing rules apply between mainland and Free Zone companies?
Yes. The FTA confirms that transfer pricing rules apply to Related Party and Connected Person transactions, including transactions between UAE mainland and Free Zone entities.
5. Should UAE groups review their tax structure regularly?
Yes. Changes to ownership, business activities, transactions, Free Zone rules and Corporate Tax decisions can affect the group’s tax position. A periodic review can help identify potential compliance issues before they become more difficult to address.
Conclusion
Effective mainland free zone tax planning UAE is about aligning the group’s commercial structure with the UAE Corporate Tax rules. For multi-entity groups, the important questions are not simply where each company is registered. Businesses should examine Free Zone qualifying conditions, sources of income, Tax Group eligibility, related-party transactions, transfer pricing, substance and supporting records. Because the UAE Free Zone Corporate Tax framework continues to evolve, groups should review their arrangements against the current legislation and FTA guidance before implementing structural or tax-planning changes.
Disclaimer: This article is provided for general informational purposes only and does not constitute tax, legal, accounting or financial advice. UAE Corporate Tax and Free Zone rules may depend on the specific facts, activities, ownership structure and transactions of a business and may change as legislation and official guidance develop. Businesses should review the current UAE legislation and Federal Tax Authority guidance and obtain professional advice before making tax-planning or restructuring decisions.
Auditing different types of businesses is essential because every industry operates with unique financial processes, regulations, and risks. A manufacturing company manages…
Corporate governance and accounting are closely connected because both help businesses operate with honesty, transparency, and accountability. A strong governance framework ensures…
0 Comments