Outsourced Payroll vs In-House Payroll in the UAE: What SMEs Should Know
Could your UAE business manage payroll more efficiently in-house, or would outsourcing give your finance team more time and control? For UAE…
Read article
Is your UAE business carrying inventory that has been sitting on the shelves for months or even years?
Slow-moving and obsolete stock can tie up working capital, distort inventory values and make reported profits look stronger than the underlying economics. For UAE businesses, an appropriate inventory provision UAE approach can help reflect the recoverable value of stock in the financial statements. However, an accounting provision does not automatically mean the same amount is deductible for Corporate Tax. Understanding the difference between accounting treatment, inventory valuation and UAE Corporate Tax rules is therefore essential.
So, how should businesses identify obsolete stock, calculate a provision and determine its UAE Corporate Tax impact? Let’s examine the process step by step.
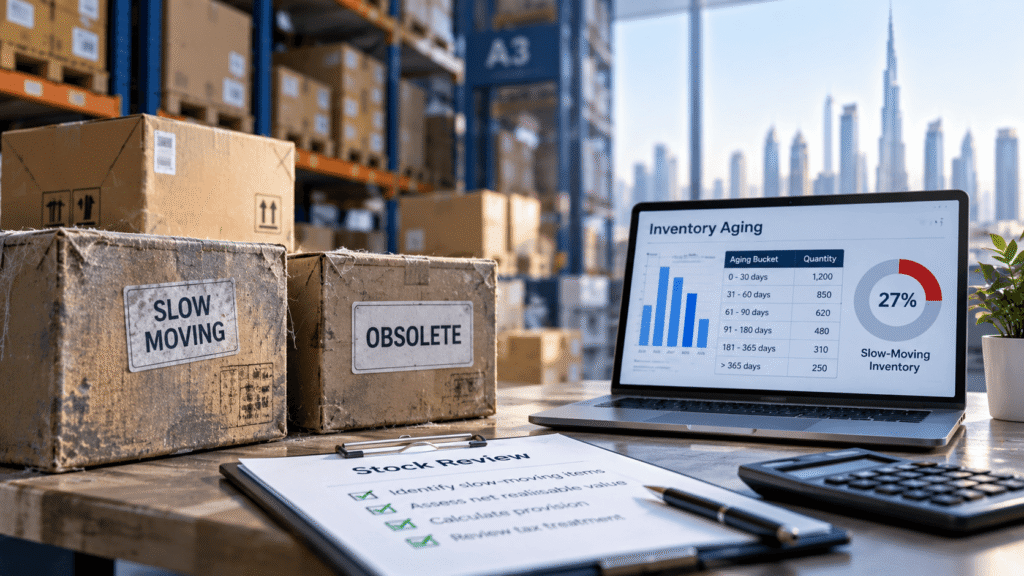
Inventory becomes slow-moving when it remains unsold or is consumed more slowly than expected. It may still have a realistic selling value, but its turnover is lower than normal. Obsolete inventory, on the other hand, may have little or no economic value because it is:
For example, a UAE electronics distributor may have AED 500,000 of smartphones in inventory. If newer models have entered the market and the older models can only be sold for AED 320,000 after selling costs, the company may need to consider whether the inventory’s carrying value should be reduced. This is where obsolete stock accounting UAE becomes particularly important.
Inventory is generally reported as an asset until it is sold or otherwise recognised as an expense. If stock is carried at an amount higher than what the business expects to recover, the financial statements may not provide a realistic picture of the company’s financial position. A proper review can help management:
For businesses with large inventories, regular ageing analysis should therefore form part of the financial close process.
There is no single ageing threshold that automatically makes inventory obsolete. Businesses should consider their products, industry, customer demand and expected selling cycle.
A useful inventory review can classify products into categories such as:
| Inventory status | Example | Potential action |
| Fast-moving | Regularly sold products | Normal monitoring |
| Slow-moving | Limited sales over several months | Review demand and pricing |
| At risk | Significant decline in sales | Assess recoverable value |
| Obsolete | No realistic future demand | Consider write-down/disposal |
| Damaged | Products cannot be sold normally | Assess recoverable amount |
Businesses can use inventory ageing reports to identify items requiring further investigation.
For example:
0–90 days: Normal stock
91–180 days: Monitor
181–365 days: Detailed review
Over 365 days: Management assessment for impairment/obsolescence
These are practical review categories rather than universal accounting rules. The appropriate period depends on the nature of the business.
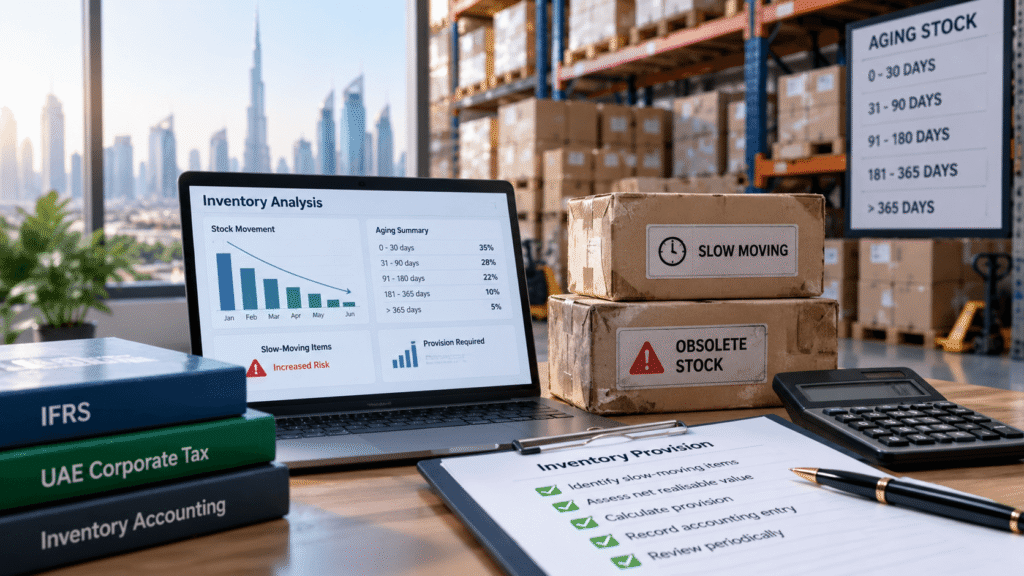
An inventory provision is an accounting adjustment used to reflect a reduction in the expected value of inventory when its carrying amount is not fully recoverable. Under commonly applied inventory accounting principles, inventory is generally measured at the lower of cost and net realisable value (NRV).
NRV broadly represents the estimated selling price in the ordinary course of business, less estimated costs necessary to complete and sell the inventory.
Therefore:
when the carrying cost is higher.
Simple example
A UAE retailer has obsolete products with:
Estimated NRV:
Potential write-down:
The accounting treatment should follow the applicable financial reporting framework and the company’s accounting policies.
The FTA confirms that UAE businesses should prepare financial statements using accounting standards accepted in the UAE, with IFRS being the most frequently used standard.
A practical inventory provision UAE process can follow these steps.
Start with SKU-level information showing:
Flag products with:
Review current market prices rather than relying solely on the original selling price.
Where applicable, consider costs required to complete and sell the goods.
If NRV is below the carrying cost, determine the required write-down under the applicable accounting framework.
Keep evidence supporting:
This documentation becomes particularly important when the adjustment is material.
The exact account names will depend on the company’s accounting system, but a simplified entry could be:
For example, if a business determines that AED 85,000 of inventory is no longer recoverable at its carrying amount:
The result is a reduction in the inventory carrying amount and recognition of the relevant accounting expense.
Businesses should also review the provision in subsequent periods. If circumstances change and inventory becomes recoverable, the accounting treatment should be reassessed under the applicable financial reporting requirements.
These terms should not be treated as interchangeable.
The product is still saleable, but sales are slower than expected. For example, a furniture company may normally sell a product within three months, but a particular model has remained in stock for eight months.
The product may no longer have a realistic market or may only be sold for a substantially reduced amount.
For example, a technology distributor holding an outdated product model after its replacement has been launched may need a significant write-down. Slow-moving does not automatically mean obsolete.
This distinction is important because a business should base its accounting adjustment on evidence about recoverability rather than applying an arbitrary percentage simply because inventory is old.
This is one of the most important parts of the issue. The starting point for UAE Corporate Tax is generally the accounting net profit or loss reported in the financial statements, followed by adjustments required under the Corporate Tax Law. The Ministry of Finance explains that taxable income starts with accounting income and that adjustments may be required for items that are exempt or non-deductible for Corporate Tax purposes.
The FTA similarly states that taxable income is based on accounting profit or loss after the adjustments specified under the Corporate Tax Law.
This means an accounting inventory write-down can affect accounting profit, but businesses should not automatically assume that every provision will produce an immediate Corporate Tax deduction.
The tax treatment needs to be assessed under the applicable Corporate Tax rules, accounting method, and circumstances.
The answer depends on the nature and timing of the accounting adjustment and the Corporate Tax rules applicable to the taxpayer. The general rule is that legitimate business expenditure incurred wholly and exclusively for the purposes of the business can generally be deductible, subject to the Corporate Tax Law and applicable limitations. The FTA explains this principle in its Corporate Tax guidance.
However, the UAE Corporate Tax regime contains specific rules concerning unrealized gains and losses. The FTA explains that taxpayers using the realization principle can exclude certain unrealized gains and losses until they are realized. The treatment can differ depending on whether assets and liabilities are held on capital or revenue account and on the election made by the taxpayer.
For inventory held for sale in the ordinary course of business, businesses therefore need to assess the specific Corporate Tax treatment rather than applying a blanket rule to every inventory provision.
Accounting treatment ≠ automatic tax treatment.
A company should reconcile its accounting profit to taxable income and determine whether a particular inventory adjustment requires a Corporate Tax adjustment. The current FTA Corporate Tax legislation and guidance should be checked when preparing the Corporate Tax return.
Consider a UAE trading company with:
The business may recognise the appropriate accounting adjustment under its applicable accounting framework. Its accounting profit would consequently be reduced by the relevant amount.
However, when preparing the Corporate Tax computation, the company should determine whether the accounting adjustment is recognised for tax purposes in the relevant Tax Period or whether a tax adjustment is required.
This is why the tax computation should not simply be:
Accounting profit − inventory provision = taxable income
Instead, the company should begin with accounting profit and apply the Corporate Tax adjustments required by law.
A well-supported inventory provision should be backed by evidence. Useful records include:
The FTA’s Corporate Tax framework places importance on appropriate financial information and records for determining taxable income. The Ministry of Finance specifically advises businesses to understand what financial information and records they need to maintain for Corporate Tax purposes.
Businesses can incorporate the following checklist into their month-end or year-end closing process:
Step 1: Generate inventory ageing report
Identify stock with prolonged periods without sales or movement.
Step 2: Categorise inventory
Separate normal, slow-moving, at-risk, damaged and obsolete products.
Step 3: Review sales trends
Compare historical sales with current demand.
Step 4: Determine estimated NRV
Use realistic selling prices and relevant selling/completion costs.
Step 5: Calculate required write-down
Compare inventory carrying value with its recoverable amount under the applicable accounting requirements.
Step 6: Record the accounting adjustment
Recognise the appropriate write-down or provision.
Step 7: Review Corporate Tax treatment
Determine whether a tax adjustment is required.
Step 8: Retain evidence
Keep calculations and supporting documents with the financial records.
This process can turn inventory provisions from a year-end surprise into a controlled accounting procedure.
Managing inventory provision UAE requirements becomes more challenging when a business has hundreds or thousands of SKUs, multiple warehouses, and constantly changing selling prices. Ripple Accountant can support UAE businesses with accounting and bookkeeping processes that help management maintain more reliable financial records and better visibility over inventory.
If your business has significant slow-moving or obsolete stock and you are unsure how to account for the provision or assess its Corporate Tax implications, contact Ripple Accountant for professional support tailored to your UAE business.
Slow-moving and obsolete inventory can have a significant impact on a UAE company’s financial statements, working capital and profitability. A structured review of inventory ageing, product demand, selling prices and net realisable value can help businesses identify stock that may need to be written down. However, the accounting provision and the Corporate Tax treatment should be considered separately. UAE Corporate Tax calculations generally start with accounting income, but specific tax adjustments may apply.
Disclaimer: This article is provided for general informational purposes only and does not constitute tax, accounting, legal, or other professional advice. Businesses should refer to the latest UAE legislation and official Federal Tax Authority and Ministry of Finance guidance before making tax or accounting decisions. Where specific treatment is required, consult a qualified UAE tax or accounting professional.
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
 Bookkeeping
Could your UAE business manage payroll more efficiently in-house, or would outsourcing give your finance team more time and control? For UAE…
Read article Corporate Tax
Is your UAE business earning AED 3 million or less in Revenue and does that automatically mean you do not have to…
Read article Audit
If an auditor selects only a small number of your company’s transactions for testing, how can that sample provide reliable evidence about…
Read articlePage 5 of 45
Book a free consultation and get clear answers for your business.
0 Comments