Do you know the difference between the VAT your business charges customers and the VAT it pays on business expenses?
Understanding input VAT vs output VAT UAE businesses deal with is essential for preparing accurate VAT returns. Output VAT generally relates to VAT charged or accounted for on taxable supplies, while input VAT relates to VAT incurred on eligible business purchases and expenses. The difference between the two helps determine whether a business has VAT to pay to the Federal Tax Authority (FTA) or is in a position where input tax exceeds output tax.
Read on to understand how input and output VAT work, when input VAT may be recoverable, and how businesses can reconcile both figures before preparing a UAE VAT return.
What Is Output VAT in the UAE?
Output VAT is the VAT a VAT-registered business charges or accounts for on its taxable supplies.
For example, suppose a UAE business provides a taxable service for AED 10,000 and charges VAT at 5%.
The calculation would be:
Value of service: AED 10,000
VAT at 5%: AED 500
Total invoice: AED 10,500
The AED 500 is output VAT.
The FTA’s VAT Return User Guide explains that output tax is VAT a taxable person calculates and charges on supplies of goods and services after VAT registration. It also notes that output tax can arise in certain deemed-supply and reverse-charge situations.
Output VAT therefore generally comes from the business’s taxable sales and other transactions where the business is required to account for VAT.
Where Does Output VAT Come From?
Depending on the business and its transactions, output VAT may arise from:
Taxable sales of goods
Taxable services
Certain deemed supplies
Certain transactions subject to the reverse-charge mechanism
Other transactions where the VAT legislation requires the business to account for output tax
The exact VAT treatment depends on the nature of the transaction and the applicable UAE VAT rules.
What Is Input VAT in the UAE?
Input VAT is VAT incurred by a business on goods and services it purchases or incurs for its business activities.
For example, a company purchases office equipment for AED 5,000 plus AED 250 VAT.
The AED 250 paid as VAT is input VAT.
However, input VAT should not automatically be treated as recoverable simply because VAT appears on a supplier invoice.
The FTA’s Input Tax Apportionment Guide explains that VAT incurred on goods and services can generally be recovered through the VAT return when the applicable conditions are satisfied. It also explains that recovery depends on how the goods or services are used.
Examples of Business Expenses That May Include Input VAT
Depending on the nature and use of the expense, input VAT may arise on:
Office supplies
Professional services
Business equipment
Software subscriptions
Rent and related expenses where VAT applies
Marketing services
Business travel expenses
Stock and inventory purchases
Other taxable business expenses
The fact that a business paid VAT does not by itself establish that the full amount can be recovered.
Input VAT vs Output VAT UAE: What Is the Difference?
The simplest way to understand the distinction is:
Input VAT
Output VAT
VAT incurred on eligible business purchases
VAT charged or accounted for on taxable supplies
Generally relates to purchases and expenses
Generally relates to sales and other taxable transactions
May be recoverable subject to applicable conditions
Generally becomes part of the VAT liability
Recorded through purchase and expense transactions
Recorded through sales and other output transactions
Contributes to determining the net VAT position
Contributes to determining the net VAT position
The two figures are brought together when a business prepares its VAT return.
How Does Input VAT and Output VAT Affect the VAT Return?
A VAT return essentially brings together the VAT a business is required to account for and the eligible input tax it can recover.
In simplified terms:
Output VAT − Recoverable Input VAT = Net VAT Position
This is a simplified illustration. The actual VAT return can include different categories, adjustments and transactions that need separate treatment.
The FTA’s VAT return filing guidance identifies sections for VAT on sales and other outputs, VAT on expenses and other inputs, and the resulting net VAT due.
What Happens When Input VAT Is Higher Than Output VAT?
A business may have a period where recoverable input VAT is higher than its output VAT.
This creates a net refundable position, subject to the applicable rules and the business’s circumstances.
The FTA provides a VAT refund service for registered taxable persons and states that refund applications require relevant information and supporting documents, including output and input tax reports and tax invoices/supporting documents for the relevant refund request.
A business should therefore distinguish between input VAT incurred and input VAT that is actually recoverable.
When Is Input VAT Recoverable in the UAE?
Input VAT recovery is subject to conditions.
The FTA’s Input Tax Apportionment Guide states that a registrant is entitled to recover input tax incurred on goods and services to the extent those goods or services are used, or intended to be used, for specified activities that allow recovery. It also explains that input VAT on expenses used solely for non-business purposes or wholly exempt supplies is not recoverable.
This means businesses should ask more than:
“Did we pay VAT?”
They should also ask:
“Was the expense used for a purpose that allows input VAT recovery, and do we have the required supporting records?”
Input VAT Related to Taxable Activities
Where a business expense is used wholly for activities that allow input VAT recovery, the applicable input VAT may generally be recoverable, subject to the relevant requirements.
Input VAT Related to Exempt Activities
Where an expense relates solely to exempt supplies or another purpose that does not allow recovery, the input VAT may not be recoverable.
Mixed-Use Expenses
Some expenses may relate partly to activities that allow input VAT recovery and partly to activities that do not.
In these circumstances, the business may need to determine the recoverable portion.
The FTA’s guidance explains that where goods or services are used partly for recoverable purposes and partly for other purposes, the business must determine the portion of input tax that can be recovered.
What Records Should Businesses Check Before Claiming Input VAT?
A business should maintain a clear connection between the expense, VAT amount and supporting documentation.
A review can include:
Supplier tax invoice
Supplier details
Invoice date
VAT amount
Nature of the expense
Business purpose
Accounting entry
VAT treatment
Recoverability
Relevant tax period
The FTA’s current public clarification on tax invoices and input tax recovery provides specific guidance on tax invoices and input tax recovery.
This is particularly important where a business has a large number of supplier invoices or uses automated accounting systems.
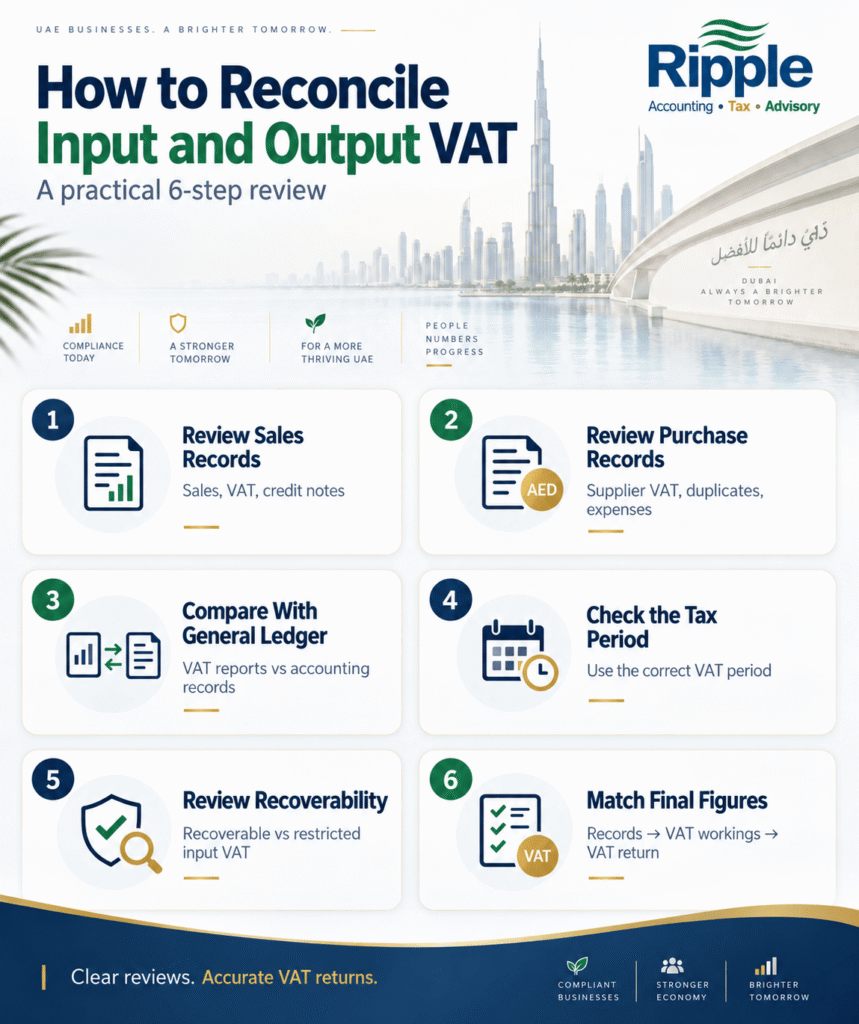
How to Reconcile Input and Output VAT
A regular reconciliation can help businesses identify differences before submitting a VAT return.
Step 1: Review Sales Records
Start with the sales ledger for the relevant VAT period.
Check:
Taxable sales
VAT amounts
Credit notes
Adjustments
Transactions requiring special VAT treatment
Step 2: Review Purchase Records
Check the purchase ledger and expense accounts.
Look for:
VAT charged by suppliers
Missing invoices
Duplicate invoices
Credit notes
Expenses with restricted or non-recoverable VAT
Unusual transactions
Step 3: Compare VAT Reports With the General Ledger
The VAT control accounts and VAT reports should be compared with the accounting records.
A difference does not necessarily mean there is an error, but it should be explainable.
Step 4: Check the Tax Period
Make sure transactions have been considered in the appropriate VAT period based on the applicable VAT rules.
This is particularly important for invoices, credit notes, imports and adjustments recorded around the end of a tax period.
Step 5: Review Input VAT Recoverability
Do not treat all VAT on purchases as automatically recoverable.
Review whether each significant or unusual expense meets the relevant recovery requirements.
Step 6: Compare the Final Figures With the VAT Return
Before submitting, compare the final VAT workings with the figures entered into the VAT return.
This creates a final control between:
Accounting records → VAT workings → VAT return
Common Mistakes When Comparing Input and Output VAT
Treating All Input VAT as Recoverable: A business may record VAT on a purchase but fail to consider whether the expense qualifies for recovery. This can overstate recoverable input VAT.
Using Sales VAT as the Only Output VAT Check: Businesses should consider whether there are transactions other than ordinary sales that require VAT treatment. The FTA notes that output tax can arise in certain deemed-supply and reverse-charge situations.
Ignoring Credit Notes: Credit notes can change the VAT position of an earlier transaction. They should therefore be included in the VAT review.
Failing to Reconcile VAT Accounts: A business may prepare its VAT return directly from accounting reports without checking whether the underlying VAT balances are complete and accurate.
Claiming VAT Without Adequate Documentation: Supporting records are an important part of the input VAT review process. Businesses should retain the documentation needed to support their VAT treatment and recovery position.
A Simple Input and Output VAT Review Checklist
Before preparing the VAT return, businesses can use the following checklist:
Review total taxable sales.
Check output VAT calculations.
Review credit notes and adjustments.
Identify transactions requiring special VAT treatment.
Review purchase invoices.
Check input VAT amounts.
Review input VAT recoverability.
Identify mixed-use expenses where relevant.
Check import-related VAT where applicable.
Reconcile VAT control accounts.
Compare VAT reports with the general ledger.
Check unusual movements against previous periods.
Confirm the final VAT figures before submission.
Retain supporting records.
The FTA states that VAT-registered businesses are required to file their VAT return and make related VAT payments within 28 days from the end of the relevant tax period.
A documented review before that deadline can reduce the risk of discovering discrepancies at the last minute.
How Ripple Accounting Can Help With Input and Output VAT
Understanding input VAT vs output VAT UAE businesses deal with is only useful when the underlying accounting records are accurate and properly reconciled.
Ripple Accountants can support UAE businesses with VAT registration and filing-related accounting requirements, including organising VAT records, reviewing input and output VAT figures and reconciling relevant accounting information before VAT return preparation.
If your business needs help reviewing input VAT, output VAT or the records supporting its VAT return, contact Ripple Accountants to discuss your requirements.
Email: info@uaetaxcompliance.ae
Phone: +971 52 356 5409
WhatsApp: +971 4 250 0833
FAQs
1. What is the difference between input VAT and output VAT in the UAE?
Input VAT is VAT incurred by a business on eligible purchases and expenses, while output VAT is VAT charged or accounted for on taxable supplies and certain other transactions. The two figures contribute to determining the business’s net VAT position.
2. Is all input VAT recoverable in the UAE?
No. Input VAT recovery is subject to applicable conditions. The FTA explains that recovery generally depends on the use of the goods or services and whether they relate to activities that allow input tax recovery.
3. How do you calculate the net VAT position?
In a simplified calculation, a business subtracts recoverable input VAT from output VAT:
Output VAT − Recoverable Input VAT = Net VAT payable or refundable position.
The actual VAT return can contain additional categories and adjustments.
4. What happens if input VAT is higher than output VAT?
If eligible recoverable input VAT exceeds output VAT for a tax period, the business may have a net refundable position, subject to the applicable requirements. The FTA provides a process through EmaraTax for eligible VAT refund requests.
5. How can a UAE business reconcile input and output VAT?
A business can compare its sales and purchase records with VAT reports, review credit notes and adjustments, check input VAT recovery, reconcile VAT control accounts and compare the final figures with the VAT return before submission.
Conclusion
Understanding input VAT vs output VAT UAE businesses report is fundamental to preparing an accurate VAT return. Output VAT generally relates to VAT charged or accounted for on taxable supplies, while input VAT relates to VAT incurred on business purchases and expenses. However, input VAT is not automatically recoverable simply because VAT has been paid. The applicable recovery conditions and supporting records need to be considered. A regular reconciliation between sales, purchases, VAT reports, accounting records and the VAT return can help businesses identify differences before filing.
Disclaimer: This article is provided for general informational purposes and does not constitute tax, legal or accounting advice. UAE VAT legislation, FTA guidance and administrative procedures may change. The VAT treatment of a particular transaction depends on its specific facts and the applicable legislation and guidance. Businesses should review the latest FTA requirements and obtain professional advice where appropriate before preparing or submitting a VAT return.
Environmental, Social, and Governance (ESG) reporting has become a critical part of modern corporate reporting. Investors, regulators, customers, and financial institutions increasingly…
Businesses are under constant pressure to process financial data faster, reduce manual work, and improve accuracy. Traditional accounting methods often rely on…
Businesses are expanding beyond domestic markets more than ever before. Companies buy products from overseas suppliers, sell to international customers, receive payments…
0 Comments