Outsourced Payroll vs In-House Payroll in the UAE: What SMEs Should Know
Could your UAE business manage payroll more efficiently in-house, or would outsourcing give your finance team more time and control? For UAE…
Read article
For UAE trading, retail, distribution, and manufacturing businesses, inventory costing can directly affect reported gross profit, closing inventory and the cost of goods sold. Choosing between FIFO and weighted average is therefore more than an accounting preference. It can influence how management evaluates margins and how financial statements reflect inventory movements.
Under IAS 2, businesses generally use either the first-in, first-out (FIFO) or weighted average cost formula for inventories that are ordinarily interchangeable. Understanding FIFO vs Weighted Average IFRS is essential for businesses preparing IFRS-based financial statements in the UAE, particularly when purchase prices fluctuate and inventory values affect reported financial results.
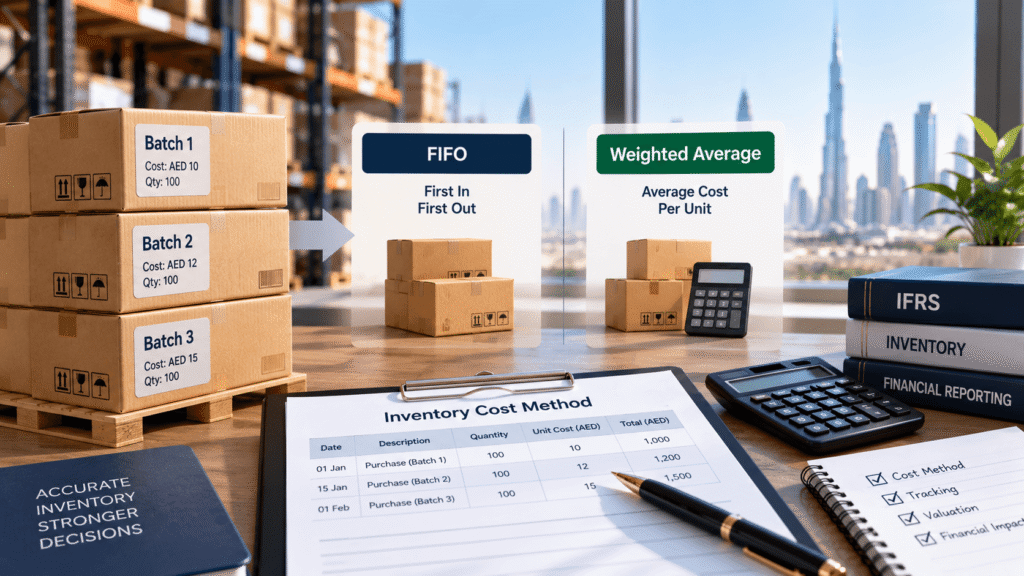
IAS 2 Inventories establishes the accounting treatment for inventory, including how inventory costs are determined and subsequently recognised as an expense.
Under IAS 2, inventory cost includes costs of purchase, costs of conversion and other costs incurred in bringing inventory to its present location and condition. For ordinarily interchangeable inventory, the standard permits two cost formulas:
For items that are not ordinarily interchangeable or are segregated for specific projects, specific identification of individual costs may be appropriate.
IAS 2 also requires inventory to be measured at the lower of cost and net realisable value (NRV). This means simply calculating the historical cost is not always enough; businesses also need to consider whether inventory can still be recovered through its expected sale.
The UAE Federal Tax Authority states that financial statements for UAE Corporate Tax purposes should be prepared using accounting standards accepted in the UAE, with IFRS being the most frequently used accounting standard.
Therefore, businesses using IFRS need a consistent and properly documented approach to IAS 2 inventory costing.
FIFO means first in, first out. The method assumes that the inventory purchased or produced first is sold first. As a result, the units remaining in closing inventory are generally associated with the most recent purchases.
For example, suppose a UAE distributor purchases:
| Purchase | Quantity | Cost per unit |
| First purchase | 100 units | AED 20 |
| Second purchase | 100 units | AED 25 |
| Third purchase | 100 units | AED 30 |
If the business sells 150 units, FIFO assumes that the first 100 units sold cost AED 20 each and the next 50 cost AED 25 each.
Therefore:
COGS = (100 × AED 20) + (50 × AED 25) = AED 3,250
The remaining 150 units consist of:
So closing inventory is AED 4,250.
FIFO can therefore result in closing inventory that more closely reflects recent purchase costs when prices are changing.
The weighted average method combines the cost of similar inventory items and calculates an average cost per unit.
Using the same example:
Total cost = AED 7,500
Total units = 300
Weighted average cost per unit:
AED 7,500 ÷ 300 = AED 25 per unit
If the company sells 150 units, COGS would be:
150 × AED 25 = AED 3,750
The remaining 150 units would also have a carrying amount of:
150 × AED 25 = AED 3,750
IAS 2 permits the weighted average to be calculated periodically or, depending on the circumstances, as each additional shipment is received.
The main difference is how each method assigns costs to inventory sold and inventory remaining.
| Factor | FIFO | Weighted Average |
| Cost assumption | Oldest costs are issued first | Costs are averaged |
| Closing inventory | Generally reflects newer costs | Reflects average costs |
| COGS during rising prices | Generally lower | Generally higher than FIFO |
| Profit during rising prices | Generally higher | Generally lower than FIFO |
| Price volatility | More sensitive to purchase-cost sequence | Smooths cost fluctuations |
| Inventory tracking | Can require detailed layer tracking | Generally simpler |
| Suitable environment | Businesses where cost layers are useful | Businesses with frequent purchases of similar goods |
The actual financial effect depends on the company’s purchasing pattern and price movements. Businesses should therefore avoid assuming that one method will always produce a particular result.
The choice of inventory costing methods under IFRS affects the amount transferred from inventory to cost of goods sold when inventory is sold. When purchase prices are increasing, FIFO generally assigns older, lower costs to COGS. This can produce:
Weighted average, by contrast, spreads the effect of price increases across units. When prices are falling, the relative effect can change.
This is why inventory costing should be considered alongside gross margin analysis. A sudden change in reported gross margin may not necessarily mean selling prices or operating performance have changed; inventory purchase costs and the selected costing formula can also contribute.
There is no universal answer. A UAE trading company should select the method that appropriately reflects its inventory characteristics, accounting policies, systems and reporting requirements.
FIFO may be useful when:
For businesses dealing with goods that can become obsolete, the physical flow of inventory may also make FIFO operationally intuitive. However, the accounting assumption should not be confused with the actual physical movement of every item.
Weighted average may be practical when:
For distributors and wholesalers handling high volumes of interchangeable products, weighted average can simplify inventory costing and reduce the impact of individual purchase-price fluctuations.
Inventory costing can affect accounting profit because it influences COGS and closing inventory. The FTA explains that UAE Corporate Tax taxable income starts with the business’s accounting net profit or loss, followed by adjustments required under the Corporate Tax Law.
This means accurate inventory accounting is relevant to the financial statements that form the starting point for determining taxable income.
However, businesses should not assume that choosing FIFO or weighted average automatically creates a separate tax deduction or tax advantage. The accounting treatment and applicable UAE Corporate Tax adjustments need to be considered together.
The FTA’s Accounting Standards and Interaction with Corporate Tax guidance explains how accounting standards interact with UAE Corporate Tax requirements.
Businesses should therefore maintain a clear accounting policy and ensure that inventory records support the figures reported in their financial statements.
Selecting an inventory costing method is only one part of effective inventory accounting. UAE businesses should also establish controls covering:
Before selecting an inventory costing method, management should consider five questions:
The decision should also be reviewed alongside the company’s financial reporting requirements and inventory management processes.
The objective should not be to select the method that produces the highest profit. Instead, the business should select an appropriate accounting policy, apply it consistently and maintain reliable supporting records.
Ripple Accountant can help businesses establish stronger accounting processes covering inventory records, reconciliations, month-end reporting and financial statement preparation. For businesses, professional accounting support can also help ensure that the selected approach is properly documented, consistently applied and aligned with the company’s reporting requirements.
If your UAE business needs support with inventory accounting, bookkeeping, financial reporting or UAE Corporate Tax compliance, contact Ripple Accountant to discuss your requirements.
Yes. IAS 2 permits FIFO for assigning the cost of ordinarily interchangeable inventory. Weighted average is also permitted.
Yes. IAS 2 permits the weighted average cost formula for ordinarily interchangeable inventory.
When inventory purchase prices are rising, FIFO will generally result in lower COGS and therefore higher gross profit than weighted average. The result can differ when prices fall or fluctuate differently.
Not automatically. FIFO can affect accounting COGS and profit, but UAE taxable income is determined from accounting profit after the adjustments required by the Corporate Tax Law.
IAS 2 requires the same cost formula for inventories having a similar nature and use. Different formulas may be justified for inventories with a different nature or use, but differences in geographical location or tax rules alone do not justify different formulas.
The choice between FIFO vs Weighted Average IFRS is an important inventory accounting decision for UAE businesses. IAS 2 permits both methods for ordinarily interchangeable inventory, but each produces a different pattern of COGS and closing inventory when purchase prices change. FIFO generally assigns older costs to goods sold, while weighted average spreads costs across similar inventory. The right choice depends on the nature of the inventory, purchasing patterns, systems, and accounting policy, not simply on which method produces a preferred profit figure.
Disclaimer: This article is provided for general informational purposes only and does not constitute tax, accounting, legal, or professional advice. Regulations and requirements may change, and their application can vary depending on individual business circumstances. Readers should refer to the latest information from the relevant UAE authorities and seek professional advice where appropriate.
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
 Bookkeeping
Could your UAE business manage payroll more efficiently in-house, or would outsourcing give your finance team more time and control? For UAE…
Read article Corporate Tax
Is your UAE business earning AED 3 million or less in Revenue and does that automatically mean you do not have to…
Read article Audit
If an auditor selects only a small number of your company’s transactions for testing, how can that sample provide reliable evidence about…
Read articlePage 5 of 45
Book a free consultation and get clear answers for your business.
0 Comments