DMTT Reporting Calendar UAE: Roles for Subsidiaries and Parent Companies
M Maria September 1, 2026 12 min read
Who is responsible for Pillar Two reporting when a multinational group has several UAE entities?
This question is becoming increasingly important as the UAE implements its Domestic Minimum Top-up Tax (DMTT) under Pillar Two. For groups operating through multiple UAE subsidiaries, simply knowing the tax rate is not enough. Finance teams need a clear DMTT reporting calendar UAE that identifies deadlines, data owners, reporting entities and the responsibilities of the parent company.
The UAE DMTT generally applies to UAE Constituent Entities that are members of MNE groups meeting the €750 million global revenue threshold in at least two of the four preceding financial years. The regime applies to financial years beginning on or after 1 January 2025.
So, how should a multinational group organise its UAE DMTT reporting process? Let us break the responsibilities and timeline down step by step.
What Is the UAE DMTT?
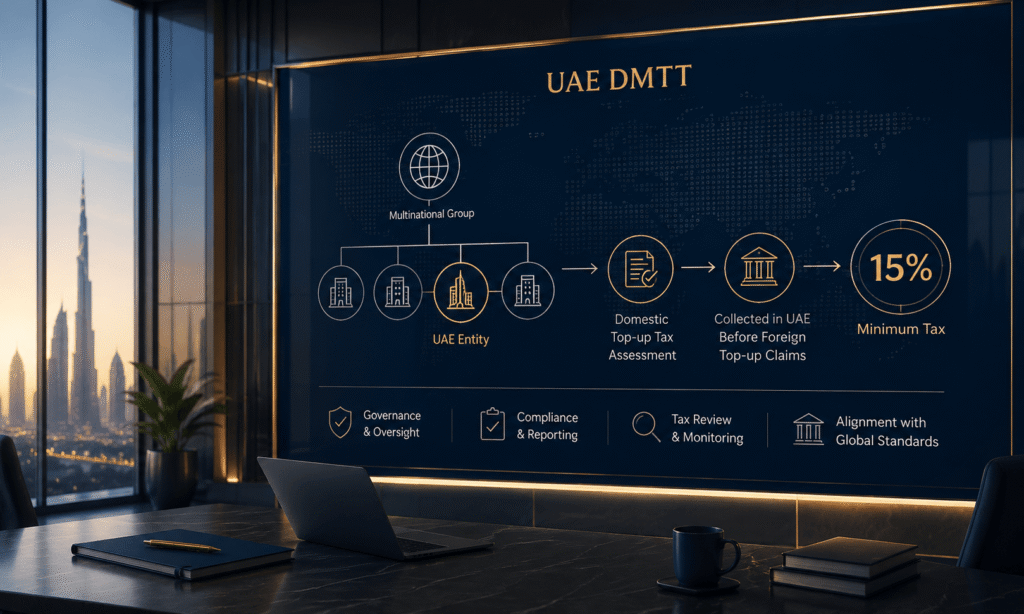
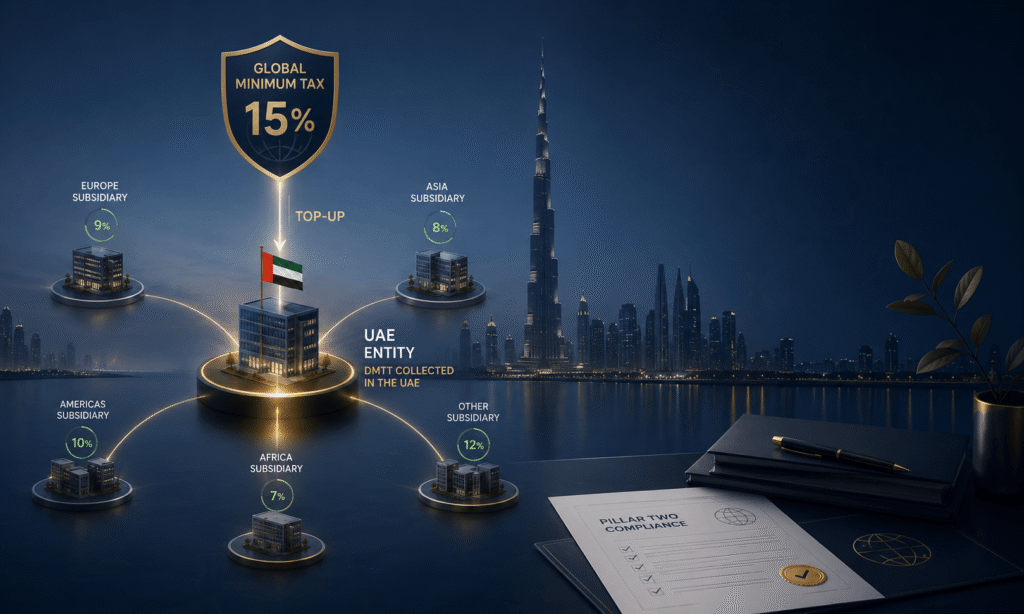
The UAE Domestic Minimum Top-up Tax is part of the global OECD/G20 Pillar Two framework. The DMTT is designed to apply a minimum effective tax framework to qualifying multinational enterprise groups. In the UAE, it applies to Constituent Entities belonging to MNE groups that meet the €750 million consolidated revenue threshold in at least two of the four financial years immediately preceding the relevant year.
The UAE DMTT applies for financial years beginning on or after 1 January 2025.
This means that multinational groups with UAE operations need to consider DMTT as a separate compliance workstream rather than treating it as simply another part of their ordinary UAE Corporate Tax filing.
DMTT Reporting Is a Group Exercise
A UAE subsidiary may be only one entity within a much larger multinational group, but its financial and tax data can form part of the group’s Pillar Two calculations. The parent company or designated reporting team may therefore need information from each UAE entity covering areas such as:
Financial accounting information
Covered taxes
Deferred tax information
Revenue
Profit or loss
Payroll and employees
Tangible assets
Ownership structures
Related entities
Corporate restructuring
Pillar Two adjustments
Safe-harbour information
The exact information required depends on the group’s reporting structure and the applicable Pillar Two rules.
This is why a DMTT group reporting calendar should allocate responsibilities at entity level rather than simply assigning the entire task to the group tax department.
Who Is Required to File the Pillar Two Information Return?
A major development for UAE businesses came on 25 August 2026, when the Ministry of Finance issued Ministerial Decision No. 133 of 2026.
The decision specifies the entities required to file the Pillar Two Information Return with the Federal Tax Authority. According to the Ministry of Finance, these include:
Each UAE Constituent Entity, excluding an Investment Entity
Each UAE Joint Venture
Each UAE JV Subsidiary
Certain Stateless Constituent Entities that are Reverse Hybrid Entities created under UAE law
The decision also allows the Pillar Two Information Return to be filed directly by the relevant entity or by a Designated Local Entity on its behalf. It applies to Fiscal Years beginning on or after 1 January 2025.
Official government document
Businesses should refer directly to Ministerial Decision No. 133 of 2026 when determining which UAE entities are required to file. The UAE Ministry of Finance’s official Financial Legislation database provides the decision and downloadable legislation.
This is preferable to relying solely on third-party summaries because the decision itself is the authoritative source for the filing entities.
What Is the DMTT Reporting Deadline?
The UAE’s Cabinet Decision No. 142 of 2024 provides the core filing timeline for the Top-up Tax Return. Under Article 8.1.2, the Top-up Tax Return must generally be filed no later than 15 months after the last day of the Reporting Fiscal Year.
For the first Transition Year of any Constituent Entity of the MNE Group, the deadline is extended to 18 months after the last day of the Reporting Fiscal Year.
Example: Assume a UAE MNE group has a Reporting Fiscal Year ending on 31 December.
For a normal reporting year:
31 December year-end + 15 months = 31 March of the following year
For the first Transition Year:
31 December year-end + 18 months = 30 June of the following year
The transition rule is important because groups entering the UAE DMTT framework for the first time may have additional time for their initial reporting cycle.
Official legislation
The exact filing provision is contained in Cabinet Decision No. 142 of 2024 on the Imposition of Top-up Tax on Multinational Enterprises.
Businesses should use the legislation itself when confirming the applicable reporting period and transition-year treatment.
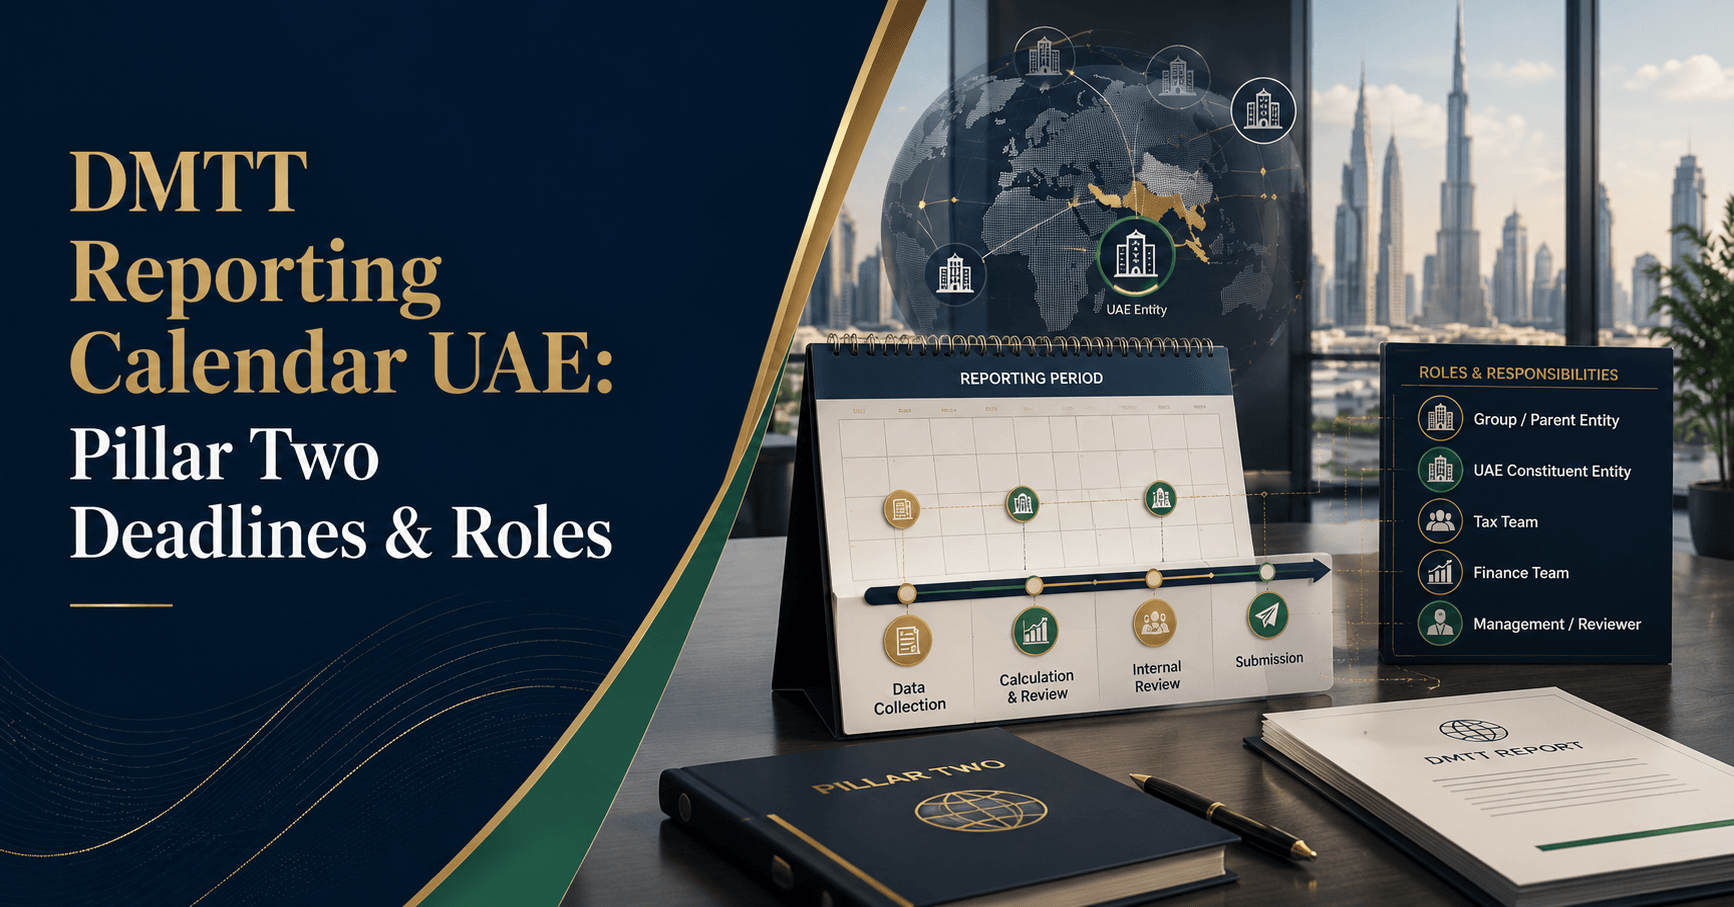
DMTT Reporting Calendar UAE for a MNE Group
A practical calendar should begin well before the statutory filing date. For example, a group with a 31 December financial year-end could structure its internal reporting process as follows:
Period
Key activity
Main responsibility
January
Confirm reporting entities and group structure
Parent / Group Tax
February–March
Collect UAE entity financial data
UAE subsidiaries
April–May
Review tax and accounting adjustments
Group Tax / Finance
June–July
Review Pillar Two calculations
Group Tax
August
Identify missing information and resolve discrepancies
UAE entities + Parent
September–October
Management review and technical review
Group Tax
November
Finalise reporting package
Parent / Designated Local Entity
December
Filing readiness and documentation
Filing entity
Statutory deadline
Submit required return/information
Responsible filing entity
The exact internal timetable should be adapted to the group’s reporting year and the applicable statutory requirements.
The key principle is simple:
Do not make the legal filing deadline the date on which data collection begins.
What Should UAE Subsidiaries Provide to the Parent Company?
A UAE subsidiary’s role is usually focused on providing accurate and timely local information. The parent or central tax team may request:
Financial information: The subsidiary may need to provide financial statements, trial balances, and relevant accounting schedules.
Tax information: The group may require details of covered taxes, UAE Corporate Tax positions and other tax information relevant to the Pillar Two calculation.
Employee and payroll data: Certain Pillar Two calculations may require information relating to employees and payroll costs.
Tangible asset information: Information concerning qualifying tangible assets may also be relevant to the group’s calculations and applicable safe harbors.
Corporate structure information: The UAE entity should communicate changes such as:
Acquisitions
Disposals
Mergers
Restructuring
New UAE subsidiaries
Changes in ownership
Changes in entity status
A reporting calendar should therefore include a monthly or quarterly data submission process, rather than waiting until the annual filing period.
What Is the Parent Company’s Role?
The parent company or central tax function typically coordinates the group-wide Pillar Two process. Its responsibilities may include:
Identifying entities within the MNE group.
Confirming whether the group meets the applicable revenue threshold.
Determining which jurisdictions are within scope.
Issuing data templates to UAE subsidiaries.
Reviewing information received from local entities.
Performing group-level calculations.
Assessing applicable safe harbours and elections.
Coordinating the Pillar Two Information Return.
Confirming which entity will submit the relevant information.
Maintaining documentation supporting the group’s calculations.
The parent company should also establish clear deadlines for each subsidiary.
For example:
UAE entity submission deadline: 30 June
Group review deadline: 31 July
Tax technical review: 31 August
Final group sign-off: 30 September
This creates a buffer before the statutory deadline.
What Is a Designated Local Entity?
The UAE rules allow the Pillar Two Information Return to be filed by a Designated Local Entity on behalf of relevant UAE entities. Ministerial Decision No. 133 of 2026 specifically confirms that the Pillar Two Information Return may be submitted either directly by the relevant Constituent Entity, Joint Venture or JV Subsidiary, or by the Designated Local Entity on its behalf.
This can be particularly useful for multinational groups with several UAE entities.
Instead of each UAE company independently managing the reporting process, the group may establish a coordinated local filing structure.
However, centralisation does not eliminate the responsibility of individual UAE entities to provide complete and accurate information to the designated reporting team.
DMTT Reporting Calendar vs Corporate Tax Calendar
Another important point is that DMTT and UAE Corporate Tax should not be placed into one generic tax deadline without distinction. They are separate compliance frameworks. A UAE company may therefore need to maintain:
Corporate Tax calendar
This can include:
Corporate Tax registration
Accounting close
Corporate Tax computation
Corporate Tax Return
Corporate Tax payment
DMTT/Pillar Two calendar
This can include:
Group scope assessment
UAE entity data collection
Pillar Two calculations
GloBE-related information
Top-up Tax Return
Pillar Two Information Return
Group reporting and review
Keeping the two calendars separate reduces the risk of confusing different deadlines or assigning the wrong responsibility to a local finance team.
Common DMTT Reporting Mistakes
Treating the parent company as the only responsible party: Even when reporting is centrally managed, UAE subsidiaries may need to provide significant information.
Starting data collection too late: Pillar Two reporting can involve multiple entities, jurisdictions and accounting adjustments. Waiting until the filing deadline approaches can create avoidable problems.
Ignoring UAE entity-level changes: A new subsidiary, acquisition or restructuring can affect the group’s reporting population.
Using inconsistent accounting data: If different UAE subsidiaries provide information using different accounting definitions or periods, the group may need substantial reconciliation work.
Confusing Corporate Tax with DMTT: A business can be compliant with its UAE Corporate Tax obligations while still having separate Pillar Two reporting responsibilities.
Failing to document decisions: The group should maintain evidence supporting its scope assessment, calculations, elections, safe-harbour positions and reporting decisions.
How to Build a Reliable DMTT Reporting Calendar
A practical calendar should contain five layers.
Layer 1: Entity mapping
Maintain a list of all UAE Constituent Entities, Joint Ventures, and other relevant entities.
Layer 2: Data ownership
Assign a responsible person for each information category.
For example:
Information
Suggested owner
Financial statements
UAE Finance
Tax data
UAE Tax / Finance
Payroll
HR / Payroll
Fixed assets
Finance
Group structure
Legal / Group Tax
Pillar Two calculations
Group Tax
Final filing
Designated filing entity
Layer 3: Internal deadlines
Set deadlines weeks or months before the statutory deadline.
Layer 4: Review controls
Include technical, accounting, and management review stages.
Layer 5: Evidence retention
Maintain copies of submitted information, calculations, supporting schedules and relevant correspondence.
This creates an audit trail and makes future reporting periods easier to manage.
Government Resources for UAE DMTT and Pillar Two
Because the UAE DMTT framework is evolving, businesses should rely on current government legislation and guidance.
1. UAE Ministry of Finance – Domestic Minimum Top-up Tax
The Ministry of Finance provides an official overview of the UAE DMTT, including the scope of the regime and the €750 million MNE revenue threshold.
This is the directly relevant government decision for determining which entities are required to file the Pillar Two Information Return. It applies to Fiscal Years beginning on or after 1 January 2025.
This is the key legislation for the UAE Top-up Tax framework and contains the 15-month general filing deadline and 18-month first-transition-year deadline for the Top-up Tax Return.
4. UAE Ministry of Finance Financial Legislation Database
The Ministry’s legislation database is useful for checking later amendments and additional Pillar Two decisions. As of August 2026, it lists both Ministerial Decision No. 133 of 2026 and Ministerial Decision No. 96 of 2026 concerning the Pillar Two framework.
For UAE subsidiaries and groups, DMTT reporting often requires close coordination between bookkeeping, financial reporting, tax data, and group-level requirements. Ripple Accountantcan supportUAE businesses with accounting and financial reporting processes that help keep the underlying data organized and ready for tax and group reporting. This can include maintaining accounting records, reconciling financial information, preparing management and financial reports, supporting tax-related data collection, and helping businesses establish structured reporting processes.
If your UAE business is part of an international group and you need help organising financial data or preparing for DMTT and Pillar Two reporting, contact Ripple Accountant to discuss your requirements and build a reporting process suited to your group structure.
Email: info@uaetaxcompliance.ae
Phone: +971 52 356 5409
WhatsApp: +971 4 250 0833
FAQ
1. What is the UAE DMTT?
The UAE Domestic Minimum Top-up Tax is the UAE’s implementation of a domestic minimum tax under the OECD/G20 Pillar Two framework. It generally applies to UAE Constituent Entities belonging to qualifying MNE groups meeting the €750 million revenue threshold in at least two of the four preceding financial years.
2. When does the UAE DMTT apply?
The UAE DMTT applies to financial years beginning on or after 1 January 2025.
3. What is the DMTT filing deadline?
Under Cabinet Decision No. 142 of 2024, the Top-up Tax Return is generally due within 15 months after the last day of the Reporting Fiscal Year. For the first Transition Year of any Constituent Entity of the MNE Group, the period is generally 18 months.
4. Do all UAE subsidiaries file the Pillar Two Information Return individually?
Not necessarily. Ministerial Decision No. 133 of 2026 permits the Pillar Two Information Return to be filed directly by the relevant entity or by a Designated Local Entity on its behalf, subject to the applicable rules.
5. What should UAE subsidiaries do if the parent company handles Pillar Two reporting?
The subsidiary should establish a clear internal process for providing the financial, tax, payroll, asset, and structural information requested by the group reporting team. Internal deadlines should be set well before the group’s final filing deadline.
Conclusion
A reliable DMTT reporting calendar UAE should connect the responsibilities of the parent company, UAE subsidiaries, and any designated local filing entity. The UAE DMTT framework applies to qualifying MNE groups from financial years beginning on or after 1 January 2025, while the 2026 Ministerial Decision No. 133 provides greater clarity on which UAE entities must file the Pillar Two Information Return. For multinational groups, Pillar Two compliance should be treated as an ongoing reporting process, not a task that starts immediately before the statutory deadline.
Disclaimer: This article is provided for general informational purposes only and does not constitute tax, accounting, or legal advice. UAE DMTT, Pillar Two, reporting and filing requirements may change through legislation, ministerial decisions, FTA guidance, or other official publications. Businesses should review the latest legislation and guidance issued by the UAE Ministry of Finance and Federal Tax Authority and obtain professional advice before making compliance decisions.
Environmental responsibilities have become an essential part of modern business operations. Companies across industries must consider not only their financial performance but…
Non-profit organizations play a vital role in supporting communities, advancing education, promoting healthcare, protecting the environment, and delivering humanitarian aid across the…
Businesses have traditionally relied on financial reports such as revenue, profit, cash flow, and expenses to evaluate performance. While these metrics remain…
0 Comments