VAT and Excise Tax Due Dates: Building a Reliable Compliance Calendar
Missing a UAE tax deadline can be costly. With VAT and Excise Tax following different filing cycles, how can businesses stay compliant…
Read article
What if your finance team could know the true financial position of the business before the month-end rush even began?
For many businesses, accounting becomes a month-end rush, with reconciliations, adjustments, reviews, and reporting completed under tight deadlines. Continuous close accounting takes a different approach by spreading these tasks throughout the month. Transactions are recorded promptly, accounts are reconciled regularly, and errors are identified earlier, reducing the workload at month-end. For UAE businesses, this can support more timely financial reporting and better management of accounting and Corporate Tax records.
Continuous close accounting is a finance process in which accounting activities are performed throughout the reporting period rather than being concentrated at the end of the month.
Under a traditional month-end close, finance teams may wait until the end of the reporting period to complete reconciliations, record accruals, review transactions, and investigate discrepancies. This creates a significant workload in a short period. With a continuous close model, these activities are distributed across the month.
For example, instead of reconciling bank accounts once at month-end, a finance team may reconcile them weekly or even daily. Instead of waiting until the last few days to investigate unusual transactions, exceptions can be reviewed as they arise.
The biggest difference is when accounting work happens. A traditional month-end close concentrates work at the end of the period. Continuous close distributes that work throughout the month.
| Traditional Month-End Close | Continuous Close |
| Work peaks at month-end | Work is spread throughout the month |
| Reconciliations may be delayed | Reconciliations happen regularly |
| Errors may be discovered late | Issues are identified earlier |
| Reporting waits for the close | Financial information is available sooner |
| Manual workload can be high | Automation can reduce repetitive work |
| Finance teams face deadline pressure | Workload becomes more predictable |
Continuous close therefore does not mean that businesses stop closing their books. It means that finance teams stop treating month-end as the only time when important accounting work gets done.
The traditional close can work for smaller businesses with limited transactions. However, as transaction volumes grow, concentrating accounting work at month-end can create several challenges.
Implementing continuous accounting does not mean completing the entire month-end close every day. Instead, the process involves completing appropriate tasks progressively throughout the month.
Sales, purchases, expenses, receipts, payments, and other transactions should be recorded as close as practical to when they occur. Delayed recording can reduce the usefulness of financial reports and create unnecessary work later.
Important accounts should be reconciled according to their transaction volume and risk.
For example:
High-volume accounts may require more frequent attention than low-volume accounts.
An unmatched transaction should not automatically be carried forward to month-end. The finance team should determine whether it represents:
Resolving these issues early prevents them from becoming part of a month-end backlog.
Recurring activities can be scheduled during the month rather than left until closing. These may include:
A close calendar can assign deadlines and responsibilities for recurring tasks. This allows finance managers to see which activities are complete, which are outstanding, and which require attention.
Once routine activities have been completed throughout the month, month-end can focus on:
This makes the final close more of a review and reporting process than a period of accumulated accounting work.
This can support faster and better-informed business decisions.
For UAE businesses, this is particularly relevant because the Federal Tax Authority requires taxpayers to maintain records and documents supporting information reported for Corporate Tax purposes.
The FTA also published Decision No. 4 of 2026, which sets out rules and requirements concerning information maintained in accounting records and commercial books.
Although continuous close accounting offers clear benefits, businesses need the right processes and controls to make it successful.
Continuous accounting can be particularly useful for UAE SMEs dealing with growing transaction volumes, digital payment channels, VAT obligations, Corporate Tax requirements, and increasing management reporting needs. A growing business may manage:
Waiting until month-end to review all these transactions can create unnecessary pressure. A continuous process allows finance teams to identify discrepancies and maintain more current financial information throughout the month.
Continuous accounting is not itself a Corporate Tax requirement. However, it can support the record-keeping process needed for tax compliance. The FTA requires taxpayers to maintain financial statements and supporting documents that substantiate information reported for Corporate Tax purposes.
For example, organized accounting records can make it easier to retrieve transaction details, invoices, bank information, and supporting documentation when required.
VAT-registered businesses also need reliable records supporting the figures reported in VAT returns. Regular reconciliation can help identify missing invoices, incorrect entries, and discrepancies before they affect reporting. This is particularly useful when businesses have large numbers of sales and purchase transactions.
Businesses do not need to transform their entire accounting function immediately. A gradual implementation is often more practical.
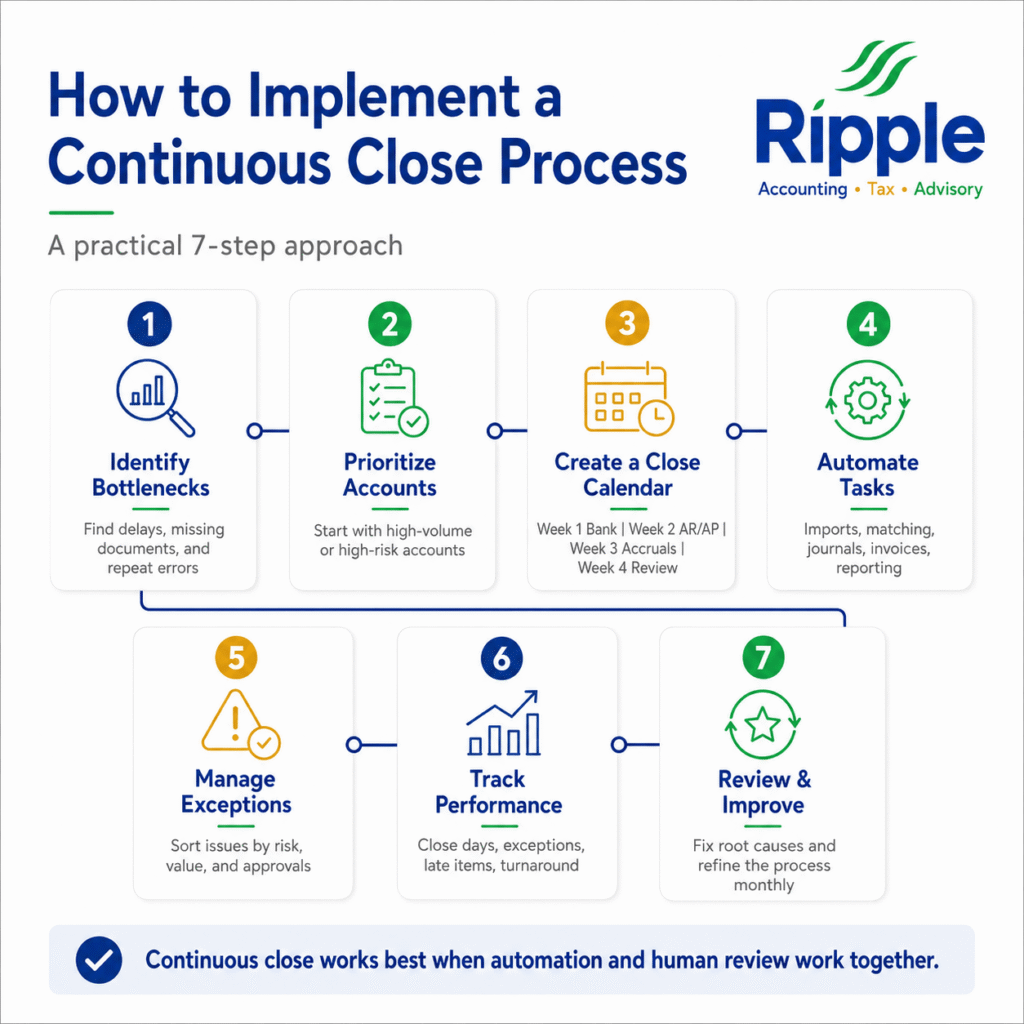
Review previous month-end closes and identify:
These areas can become the starting point for continuous accounting.
Begin with accounts that have high transaction volumes, significant financial value, or frequent discrepancies. Bank accounts, receivables, payables, payroll, and major expense accounts are often good starting points.
Instead of one large month-end checklist, distribute activities across the month. For example:
Week 1: Bank reconciliation and previous-period review
Week 2: Receivables and payables review
Week 3: Accruals and recurring journals
Week 4: Final reconciliation and management review
The schedule should be adapted to the company’s size and transaction volume.
Accounting automation can support activities such as:
However, businesses should clearly define which transactions can be automated and which require human review.
Not every exception has the same level of risk. Businesses can categorize exceptions into:
This helps finance teams focus their attention where it matters most.
Useful measures include:
These metrics help determine whether the continuous close process is actually improving financial operations.
If the same exception appears every month, businesses should investigate its underlying cause. Continuous accounting should itself be continuously improved.
Consider a UAE trading company with several bank accounts and hundreds of monthly transactions. Under a traditional process, the finance team may wait until month-end to download statements, reconcile transactions, identify missing invoices, review customer balances, record adjustments, and prepare reports. This creates a large workload in the final days.
With continuous accounting:
Throughout the month:
At month-end:
The work has not disappeared. It has been distributed more efficiently.
Moving toward continuous accounting requires more than software. Businesses need reliable bookkeeping, reconciliation processes, timely recording, financial controls, and appropriate review procedures.
Ripple Accountant can support UAE businesses with:
The objective is to help businesses keep their financial records organized and reduce unnecessary pressure during the month-end close.
Contact us today to discuss your payment, reconciliation, and financial control requirements.
Continuous close accounting is an approach where accounting, reconciliation, review, and other closing activities are performed throughout the month instead of being concentrated at month-end.
No. A formal period-end close is still required. Continuous accounting simply reduces the amount of routine work left for the final closing period.
Yes. It can be particularly useful for businesses experiencing growing transaction volumes, increasing reporting requirements, or recurring month-end pressure.
Continuous accounting focuses on performing accounting activities throughout the reporting period. Real-time finance is a broader concept focused on providing management with current financial information for decision-making.
Yes. Automation can help with repetitive tasks such as transaction imports, matching, recurring entries, and certain reconciliations. Exceptions and judgement-based transactions should still receive appropriate human review.
It can make financial records and supporting documentation more organized and easier to retrieve. However, continuous accounting itself is not a Corporate Tax compliance requirement.
The traditional month-end close does not have to remain a monthly accounting race. Continuous close accounting shifts routine accounting activities throughout the month, helping businesses identify errors earlier, improve financial visibility, reduce closing pressure, and strengthen financial controls. When these elements work together, month-end becomes less about catching up and more about reviewing, analyzing, and reporting reliable financial information.
Disclaimer: This article provides general information about continuous close accounting and financial processes for UAE businesses. It does not constitute accounting, tax, legal, or financial advice. UAE accounting and tax requirements may vary depending on a business’s activities, size, systems, and circumstances. Businesses should assess their specific requirements and consult a qualified accounting or tax professional where appropriate.
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
 VAT
Missing a UAE tax deadline can be costly. With VAT and Excise Tax following different filing cycles, how can businesses stay compliant…
Read article Corporate Tax
What is the accounting difference between operating a UAE branch and establishing a subsidiary? For businesses expanding into the UAE, the choice…
Read article Compliance
Is your business profitable on paper but still struggling to maintain enough cash? The problem may be tied to working capital rather…
Read articlePage 20 of 45
Book a free consultation and get clear answers for your business.
0 Comments