UAE Medical Insurance Receivables: Rejections & Reconciliation
Why can a healthcare provider have strong patient volumes and substantial billed revenue, yet still struggle with cash flow? The answer is…
Read article
Is your business still measuring performance against a budget that no longer reflects reality?
A budget gives your business a financial plan, but business conditions rarely remain unchanged throughout the year. Sales may increase or decline, costs may rise, customers may delay payments, or management may change its growth plans. This is where budget vs forecast and reforecast become important.
A budget sets the original financial targets, a forecast shows what the business currently expects to achieve, and a reforecast revises that outlook when significant assumptions change. Understanding the difference helps UAE finance teams make better decisions instead of relying on outdated numbers.
A budget is a financial plan that sets out what a business expects to earn, spend, and achieve over a particular period, usually the financial year. It translates management’s business plans into numbers. For example, a UAE company planning to expand may prepare a budget that includes:
The budget becomes the company’s financial baseline.
A comprehensive business budget may cover several areas:
For larger organizations, individual departments may also have their own budgets that are consolidated into an overall company budget.
A budget helps management answer questions such as:
It also provides a benchmark for measuring actual performance.
Imagine a Dubai-based professional services company preparing its annual budget.
It expects:
| Budget Item | Annual Budget |
| Revenue | AED 8 million |
| Operating expenses | AED 5.5 million |
| Expected operating profit | AED 2.5 million |
The AED 8 million revenue target and AED 5.5 million expense budget become the company’s original financial expectations.
Six months later, management can compare actual performance against these numbers. However, the original budget does not automatically tell management what will happen during the remaining six months. That is where the forecast becomes useful.
A financial forecast is an estimate of what a business currently expects to happen in the future based on the latest available information. Unlike the budget, a forecast is not simply based on assumptions made before the financial year begins. It incorporates what has actually happened.
For example, suppose the company originally budgeted AED 8 million in annual revenue. After six months, sales are lower than expected, and the customer pipeline has weakened. The latest forecast might show:
The budget has not necessarily changed. It remains the original benchmark.
The forecast simply tells management:
“Based on what we know today, we now expect revenue to be AED 7.2 million.”
A finance team uses actual results, sales pipeline, customer orders, expenses, cash flow, market conditions, and management assumptions to estimate future performance. For UAE businesses, these forecasts can also support broader financial planning and decision-making. By combining current data with realistic assumptions, a forecast provides a practical view of expected revenue, costs, and cash flow. It should be based on evidence rather than wishful thinking.
The main difference is purpose. A budget establishes the target. A forecast estimates the likely outcome. For example:
A finance team should not change the budget simply because the forecast changes. Keeping the original budget allows management to measure how actual performance compares with the original plan.
A rolling forecast is a forecasting approach in which the business continuously maintains a forward-looking period. For example, a business may always maintain a forecast for the next 12 months.
At the end of January, it forecasts February to January of the following year. At the end of February, it updates the forecast to cover March through February of the following year. This means the business always has a current view of the coming 12 months rather than relying only on an annual forecast prepared once.
A rolling forecast can be particularly useful for UAE SMEs operating in markets where sales, costs and cash requirements can change quickly.
Reforecasting means deliberately revising the existing financial outlook because important business assumptions have changed.
It is more than simply updating one month’s numbers. For example, imagine a UAE company originally expected:
During the year:
These changes may make the original forecast unrealistic. The finance team may therefore conduct a reforecast using the new assumptions. The revised outlook might become:
The purpose is not to make the business look better or worse. It is to give management a more realistic view of what is now expected.
Reforecasting may be appropriate when there is a material change such as:
However, not every small variance requires a reforecast.
If electricity costs are AED 5,000 higher than expected in one month, that may simply be a variance to investigate. If the business’s underlying cost structure has permanently changed, a reforecast may be justified.
These concepts are related but should not be confused.
A useful way to think about it is:
Forecast update = keep the outlook current.
Reforecast = reset the outlook because circumstances have materially changed.
The following table summarizes the key differences:
| Factor | Budget | Forecast | Reforecast |
| Main purpose | Set financial targets | Predict likely results | Revise the financial outlook |
| Timing | Usually prepared annually | Updated regularly | Prepared when significant changes occur |
| Flexibility | Relatively low | High | High |
| Based on | Original assumptions and strategy | Latest actuals and information | Revised assumptions and new information |
| Used for | Planning and performance measurement | Decision-making | Course correction |
| Main question | What did we plan? | Where are we heading? | What should we now expect? |
| Should it change? | Normally remains as the original benchmark | Yes | Yes, when justified |
The important point is that budget, forecast, and reforecast are not substitutes for one another.
A strong finance process can use all three.
A practical financial planning cycle can look like this:
At the beginning of the financial year, management establishes its financial targets.
For example:
Annual revenue target = AED 10 million
Each month, finance records actual revenue and expenses. Suppose after three months:
Budgeted revenue = AED 2.5 million
Actual revenue = AED 2.2 million
The team investigates the AED 300,000 variance.
Finance then considers current sales, customer orders and pipeline information. The latest forecast may indicate:
Expected annual revenue = AED 9.2 million
Management continues monitoring:
If conditions change significantly, management may formally revise the outlook. For example:
Original budget: AED 10 million
Previous forecast: AED 9.2 million
Reforecast: AED 8.5 million
The original AED 10 million budget should normally remain available for comparison. This allows management to see:
Original plan → Actual results → Current forecast → Revised outlook
That history is valuable because it shows how and why expectations changed.
The practical question for finance teams is not simply “budget vs forecast—which one is better?”
It is:
“When should we use each tool?”
For UAE SMEs, financial planning cannot stop with an annual budget. Businesses may experience changes in customer demand, operating costs, staffing requirements, supplier prices, financing needs and expansion plans throughout the year.
A company that prepares a budget in January and never updates its expectations may reach December still working from assumptions that are no longer realistic. This is why financial planning UAE businesses can rely on should combine historical performance with forward-looking information.
Revenue and cash flow should also be considered separately. For example, a UAE company could forecast AED 1 million in additional sales but still experience a cash shortage if customers take 60 or 90 days to pay.
This means finance teams should consider:
Revenue forecast + collection timing + payment commitments = cash-flow outlook
A cash-flow forecast can help management plan:
For many SMEs, this forward-looking cash visibility can be more useful than looking at profit alone.
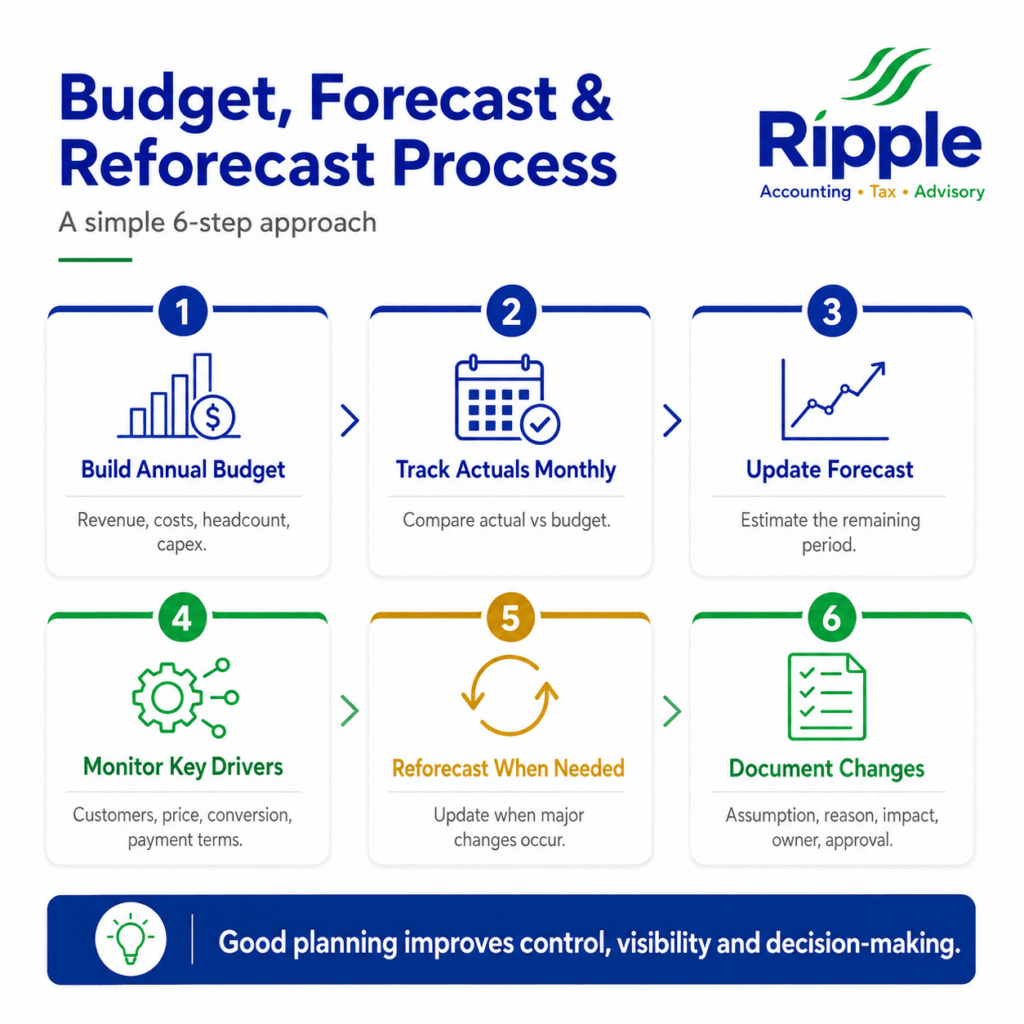
A practical process does not need to be complicated.
Set realistic assumptions for:
Record actual revenue, costs and cash movements and compare them with the budget.
Use actual results and current business information to estimate the remaining period.
Don’t only monitor financial numbers. Track the business drivers behind them.
For example:
Establish clear criteria for when a reforecast is required. For example, a major customer loss or significant change in operating costs may justify a formal reforecast.
When preparing a reforecast, record:
This makes the planning process more transparent and easier to review.
A reliable forecasting process should use agreed assumptions across the business.
A practical monthly management report can combine the budget and forecast rather than presenting them separately. A useful reporting pack may include:
For example:
| Metric | Budget | Actual | Latest Forecast |
| Revenue | AED 10m | AED 8.8m | AED 9.3m |
| Operating costs | AED 6m | AED 5.7m | AED 6.1m |
| Profit | AED 4m | AED 3.1m | AED 3.2m |
This gives management three perspectives:
What we planned → What happened → What we now expect
That is much more useful for decision-making than looking at the annual budget alone.
Effective financial forecasting UAE businesses can use requires accurate accounting records, realistic assumptions, and regular analysis.
Ripple Accountant can support UAE businesses with:
Not sure whether your business needs a new budget, updated forecast, or full reforecast?
Contact the Ripple Accountant team for professional support with budgeting, forecasting, and financial planning for your UAE business.
A budget represents the business’s original financial plan and targets, while a forecast estimates what the business currently expects to achieve based on actual performance and updated assumptions. The budget can remain fixed as a benchmark while the forecast changes throughout the year.
A forecast is regularly updated to reflect the latest information. A reforecast is a more deliberate revision of the financial outlook when significant changes make the existing assumptions or forecast unrealistic.
No. A reforecast updates the expected financial outcome based on changed circumstances. A budget establishes the original plan and normally remains available as a benchmark. Businesses should avoid replacing the original budget simply because their forecast changes.
There is no single frequency that works for every business. Many finance teams update forecasts monthly or quarterly, depending on the size, complexity, and volatility of the business. The important point is that the forecast should be updated often enough to support meaningful decisions.
A business should consider reforecasting when there is a significant and sustained change in its assumptions, such as losing a major customer, experiencing substantial cost increases, changing its expansion plans, or facing a material change in cash requirements.
Budget, forecast, and reforecast each serve a different purpose. For UAE SMEs, the strongest approach is not to choose one and ignore the others. Keep the original budget as your benchmark, update the forecast using current financial information, and reforecast when significant changes require a reset.
Disclaimer: This article provides general information about continuous close accounting and financial processes for UAE businesses. It does not constitute accounting, tax, legal, or financial advice. UAE accounting and tax requirements may vary depending on a business’s activities, size, systems, and circumstances. Businesses should assess their specific requirements and consult a qualified accounting or tax professional where appropriate.
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
 Audit
Why can a healthcare provider have strong patient volumes and substantial billed revenue, yet still struggle with cash flow? The answer is…
Read article VAT
Do schools in the UAE charge VAT on tuition fees, school transport, uniforms, extracurricular activities, and other services? The answer is not…
Read article Compliance
What happens when the payroll amount you approved doesn’t match the amount shown in your bank records? This is where WPS payroll…
Read articlePage 27 of 45
Book a free consultation and get clear answers for your business.
0 Comments