FTA Decision No. 15 of 2026: New Rules and Deadlines for UAE Corporate Tax Exemption Applications
Could an entity qualify for UAE Corporate Tax exemption but still face an issue because it applied at the wrong time or…
Read article
Are your bank statements showing a different balance from your accounting records?
For UAE businesses, even small differences can indicate missing transactions, duplicate entries, bank charges, timing differences or other bookkeeping errors. A regular bank reconciliation UAE process helps businesses compare their accounting records with actual bank activity and identify discrepancies before they affect financial reporting, cash-flow decisions or tax records. For SMEs, bank reconciliation is more than simply matching two balances. It creates a reliable link between the business’s accounting system and its actual cash position.
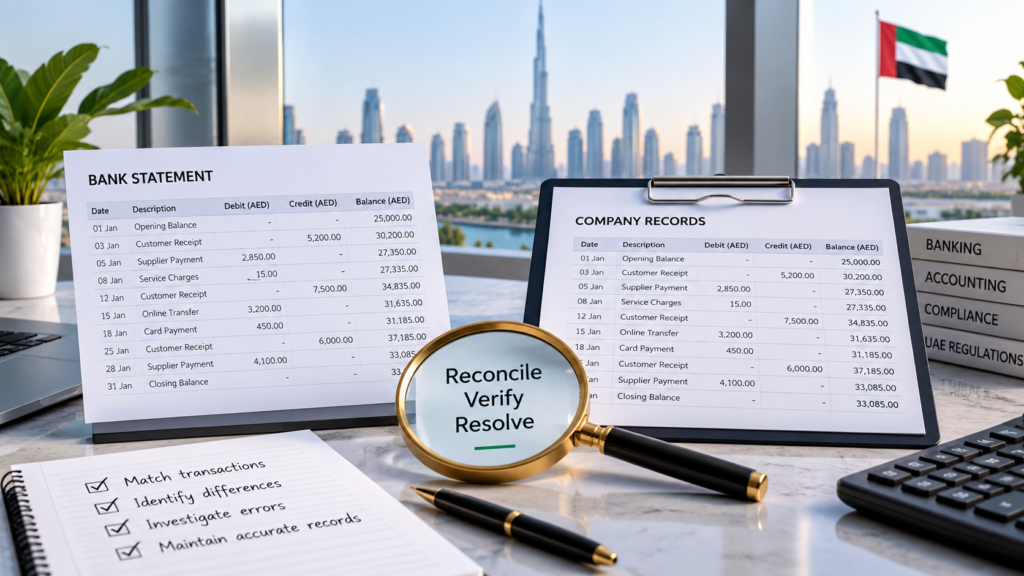
Bank reconciliation is the process of comparing the transactions and balance recorded in a company’s accounting system with the transactions and balance shown on its bank statement. The objective is to identify and explain differences between the two records.
For example, a company’s accounting software may show AED 125,000 in its bank account, while the bank statement shows AED 119,800. This does not automatically mean that the accounting records are wrong. The difference may result from:
Once these differences are identified, the bookkeeper can make the necessary adjustments and establish the correct reconciled balance.
Accurate cash records are essential for UAE SMEs because cash and bank transactions affect revenue, expenses, receivables, payables and financial statements.
A consistent bank reconciliation UAE procedure can help businesses:
A reconciliation can reveal transactions that have been entered incorrectly, recorded twice or omitted completely.
Unexpected withdrawals, transfers or payments can be investigated when bank statements are regularly reviewed.
A reconciled account provides management with a more reliable view of available cash and outstanding transactions.
Bank balances form part of a company’s financial records. Errors in cash balances can therefore affect the accuracy of financial statements.
UAE businesses subject to tax requirements must maintain accounting records and supporting documents. The Federal Tax Authority states that taxpayers should maintain records supporting information reported in Corporate Tax returns.
The UAE’s Tax Procedures framework also requires accounting records and commercial books to be maintained in a manner that enables tax obligations to be verified.
A consistent bank reconciliation process makes it easier for bookkeepers to identify discrepancies and correct them systematically.
Start with the bank statement for the period being reconciled. Ideally, businesses should reconcile accounts monthly, although businesses with high transaction volumes may benefit from weekly or even daily reconciliation.
Collect the statement for the exact period and ensure that the opening balance corresponds with the previous reconciliation.
Compare the opening balance in the accounting system with the opening balance shown on the bank statement.
If the opening balances do not agree, review the previous reconciliation before proceeding. An unresolved previous-period difference can carry forward and make the current reconciliation difficult.
Compare deposits appearing on the bank statement with receipts recorded in the accounting system. Check:
Mark transactions that match and investigate amounts appearing in one record but not the other.
Next, compare outgoing bank transactions with accounting entries. These may include:
Confirm that the amount, date and description are correctly recorded.
Some transactions appear on the bank statement before they are entered into the accounting system. Examples include:
These transactions should be recorded in the accounting system with appropriate supporting documentation.
Not every difference represents an accounting error. For example, a business may issue a cheque on 28 September, record it in its books, but the supplier may not deposit it until October. The September accounting balance will therefore differ from the September bank statement.
Similarly, a customer payment may be recorded by the business before the funds appear in the bank account. These legitimate timing differences should be documented rather than incorrectly adjusted.
If the difference cannot be explained by timing or bank-only transactions, investigate further. Review the:
Once the cause of a difference is established, post the appropriate accounting adjustment. For example, if the bank charged AED 150 that was not recorded in the books, the business may need to record the bank expense and reduce the relevant bank balance in its accounting system.
After all appropriate adjustments have been recorded, the adjusted accounting balance should agree with the bank balance after considering valid outstanding items.
The reconciliation should be reviewed and retained as part of the company’s accounting documentation.
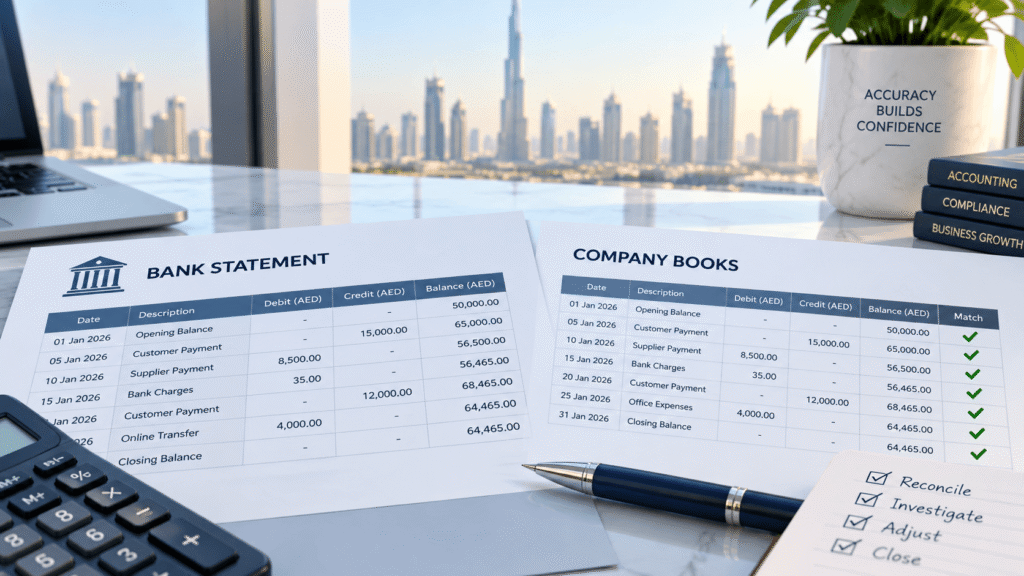
Businesses asking how to reconcile a business bank account UAE can use a simple three-part approach:
Bank statement → Accounting records → Difference investigation
First, obtain the relevant bank statement. Next, compare every transaction against the accounting ledger. Finally, classify every difference as either:
Do not simply force the accounting balance to equal the bank balance. Every adjustment should have a reasonable explanation and, where appropriate, supporting evidence.
Bank reconciliation is particularly useful for identifying recurring bookkeeping errors UAE businesses may experience.
Bank reconciliation should form part of a broader accounting record-keeping system rather than being treated as an isolated monthly task.
The UAE Tax Procedures framework identifies accounting records and commercial books as including records of payments and receipts, purchases and sales, revenues and expenditures, together with supporting documents such as invoices, contracts and correspondence.
The FTA also published FTA Decision No. 4 of 2026 concerning rules and requirements for maintaining information contained in accounting records and commercial books. The decision is listed in the FTA’s current legislation resources.
Businesses should therefore maintain an organised audit trail connecting bank transactions to the underlying accounting entries and supporting documents.
Record-retention requirements depend on the applicable UAE tax legislation and the type of record. For Corporate Tax purposes, the FTA states that records and documents should generally be kept for at least seven years following the end of the relevant Tax Period.
Businesses should therefore avoid treating bank statements and reconciliation documents as disposable working papers. Where they support accounting entries, tax calculations or financial reporting, they should be retained within the business’s document-management system according to the applicable requirements.
The Ministry of Finance also advises businesses to understand what financial information and records they need to maintain for Corporate Tax purposes.
Use this reconciliation checklist at each reconciliation period:
The ideal frequency depends on transaction volume and business complexity.
The important point is consistency. Waiting until year-end to reconcile bank accounts can make it much harder to trace old transactions and correct errors.
Delayed reconciliation can allow small accounting errors to become larger problems. For example, an omitted customer receipt may cause an incorrect receivable balance for several months. A duplicated expense may remain unnoticed until management reviews the financial statements. Unexplained bank charges can also accumulate.
Delayed reconciliation can also make it harder to locate supporting documents because invoices, receipts and payment confirmations become more difficult to trace as time passes. Regular reconciliation provides an early-warning system for these issues.
Managing bank reconciliation alongside invoicing, VAT records, payroll, accounts payable and other bookkeeping responsibilities can be challenging for SME owners.
Ripple Accountant provides accounting and bookkeeping support for UAE businesses, helping businesses maintain organised financial records and improve the accuracy of their accounting processes. Professional bookkeeping support can help businesses with:
Contact Ripple Accountant to discuss your requirements.
Bank reconciliation is the process of comparing a company’s accounting records with its bank statement to identify and explain differences. It helps businesses maintain accurate cash balances and detect accounting errors.
Many SMEs reconcile bank accounts monthly, while businesses with high transaction volumes may benefit from weekly or daily reconciliation. The appropriate frequency depends on transaction volume, business complexity and cash-flow requirements.
Common errors include duplicate entries, missing transactions, incorrect amounts, unrecorded bank charges, incorrect account classifications, unrecorded customer receipts and unexplained transfers.
Yes. While bank reconciliation itself should not be treated as a substitute for tax compliance, accurate reconciliations support reliable accounting records and help businesses maintain documentation supporting their financial information. The FTA requires Corporate Tax taxpayers to maintain records supporting information reported in their returns.
The FTA states that records and documents should generally be kept for at least seven years following the end of the relevant Corporate Tax period. Businesses should consider the specific requirements applicable to their records and circumstances.
A reliable bank reconciliation UAE process gives businesses greater confidence that their accounting records reflect actual financial activity. By regularly comparing bank statements with accounting records, SMEs can identify missing transactions, duplicate entries, bank charges, timing differences and other bookkeeping errors UAE businesses commonly face. The process is straightforward: obtain the bank statement, match transactions, investigate differences, record valid adjustments and retain supporting documentation. When performed consistently, reconciliation can improve financial reporting, cash-flow visibility and the reliability of records used for UAE tax compliance.
Disclaimer: This article is provided for general informational purposes only and does not constitute tax, accounting, legal or other professional advice. UAE tax legislation, record-keeping requirements and administrative procedures may change. Businesses should review the latest guidance issued by the Federal Tax Authority and Ministry of Finance and obtain professional advice based on their individual circumstances before making compliance decisions.
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
 Compliance
Could an entity qualify for UAE Corporate Tax exemption but still face an issue because it applied at the wrong time or…
Read article Audit
Is your UAE business calculating end-of-service gratuity correctly when an employee leaves, but forgetting to track the amount building up during their…
Read article Audit
Are you looking at your business numbers every month, or only checking them when cash gets tight or a major decision comes…
Read articlePage 3 of 45
Book a free consultation and get clear answers for your business.
0 Comments