UAE Corporate Tax Penalties: Registration, Filing and Payment
Have you missed a UAE Corporate Tax deadline and are unsure which penalty may apply to your business? UAE Corporate Tax compliance…
Read article
A construction company may complete work and earn revenue, yet still have part of its payment withheld by the customer as retention. This creates an important accounting question: when should retention be recognised, when is it a receivable, and how should expected credit loss (ECL) be measured? For UAE contractors, getting this treatment right supports accurate financial statements, stronger cash-flow management, and reliable Corporate Tax reporting.
Let’s look at how IFRS 15, IFRS 9, and UAE accounting requirements work together to manage retention receivables accounting.
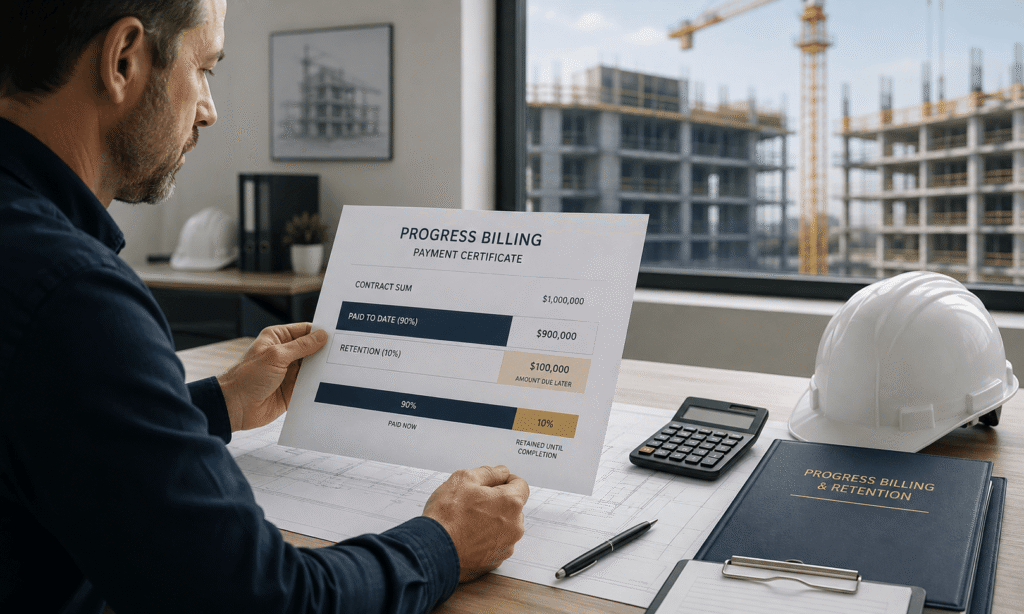
Retention is an amount withheld by a customer from payments due to a contractor until certain contractual conditions are satisfied. In construction projects, retention may be linked to completion of the project, correction of defects, expiry of a defects-liability period, final certification, or other conditions specified in the contract.
For example, suppose a UAE contractor completes AED 1 million of certified work. The contract provides for 10% retention.
The contractor may have:
The important point is that retention is not automatically a separate type of revenue. It is part of the consideration for construction work, and its accounting classification depends on the contractor’s rights under the contract.
Under IFRS 15, a receivable represents an unconditional right to consideration, while a contract asset arises when the right to consideration is still conditional on something other than the passage of time.
This distinction is particularly important for construction businesses because retention conditions can differ significantly from one contract to another.
Retention can remain outstanding for months or even years. As a result, a contractor’s accounts may show a significant balance that has already been earned economically but has not yet been collected.
Poor accounting treatment can create several problems, including:
For construction businesses operating in the UAE, retention should therefore be monitored at both the project level and accounting level.
A strong retention process connects the project contract, progress certificates, invoices, retention terms, expected release date, customer payment history and ECL assessment.
One of the most important questions in retention receivables accounting is whether the amount should be recorded as a receivable or a contract asset.
A contract asset arises when the contractor has transferred goods or services to the customer but does not yet have an unconditional right to consideration.
For example, assume a contractor has completed a stage of construction, but the contract states that the retention amount becomes payable only after:
If the contractor’s right to payment depends on something beyond simply waiting for the payment date, the amount may remain a contract asset.
IFRS 15 specifically states that a contract asset represents a right to consideration for goods or services transferred to a customer when that right is not yet unconditional. Contract assets are also assessed for impairment under IFRS 9.
A retention amount becomes a receivable when the contractor has an unconditional right to consideration and only the passage of time is required before payment. For instance, if all contractual conditions have been satisfied and the customer is simply required to pay the retention after 90 days, the balance may qualify as a receivable.
This distinction matters because IFRS 15 requires unconditional rights to consideration to be presented separately as receivables and accounted for under IFRS 9.
Therefore, contractors should not automatically classify every retention balance as a trade receivable.
IFRS 15 establishes the principles for recognising revenue from contracts with customers. Revenue is recognised to depict the transfer of promised goods or services to the customer for the consideration to which the entity expects to be entitled. Construction contracts frequently involve performance over time, but the appropriate IFRS 15 criteria must be assessed for each contract rather than assuming that every construction arrangement qualifies for over-time recognition.
A common accounting mistake is to delay revenue recognition simply because the customer has withheld retention.
The fact that cash has not yet been received does not, by itself, mean revenue has not been earned.
Consider this simplified example:
If the relevant IFRS 15 requirements for recognising AED 2 million of revenue have been satisfied, the contractor does not necessarily wait until the AED 200,000 retention is collected before recognising the related revenue.
Instead, the contractor determines the appropriate asset classification based on its contractual right to consideration.
Suppose a contractor completes and certifies AED 1 million of work.
The contract provides:
If the AED 100,000 is already an unconditional right to payment, the accounting may be presented as:
However, if the retention remains conditional on future performance, certification or another contractual requirement, the AED 100,000 may instead be recorded as a contract asset until the right becomes unconditional.
The contract terms should therefore drive the accounting treatment.
Correct journal entries help ensure that revenue, contract assets and receivables are not mixed together.
Where the contractor has recognised revenue and has an unconditional right to the consideration:
Dr Trade receivable – current amount
Dr Retention receivable – retained amount
Cr Revenue – total recognised amount
The exact presentation can vary depending on the entity’s accounting policies and contract structure.
Suppose AED 150,000 was previously recorded as a contract asset because payment depended on a contractual condition.
Once that condition is satisfied and the right becomes unconditional:
This entry changes the classification of the asset rather than recognising revenue again.
When the customer finally pays the retention:
The collection itself does not create new revenue. It settles the outstanding receivable.
Recognition is only one side of retention accounting. Contractors must also consider whether the outstanding amount may not be fully collected. IFRS 9 contains an expected credit loss model for financial assets. For qualifying trade receivables and contract assets arising from IFRS 15, the simplified approach requires lifetime expected credit losses in the circumstances specified by IFRS 9.
This means a construction company should not wait until a customer actually defaults before considering credit losses.
Retention balances can carry additional collection risk because payment may occur significantly later than normal progress invoices.
Potential risks include:
A contractor should therefore assess the recoverability of retention balances as part of its regular financial reporting process.
For qualifying trade receivables and contract assets, the IFRS 9 simplified approach can require lifetime ECL. A provision matrix can be a practical way of estimating losses, particularly where there is a large population of similar receivables.
However, an ECL calculation should not simply apply an arbitrary percentage to every retention balance.
The assessment should consider:
This produces a more supportable estimate of the amount that may ultimately be uncollectible.
Assume a UAE contractor has the following retention portfolio:
| Customer | Retention | Estimated ECL Rate | ECL |
| Customer A | AED 500,000 | 1% | AED 5,000 |
| Customer B | AED 300,000 | 3% | AED 9,000 |
| Customer C | AED 200,000 | 8% | AED 16,000 |
| Total | AED 1,000,000 | — | AED 30,000 |
The contractor could recognise an ECL allowance of AED 30,000, provided the assumptions and rates are supported by an appropriate assessment.
The journal entry would be:
Dr ECL impairment expense – AED 30,000
Cr Loss allowance for retention receivables – AED 30,000
If the expected loss subsequently decreases because the customer’s financial position improves or the risk assessment changes, the relevant allowance may be reversed, subject to IFRS 9 requirements.
The objective is to reflect expected credit losses rather than simply record losses after a customer has already failed to pay.
Retention should also be reviewed for appropriate current and non-current presentation.
For example, a contractor may have:
The accounting team should assess the relevant classification requirements and the contractual and expected settlement dates.
This information is particularly useful for management because a large retention balance can make the balance sheet appear strong while the business may still face significant short-term cash-flow pressure.
A retention ageing schedule should therefore show:
Retention receivables should be actively managed rather than left in the accounts until payment eventually arrives.
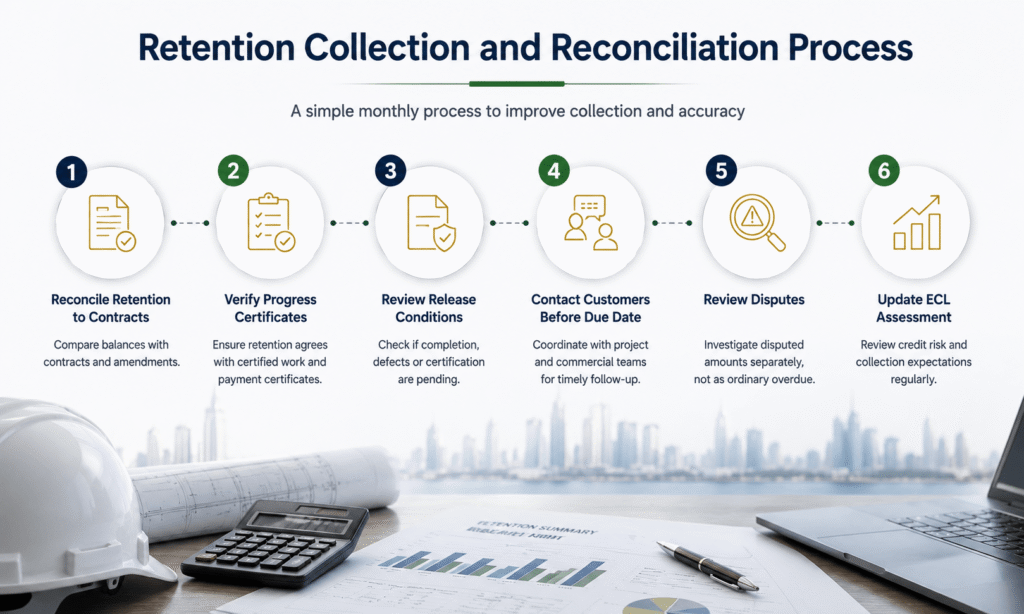
A practical monthly process can include the following steps.
Compare accounting balances with the underlying construction contracts and amendments.
Ensure the retention balance agrees with certified work and approved payment certificates.
Identify whether project completion, defect correction, certification or another condition is preventing collection.
The finance team should coordinate with project managers and commercial teams to follow up on upcoming retention releases.
Any disputed amount should be separately investigated rather than treated as an ordinary overdue receivable.
Customer credit risk and collection expectations should be reviewed regularly.
This process helps construction companies improve both accounting accuracy and working-capital management.
Accounting records are particularly important for UAE businesses because financial statements form an important starting point for determining taxable income under the UAE Corporate Tax framework. The UAE Ministry of Finance’s Ministerial Decision No. 114 of 2023 on the Accounting Standards and Methods for Corporate Tax Purposes sets out relevant accounting requirements. It confirms the use of IFRS as the applicable accounting standards and provides specific provisions concerning IFRS for SMEs and cash-basis accounting.
The Federal Tax Authority also provides an Accounting Standards and Interaction with Corporate Tax guide explaining how accounting standards interact with the UAE Corporate Tax regime. The FTA states that the guide is intended to assist businesses in understanding this interaction and should be read together with the relevant legislation and implementing decisions.
This is particularly relevant when retention balances, impairment expenses, contract assets and receivables are included in the financial statements used in the Corporate Tax process.
Businesses should distinguish between the accounting treatment under IFRS and any specific tax adjustments required under UAE Corporate Tax rules. An accounting entry does not automatically determine its final tax treatment.
UAE construction businesses should watch for these common errors:
Ripple Accountant can support UAE businesses with bookkeeping, financial reporting, receivables management, accounting reviews, and Corporate Tax-related accounting support. Professional accounting support can help construction businesses maintain organised records, reconcile retention balances, review outstanding receivables, and prepare reliable financial information.
Contact Ripple Accountant for a review of your accounting records and reporting requirements.
Not always. It is a receivable when the contractor has an unconditional right to consideration and only the passage of time is required before payment. If the right remains conditional on another contractual requirement, it may be a contract asset.
Retention does not automatically prevent revenue recognition. Revenue is recognised under IFRS 15 based on satisfaction of the applicable performance obligations and the consideration to which the entity expects to be entitled.
Where the retention qualifies as a financial asset within IFRS 9, an expected credit loss assessment is required. Qualifying trade receivables and contract assets under the IFRS 9 simplified approach are generally measured using lifetime ECL as specified by the standard.
Yes. If the contractor has performed but its right to payment remains conditional on something other than the passage of time, the balance can be a contract asset under IFRS 15.
The contractor should consider historical collection experience, ageing, customer-specific risks, disputes, payment behaviour, current conditions and relevant forward-looking information. A provision matrix may be appropriate for groups of similar balances.
Retention accounting can affect the financial statements used in the Corporate Tax process. However, businesses should separately assess whether any accounting item requires a specific tax adjustment under the UAE Corporate Tax rules.
Retention receivables are an important accounting issue for UAE construction companies because the balance can remain outstanding long after revenue has been recognised. The key is to distinguish between a contract asset and an unconditional receivable, apply IFRS 15 correctly, and assess qualifying balances for expected credit losses under IFRS 9.
Disclaimer: This article is provided for general informational and educational purposes only and does not constitute accounting, audit, tax, financial or legal advice. The accounting treatment of retention balances can vary depending on the specific construction contract, payment terms, certification requirements, performance obligations and other facts and circumstances. UAE Corporate Tax rules and official guidance may also be updated. Businesses should review the applicable IFRS requirements and UAE legislation and consult a qualified accountant, auditor or tax professional before making accounting or tax decisions.
Tell us a little about your business and our UAE tax experts will get back to you with clear, practical answers — no obligation.
 Corporate Tax
Have you missed a UAE Corporate Tax deadline and are unsure which penalty may apply to your business? UAE Corporate Tax compliance…
Read article Compliance
Could your UAE business need to prove its tax residency to a foreign tax authority before receiving cross-border tax benefits? A UAE…
Read article VAT
Has your UAE business accumulated more recoverable input VAT than output VAT, and are you unsure whether you can claim the difference…
Read articlePage 1 of 45
Book a free consultation and get clear answers for your business.
0 Comments